September 30, 2026
Bonus Content: Oil’s War Premium Is Draining. Here’s the Trade Traders Are Missing.
A 2026 Gold-Silver Production Story Still Under $1.
There is a specific frustration that hits investors after a major move.
You watch the obvious names run. You hear about them everywhere. Then suddenly everyone starts acting like it was obvious the whole time.
Gold and silver feel a little like that right now.
The majors moved first. The headlines followed. And now a lot of investors are looking at the sector wondering if there is still room.
But here’s the part people miss. The first move usually goes to the obvious names. The next move often starts when investors find the stories still sitting just outside the spotlight.
Here’s one of those stories sitting just outside the spotlight for now.
And it is not just another junior explorer asking investors to wait years for a possible discovery. It is targeting 2026 production from above-ground material already sitting at the surface.
That means potential cash flow may be coming into view much sooner than the usual junior mining timeline.
That is a rare setup: a near-production company with cash flow potential before the crowd fully connects it. In a gold and silver market that is already moving.
Find out why this gold-silver setup may not be obvious for long…
Oil’s War Premium Is Draining. Here’s the Trade Traders Are Missing.
Brent crude settled Tuesday at $102.59, down 2.6% on the session, and WTI dropped 3.5% to $89.38. The catalyst was not diplomacy: the Strait of Hormuz remains closed, and President Trump said Tuesday he does not know whether Iran will “give up yet.” What drove the selloff was supply math.
The War Premium Is Deflating Without a Peace Deal
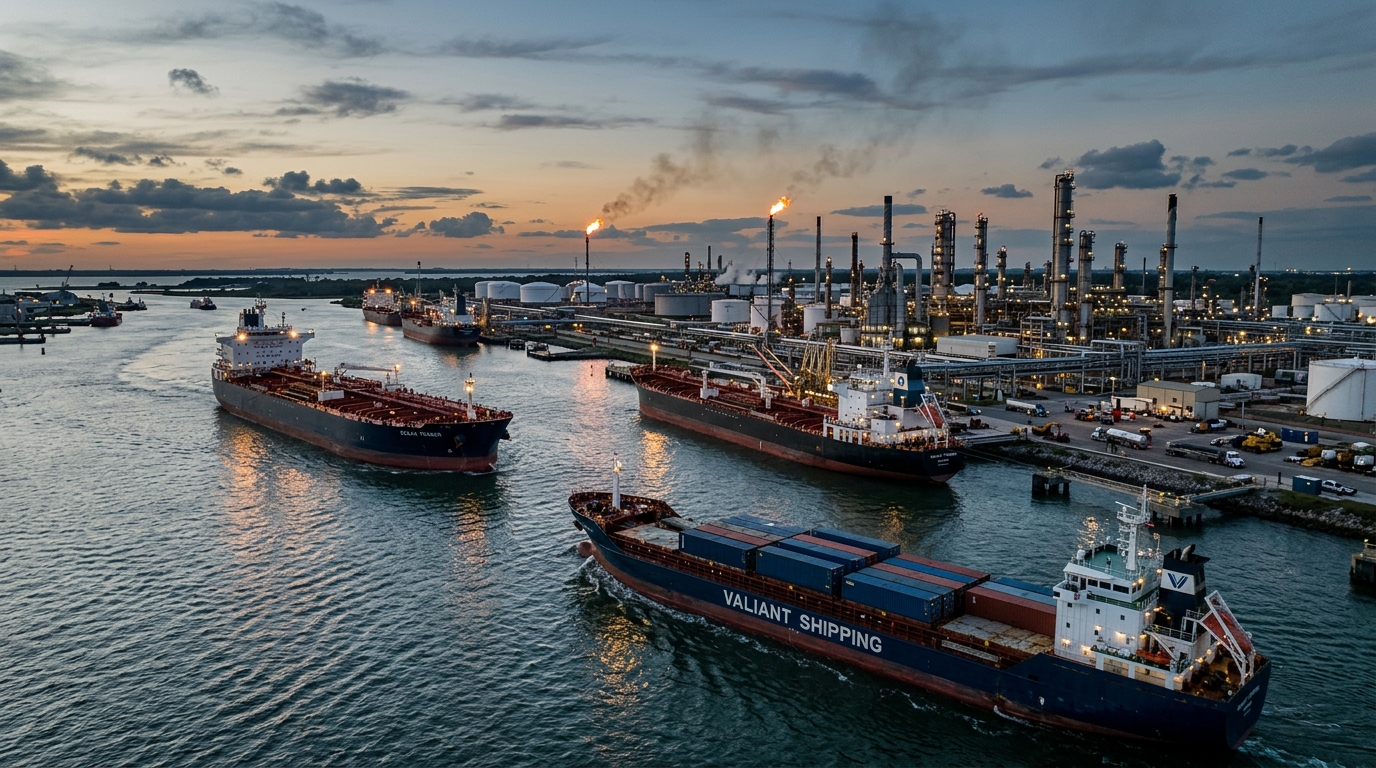
JPMorgan analysts led by Natasha Kaneva put regional crude exports at 17.5 million barrels a day, or roughly 98% of pre-war volumes. Kpler data cited by Reuters showed September exports already at 16.3 million barrels per day, the highest since the conflict began in late February. The route doing the heavy lifting is Saudi Arabia’s East-West Petroline, which had been knocked offline by drone strikes earlier this month. Bloomberg reported Monday that flows through the East-West pipeline to the Red Sea have been restored to at least 3.5 million barrels a day, about half of its 7 million b/d capacity, after repairs. U.S. military escorts through the strait for daytime transits account for much of the rest, with one oil analyst putting strait clearances near 13.5 million barrels a day on the latest seven-day average.
Hormuz is still shut in the formal sense. Iran proposed a seven-day phased reopening last week contingent on U.S. concessions; Trump rejected it. The war premium in Brent, which had pushed prices higher this month and left Brent headed for a monthly gain of around 13% at the time of Tuesday’s settlement, was never purely about volume. It was about tail risk. That tail is compressing even without a ceasefire, because enough barrels are now moving around the blockade to change the supply picture.
Sector Rotation: Who Wins, Who Loses
The trade traders are still holding, crude longs and tanker momentum, is the wrong side of this shift for at least two of those three legs.
Tanker operators like Frontline (FRO) and DHT Holdings (DHT) delivered extraordinary results on the back of war-era rerouting. Frontline reported $943.3 million in Q2 2026 revenue and a record $659.2 million in net income, $2.96 per share. DHT’s Q2 net profit hit $198.3 million, with spot-earning vessels delivering $162,600 per day in time charter equivalent earnings. Management called it the strongest quarter in company history. Those rates assumed a world where every barrel traveled the long way around. At 98% export recovery and a partially functioning strait, that assumption is weakening. DHT’s forward P/E sits at 9.2x and the stock trades near a 24% dividend yield, but analysts have already begun flagging that revenue is projected to decline 7.7% annually over the next three years as rates normalize.
Refiners flip the logic. Lower crude input costs are margin-positive, not margin-negative. Valero (VLO) ran up 134% year to date into late September on crack spreads that hit historic highs when crude was tight and refining capacity was constrained. Q2 revenue came in at $44.5 billion, up 58% year over year, with net income of $3.7 billion. Jefferies downgraded VLO to Hold on September 22 citing stretched valuation, but a crude selloff that compresses feedstock costs while product demand stays firm is structurally constructive for refining margins. The risk to watch is spread compression between heavy sour and light sweet crudes, which narrows Valero’s processing advantage on its Gulf Coast complex.
Airlines are the asymmetric beneficiary the market is slowest to price. American Airlines disclosed that Q2 fuel expense hit $4.9 billion, up 83.3% year over year, with the average jet fuel price running $4.05 per gallon versus $2.29 in Q2 2025. The company carried no hedge book. United (UAL) absorbed nearly $6 billion in incremental fuel costs versus its start-of-year plan. Both carriers have signaled they are prepared to moderate near-term capacity if elevated fuel persists. A durable move lower in WTI toward the high $80s removes the single largest cost headwind either airline faces. United posted Q2 total revenue of $17.7 billion, up 16%, and TRASM rose 12.1%, demonstrating real pricing power. Fuel relief at those revenue levels goes straight to operating leverage.
Scenario Modeling
Bull Case for Refiners and Airlines: The East-West pipeline restores closer to full 7 million b/d capacity over the next two weeks, Kpler export data continues printing near or above the 17.5 million b/d JPMorgan estimate, and Brent slides toward the $92-$95 range. Refining crack spreads remain elevated on constrained global capacity. Airline Q4 fuel bills drop materially from Q2’s $4.05-per-gallon average. VLO holds margin; AAL and UAL recover earnings guidance.
Base Case: Brent consolidates in the $98-$105 range as the Hormuz closure keeps a risk floor under prices while export rerouting caps the upside. Tanker spot rates compress 15-25% from Q2 peaks as voyage distances shorten. Refining margins stay firm but below record levels. Airlines absorb modest fuel relief but not enough to restore full Q4 guidance.
Bear Case for the Reversal Trade: Iran drone strikes disable the Petroline again, mirroring the mid-September disruption that removed 4-5 million barrels per day for weeks. Brent retest of $110+. Tanker rates spike again. Airline stocks give back any fuel-driven gains. The diplomatic channel closes entirely as Trump signals a post-midterm resumption of strikes.
Active Trader Framework
The key level in Brent is $100. A clean daily close below that figure, confirmed on volume, shifts the technical structure from range compression to trend reversal. WTI at $89.38 is already trading below its 20-day moving average; a hold below $90 into the weekly close supports the supply-recovery story. For tanker names, watch VLCC spot rate indices: a move below $100,000 per day signals the Q2 rate environment is not repeating in Q3. Airlines need WTI to stay below $92 for the fuel relief story to hold into Q4 earnings.
Risk management matters here precisely because the Hormuz closure has not ended. Every data point pointing toward supply recovery exists inside a conflict where a single infrastructure strike has already reversed the trend once this month. Position sizing should reflect that the bull and bear cases are closer in probability than the Tuesday price move implies. The trade is not about conviction in peace. It is about recognizing that the market is still priced for a war trade that the physical barrel count no longer fully supports.