October 1, 2026
Bonus Content: Micron Beat Every Number. Then the Stock Fell.
Miners worked this mountain by candlelight in 1898
They came in on horseback and dug by candlelight. By the 1940s the district went quiet.
One company now holds 37,000 hectares of it… and says most of the ground has never seen a modern drill.
The first holes are done. What the picks missed is the open question.
Take a closer look at what’s going on in this historic district.
Micron Beat Every Number. Then the Stock Fell.
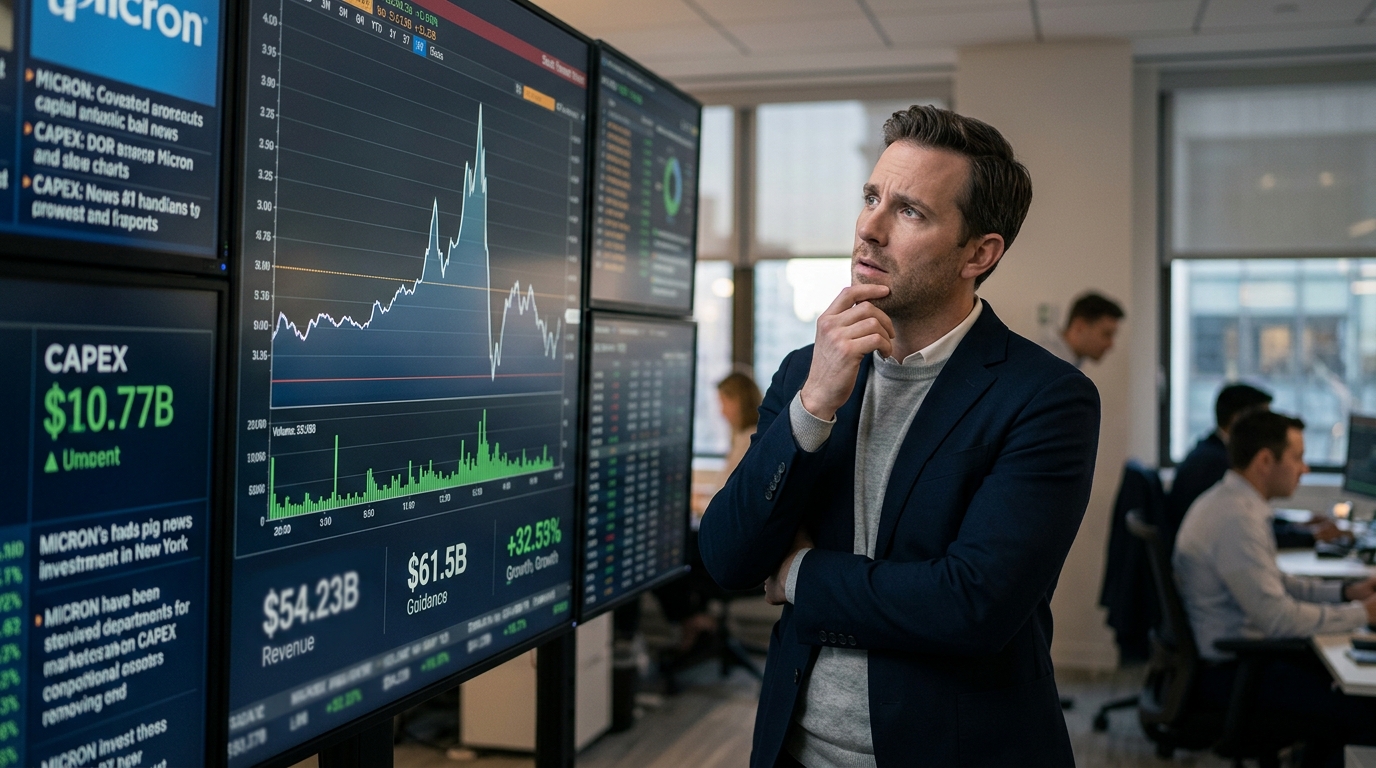
Micron delivered the kind of quarter that usually sends a stock limit-up: revenue of $54.23 billion and adjusted EPS of $33.42 both beat expectations. The core data center business unit captured the sharpest move, with revenue jumping 56% sequentially to a record $18.0 billion at a 90% gross margin. Fiscal Q1 guidance came in at about $61.5 billion in revenue, with adjusted EPS of $38.15. Yet after hours, MU barely moved and at points slipped about 1%.
The Capex Problem the Market Is Pricing
Micron reported net capital expenditures of $10.77 billion for the fourth quarter and $27.37 billion for the entire fiscal year. That number is rising. For fiscal Q1, Micron projected capex of around $11.5 billion and anticipates first-half fiscal 2027 capex of approximately $25 billion, with management explicitly guiding that the second half runs higher still. With first-half fiscal 2027 capex alone at $25 billion, full-year fiscal 2027 spending implies well above $50 billion, up sharply from the $27.37 billion in fiscal 2026.
Management raised fiscal 2027 capital expenditures versus earlier plans, with most of the increase aimed at construction rather than tools. CEO Sanjay Mehrotra tied the step-up to demand visibility through strategic customer agreements stretching toward the end of the decade, with the bulk of added construction spending meant to bring cleanroom capacity online in late calendar 2028 and beyond. That is a three-year bridge before new supply arrives.
Fiscal 2027 operating expenses will also increase by about $2.5 billion, mainly from R&D and incentive compensation, compressing the cash flow conversion that investors had priced in. Q4 adjusted free cash flow of $33.20 billion covered capex more than three times, but that ratio narrows materially as spending accelerates through fiscal 2027.
What the Reaction Means for SK Hynix, SanDisk, and Samsung
The sector read-through is not uniform. SK Hynix holds a 29.1% DRAM market share by revenue and commands a 56.4% share of the HBM market, according to IDC, giving it the most concentrated exposure to the supply-tightness trade. Micron’s capex escalation signals the entire three-player DRAM oligopoly is in an expansion phase simultaneously, a configuration that has historically front-run margin compression roughly two to three years out. Past episodes where Micron, Samsung, and SK Hynix all expanded simultaneously have tended to sow the next downturn roughly two to three years out, as new wafer capacity converts today’s tightness into oversupply.
For SanDisk, the NAND angle is distinct. Micron described a firmer pricing environment in NAND during fiscal Q4, which is consistent with a supportive backdrop into the next quarter. But a Micron capex ramp weighted toward DRAM cleanrooms, not NAND tools, may actually delay the NAND supply response, a relative positive for SanDisk’s near-term margin structure.
Scenario Framework
Bull Case: Management says it does not have line of sight to when supply and demand will return to balance, and fiscal 2027 revenue growth absorbs the capex without meaningful free cash flow deterioration. MU re-rates on the $38.15 Q1 EPS guide and the market refocuses on the $61.5 billion revenue trajectory. SK Hynix and SanDisk follow MU higher as the structural shortage thesis holds.
Base Case: Adjusted gross margin eases sequentially to about 86.25%, a modest pullback that still leaves profitability elevated. MU consolidates near current levels as investors monitor Q1 capex execution. Memory peers trade in a tight range until SK Hynix’s next quarterly update clarifies HBM demand durability.
Bear Case: Fiscal 2027 total capex exceeds $50 billion and free cash flow converts below 50% of operating income. A step-up in operating expenses and depreciation from new fabs compresses gross margins well before revenue peaks, triggering multiple compression in MU. Samsung’s parallel expansion amplifies sector-level supply concerns and drags SK Hynix and SanDisk with it.
Active Trader Framework
MU has been extremely extended in 2026, which means any miss on the capex-to-earnings delivery ratio carries outsized downside. On levels, the late-September regular-session close was about $1,065, and the late-September intraday low was roughly $1,064, which puts the near-term risk defined around that area. Use moving averages and VWAP as structure rather than as a thesis: if price acceptance fails below those references, risk control has to tighten quickly in a stock this stretched.
For the memory complex broadly, management said demand for memory and storage remains stronger than before, with supply conditions expected to stay tight in fiscal 2027 and 2028, which sustains the structural backdrop even as the stock digests heavier spending. Position sizing here must account for the capex calendar: heavy outflows in the first half of fiscal 2027 are already disclosed. That is the known risk. The unknown is whether Samsung or SK Hynix accelerate their own buildouts in response.
The reaction to last night’s results is a disciplined market distinguishing between demand strength, which is real, and capital efficiency, which is now under scrutiny. Those are different trades. Know which one you own.