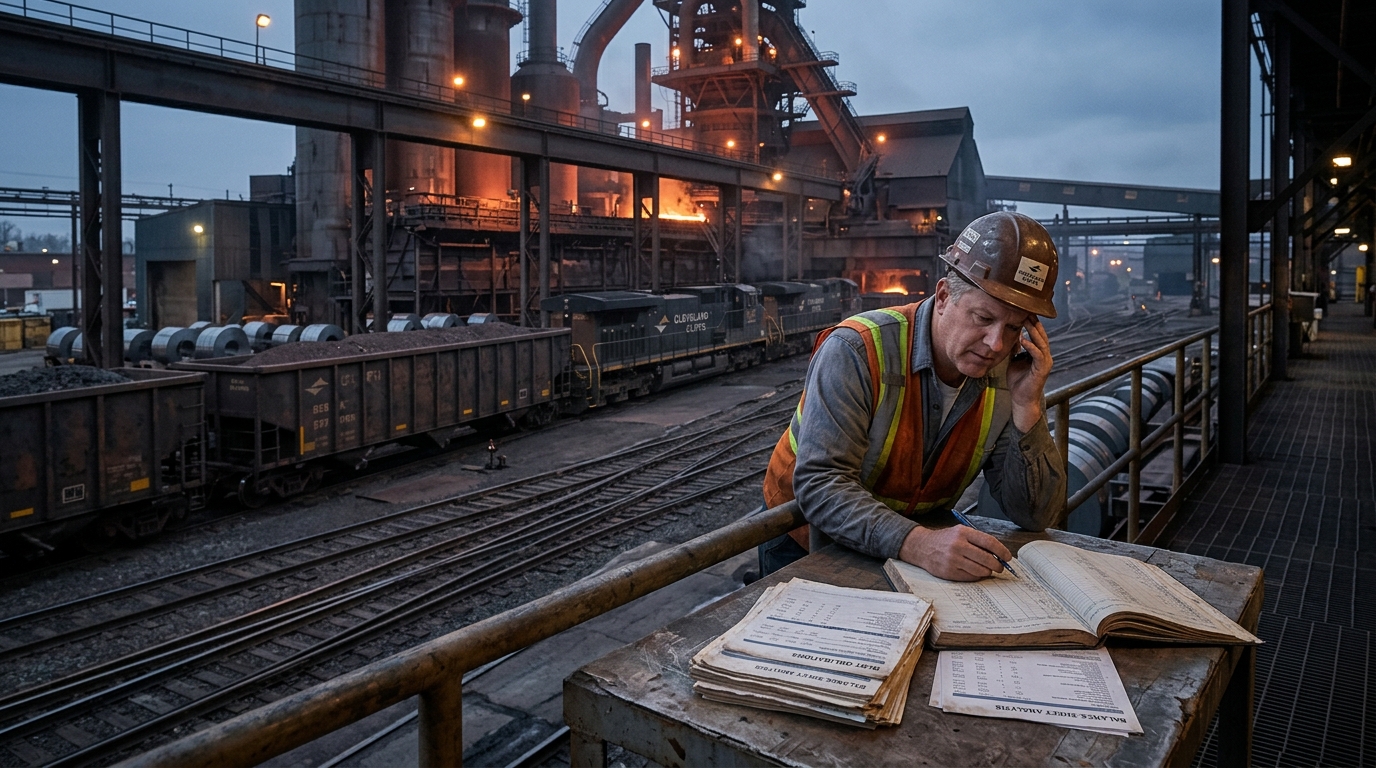
When Steel Dynamics and Cleveland-Cliffs open earnings week Monday, they will be reporting into one of the most protected domestic steel markets in a generation. U.S. finished-steel imports fell about 13.5% year over year to roughly 13.0 million net tons in the first nine months of 2026, cutting estimated finished-import market share year to date to 16% (from 19% a year earlier), according to the American Iron and Steel Institute’s read of Commerce Department SIMA data. Section 232 tariffs at 50% are doing the work, and the Iran war has added a second layer on top of them.
Dry bulk freight rates did jump sharply between February and July 2026, reaching a three-year peak amid geopolitics and higher fuel costs. Domestic prices are also far above Europe and China. That gap is wide enough that foreign steel struggles to compete here even before tariffs apply. The protection is real.
The two companies reporting Monday are not, however, equally positioned to benefit.
Steel Dynamics: Clean, Profitable, and Ready
Steel Dynamics guided Q3 EPS in the range of $5.34 to $5.38 per diluted share, up from $3.69 in Q2 2026 and $2.74 in the year-ago quarter. Consensus estimates vary by data source, but many sit modestly above the company’s own range. That puts consensus slightly above the company’s own guidance, which is a mild caution flag. The Q3 jump is driven by metal margin expansion across the platform, record shipments, higher average realized selling values, and lower scrap costs.
The fabrication backlog is nearly 50% above prior-year levels and extends through the first quarter of 2027, supported by demand from commercial construction, data centers, manufacturing, and healthcare. That is not cyclical noise; it is structural demand from the onshoring wave. Steel Dynamics also has no debt crisis, no foreign subsidiary entanglements, and a trailing P/E ratio around 22 based on recent quotes. For an EAF mill riding a tariff-protected pricing environment, the stock around the mid-$240s is the cleaner expression of the trade.
Cleveland-Cliffs: The Case That Requires More Faith
Analysts expect CLF to post Q3 EPS of $0.24, representing about a 153% increase year over year, on revenues around $5.6 billion to $5.7 billion. The return to profitability after a $0.20 loss in Q2 would matter far more if the balance sheet were not so strained.
Cleveland-Cliffs’ balance sheet still carries meaningful leverage. As of June 30, 2026, long-term debt was about $7.7 billion on the company’s reported balance sheet. With maturities beginning in 2027, the company needs this pricing environment to hold.
The Stelco situation adds political risk that Steel Dynamics simply does not carry. Cleveland-Cliffs subsidiary Stelco has said it will proceed with workforce reductions of up to 500 positions in Ontario, drawing scrutiny tied to the conditions Canada attached to its approval of the Stelco deal in 2024. Even after a bounce, CLF stock is down year to date, while the VanEck Steel ETF is up year to date. The market has been voting on this divergence all year.
The Protection Is Real. The Risk Is Political.
Here is the tension at the core of the CLF thesis. The moat keeping imports out is not a structural cost advantage; it is a policy choice that can be revised. Disruptions from the Iran war have pushed extra costs through logistics and sourcing. That war-inflated freight is a bonus layer of protection, but one that could dissipate with a ceasefire or a shipping route normalization. The tariffs themselves have already seen targeted modifications.
For investors who believe the tariff wall holds through 2027 and CLF executes against its roughly $575 million adjusted EBITDA target for Q3 while managing Stelco, the stock at a price-to-sales of 0.35 is deeply discounted relative to history. That is the bull case.
The Bottom Line
Monday’s results will tell us whether the tailwind is as strong as the pricing data suggests. Steel Dynamics is the higher-quality way to own this environment: clean leverage, record order book, no political complications, and a management team that issued guidance they are likely to hit or beat. Cleveland-Cliffs offers more upside if it survives its debt calendar and the Stelco fallout fades, but it also offers more ways to lose. The tariff moat and the war premium on freight are real today. Whether CLF can capitalize on them before its maturities arrive is a different question entirely.