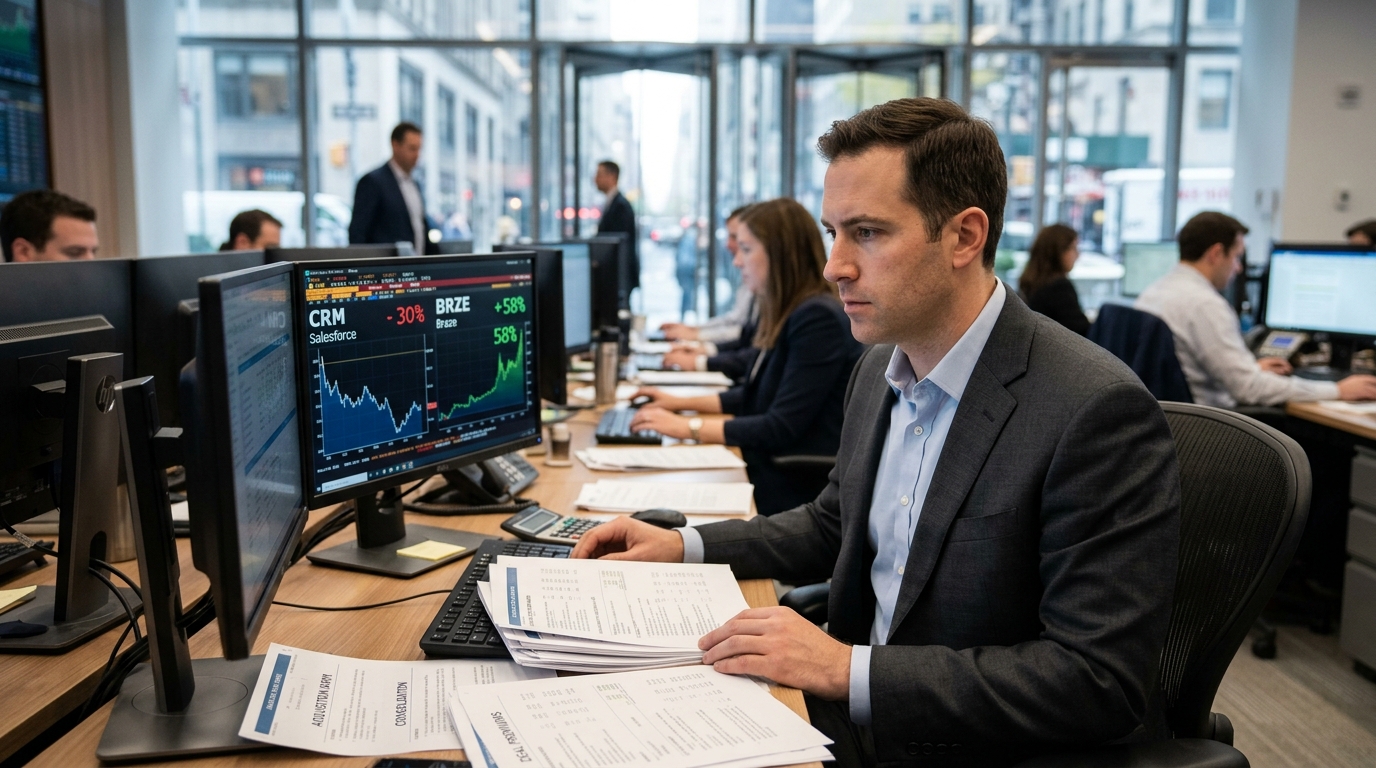
Salesforce announced this morning it will acquire Braze for $5.66 billion in cash, offering $47.50 per share, a 58% premium to Monday’s close of $30.04. Braze shares skyrocketed more than 50% on the news. CRM slipped roughly 1% to 3% depending on the session. That divergence is the first data point traders need to map.
This is not a standalone deal. It is the latest charge on a very active corporate card. Just this year Salesforce has signed deals for Fin and Listen Labs, let alone last year’s $8 billion blockbuster for Informatica. Add the $3.6 billion Fin acquisition and the $1.5 billion Contentful agreement, and Salesforce has committed north of $18 billion to M&A inside roughly 18 months, before counting Braze. Axios noted today that the Braze deal would rank as Salesforce’s fifth-largest acquisition ever.
The strategic logic is clear enough. Braze helps marketers respond to customer behavior in real time, coordinating personalized experiences across mobile apps, websites, email, SMS, and WhatsApp. Following the close, Braze’s customer engagement capabilities are expected to plug into Salesforce, including Data Cloud and Customer 360, with Salesforce also positioning it alongside Agentforce. Braze serves roughly 2,770 customers, including Canva, Instacart, Urban Outfitters, and Venmo.
The deeper question is whether Salesforce’s integration machine can absorb this pace. Salesforce dissolved its board M&A committee back in 2023, in part because of how hard it was to integrate MuleSoft, Tableau, and Slack. The Informatica acquisition closed on November 18, 2025 and is only now showing up meaningfully in revenue. Informatica contributed $444 million to Q1 FY2027 revenue, against an $8 billion purchase price. That payback math is long.
The underlying business, however, is accelerating. Revenue for the six months ended July 31, 2026 reached $22.5 billion, up 12% year-over-year. Agentforce annual recurring revenue more than tripled to $1.2 billion in Q1 FY2027. Total remaining performance obligation stood at approximately $66.3 billion as of July 31, a rise of 11% year-over-year, giving the company substantial contracted revenue runway even if near-term deal costs weigh on free cash flow.
Scenario Modeling
Bull Case: Braze’s 2,770-customer base converts to Agentforce upsells at meaningful attach rates, turning customer engagement data into a measurable revenue lever inside Salesforce’s broader AI stack. If Agentforce ARR continues tripling annually, Braze’s behavioral signals become a multiplier, not just an add-on. CRM re-rates toward $300.
Base Case: Integration timelines mirror the Informatica playbook, 12 to 18 months before meaningful cross-sell appears in reported metrics. Revenue growth holds in the 11% to 13% range through FY2027. The stock trades range-bound between $240 and $270 as the market waits for Agentforce monetization proof.
Bear Case: Regulatory scrutiny on the combined Contentful, Fin, and Braze acquisitions slows close timelines. The Braze deal is not expected to close until Salesforce’s fiscal year 2028. A prolonged M&A queue, combined with integration distraction, stalls operating margin expansion beyond the roughly 20% GAAP level implied by current FY2027 guidance. CRM tests $210 support.
Active Trader Framework
The BRZE arbitrage is straightforward: shares trade near the $47.50 cash offer, so spread traders watch for regulatory signals. The CRM positioning is more nuanced. Watch the $240 level as near-term support; a close below it on volume above the 20-day average would signal institutional distribution on acquisition fatigue. On the upside, Q3 FY2027 earnings, expected in early December, are the first clean read on whether Agentforce ARR can sustain its tripling trajectory. That report, not today’s deal announcement, is the real volatility event for CRM holders.
Preparation, not prediction, is the framework here. Salesforce is executing a deliberate consolidation of the enterprise software stack. The pace of that consolidation is also the central risk. Position sizing around binary regulatory and integration outcomes, not around the strategic story alone.