October 29, 2026
Bonus Content: Inflation Is Rising Again. The Fed Is Already Split.
The early AI winners were obvious in hindsight.
This one is in front of investors today.
The first AI wave rewarded hardware. The next may reward the companies that turn intelligence into business performance.
AI tech with validated commercial purpose. Multiple seven-figure contracts with Fortune 1000 brands. In 2026, RAD again achieved Preferred Partner status across Omnicom agencies. Sales contracts grew 10X from 2025 to 2026.
Current allocations remain limited.
RAD Intel’s Regulation CF round is now open to all investors.
P.S. Limited allocations remain in the current investment round. The offering page lays out the details, risks included. Learn more to invest →
Regulation CF · now open to investors
This is a paid advertisement for RAD Intel made pursuant to Regulation CF offering and involves risk, including the possible loss of principal. Past performance is not a guarantee of future results. Brand references reflect factual platform use, not endorsement. Investor references reflect factual individual or institutional participation and do not imply endorsement or sponsorship by the referenced companies. Please read the offering statement and related risks at invest.RADIntel.ai.
Inflation Is Rising Again. The Fed Is Already Split.
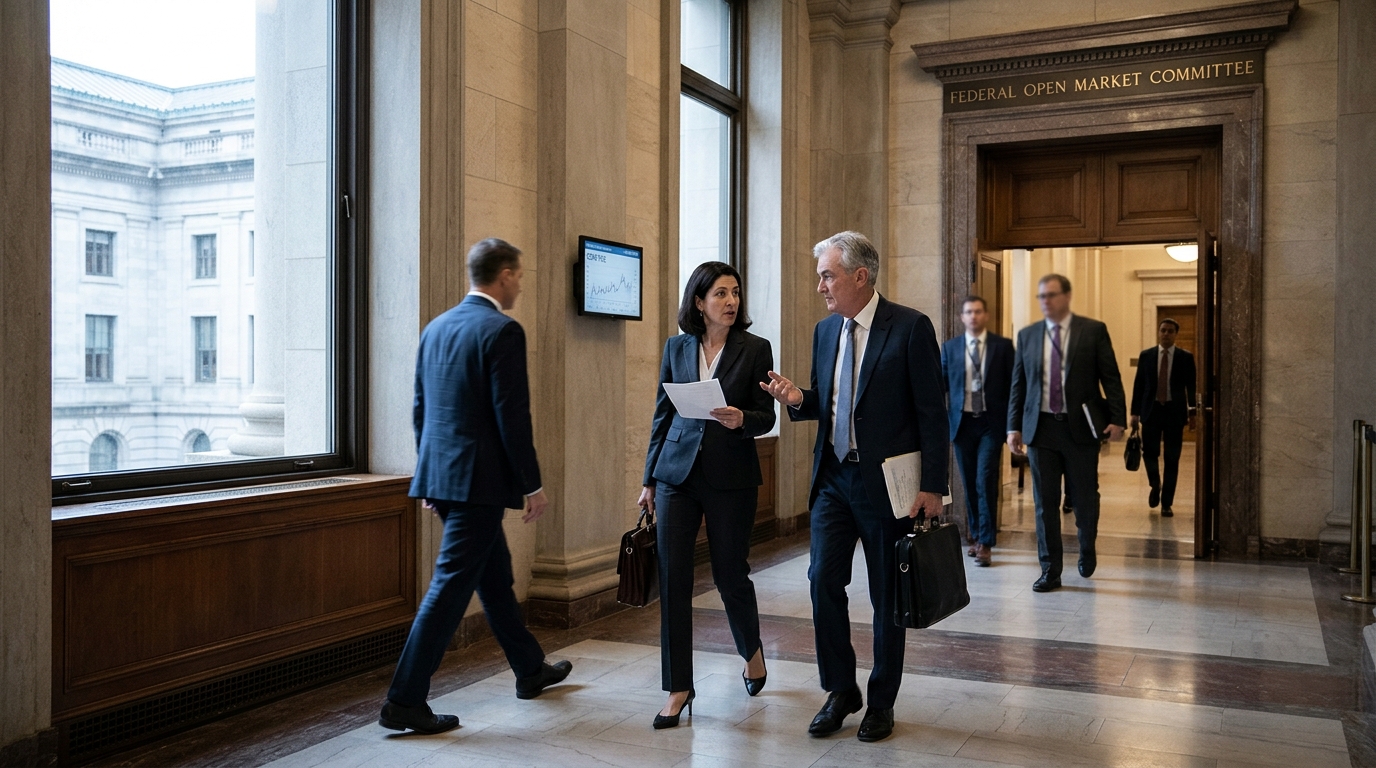
- FOMC voted 10-2 to hold at 3.75%–4.00% on October 28; Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented, each preferring an immediate 25bp hike.
- Core PCE expected at 0.3% m/m and 3.1% y/y for September, a four-month high; headline PCE forecast near 3.7% y/y on energy pass-through.
- Advance Q3 GDP expected between 2.8% and 3.5% annualized, against Q2’s confirmed 2.2%, with GDPNow at 3.3% as of October 28.
- The 2-year Treasury yield ended October 28 near 4.67%, roughly 3bp lower than the prior session, after initially moving higher in the immediate aftermath of the decision.
- Fed funds futures still lean toward a December hike; a hot 8:30 double read could push that further.
- Cook’s dissent was her first since joining the Board in 2022, adding political complexity ahead of next week’s midterm elections on November 3.
- Chair Warsh offered no forward guidance and confirmed the next meeting on December 8-9 will include new economic projections.
Market Context
Thursday’s 8:30 release is the most consequential data moment of the month. The BEA publishes both the September personal income and outlays report and the advance Q3 GDP estimate simultaneously, a combined release falling one day after the FOMC October 28 rate decision, making October 29 one of the most data-dense days of the year. The sequencing matters. The FOMC published its decision at 2:00 p.m. Eastern on October 28 without new economic projections, while PCE and GDP followed roughly 18.5 hours later. The committee therefore reached its decision before either number existed publicly.
The FOMC voted 10-2 to maintain the federal funds target range at 3.75%–4.00%. Chair Kevin Warsh reiterated that 2% is a hard target, framed the hold as an observational pause to evaluate the transmission of September’s rate hike, and declined to provide forward guidance for December. That lack of guidance puts maximum weight on today’s data. After the decision, fed funds futures continued to imply a high likelihood of another hike at the December meeting. A core PCE reading at or above 0.3% m/m this morning would hand the hawks their strongest near-term argument.
The Dissent and What It Signals
Cleveland Fed President Beth Hammack and Fed Governor Lisa Cook each voted in favor of hiking interest rates by 25 basis points. Cook and Hammack dissented because they judged a quarter-point hike to be the appropriate response to inflation remaining above the 2% goal. For Cook, it was the first dissent since she joined the Board of Governors in 2022. A governor dissent is structurally rare. As FWDBONDS chief economist Chris Rupkey noted, “it’s very rare to see a Fed governor dissent, they are sitting right there in the same building as the Chairman.”
Compared to the September statement, the description of economic activity was upgraded from “solid” to “strong.” The sentence about supporting a timely return to 2% was replaced with language about accumulating more information to determine appropriate policy stance. That shift is the committee’s clearest admission it is data-dependent with no predetermined path.
The 8:30 Double Read: What Traders Are Watching
Forecasters expect a 0.3% rise in personal income and a 0.6% rise in spending, with overall PCE prices up 0.5% and core PCE prices up a four-month high of 0.3%. Year-over-year, the core PCE price index is forecast at 3.1%, up from 3.0% in August. On growth, two Federal Reserve bank models put third-quarter expansion between 2.7% and 3.3%, above the pace BEA reported for the spring. Either reading would mean the economy picked up speed over the summer.
The asset to watch most directly is the 2-year Treasury. The 2-year yield is the market’s cleanest read on where the Federal Reserve is heading, and it arrived at this morning’s data sitting near 4.67%. A confirmed 3.1% core PCE y/y alongside a GDP handle above 3.0% would likely push the 2-year back toward its recent 4.80%+ range and carry the dollar with it.
Scenario Modeling
Bull Case for Risk Assets
Core PCE prints at 0.2% m/m, below the 0.3% consensus, while Q3 GDP comes in at the lower end of forecasts near 2.7%–2.8%. The 2-year yield drops toward 4.55%, the dollar pulls back, and December hike odds retreat materially. Equities rerate higher and rate-sensitive sectors lead. This scenario requires both prints to underperform consensus simultaneously.
Base Case
Core PCE lands at 0.3% m/m and 3.1% y/y, in line with expectations. GDP prints 3.0%–3.3% annualized. The 2-year tests resistance near 4.80%. December hike odds hold or edge slightly higher. Nearly 60% of forecasters already see this cycle topping at 4.00%–4.25%, with Mizuho’s Alex Pelle telling Reuters, “They’ll go 25 in December, but the risk is greater they end up going 50 than they don’t go at all.” The median sees no return to the 2% target before 2028.
Bear Case for Risk Assets
Core PCE surprises at 0.4% m/m, driving the y/y rate toward 3.2%, while Q3 GDP exceeds 3.3%. The 2-year pierces 4.85%, the dollar reclaims 102.50+, and December hike odds jump further. The Fed’s stated data-dependence would make a 50bp December hike a credible market conversation, particularly given the Cook-Hammack dissent already on the record.
Active Trader Framework
The decision framework centers on three levels in the 2-year yield: 4.55% on the downside, 4.67% as the current anchor, and 4.85% as the trigger for a broader reset in rate expectations. Watch the spread between the initial headline move and the sustained direction after the first 15 minutes. Knee-jerk reactions to simultaneous GDP and PCE releases historically overshoot; the 30-minute close matters more than the opening spike.
The current setup echoes an earlier inflection point in this hiking cycle. Sticky PCE alongside a stalling consumer forced traders to map the same three yield levels ahead of a Warsh policy decision.
On the dollar, 101.80 is the immediate support established after yesterday’s FOMC reaction. A hold above that level into the 8:30 release is constructive for dollar bulls if the data confirms the hawkish read. Vol is elevated. Position sizing should reflect that both numbers land at the same instant, giving no ability to layer in on confirmation.
Conclusion
Today is not a single data point. It is a collision: a four-month high in the Fed’s preferred inflation gauge, the first read on third-quarter growth, and the political weight of the closing stretch into the midterm elections on November 3, all arriving the morning after the committee’s most divided vote since the hiking cycle restarted in September. Warsh has made data the arbiter. The data is now here. Preparation beats reaction every time, and that discipline matters most on mornings when the market has nowhere to hide from the numbers.