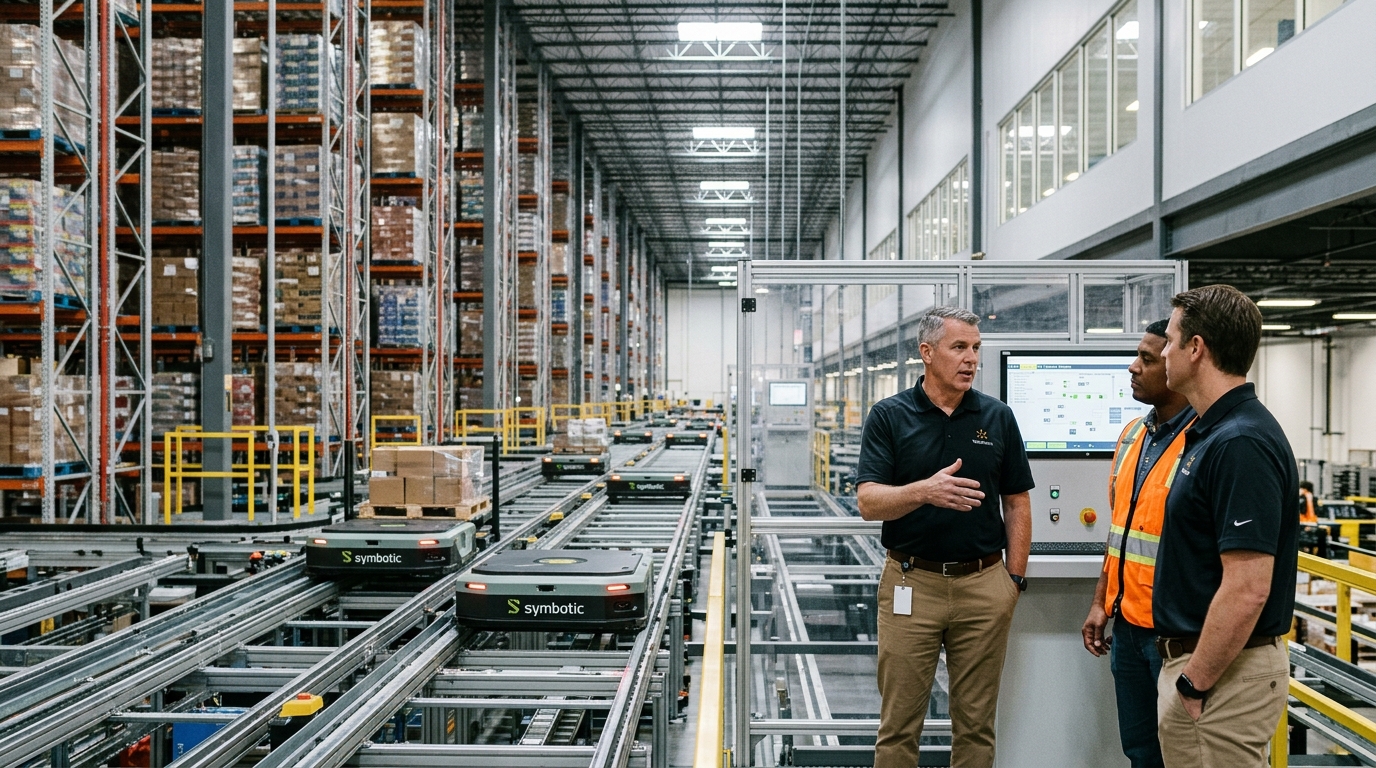
Symbotic is already Walmart’s automation engine. The question traders are not asking loudly enough is whether that relationship has quietly crossed the threshold where a full acquisition becomes the rational move.
The ownership math is striking. Walmart holds 76.35 million Symbotic shares on an as-converted basis, equal to 39.9% of Class A stock, according to a Schedule 13D amendment filed August 7, 2026. Voting power is only 5.4%, because founder Rick Cohen’s multi-class structure controls the room. That gap between economic exposure and governance control is exactly the kind of structural tension that precedes a buyout offer.
Symbotic’s operating momentum only sharpens the case. Fiscal Q3 2026 revenue came in at $721 million, up 22% year over year, with adjusted EBITDA more than doubling to $95 million. Q4 guidance targets $760 million to $780 million in revenue and $100 million to $105 million in adjusted EBITDA. The company carries a $22.5 billion backlog, the vast majority tied to Walmart and GreenBox agreements, with 15% of that expected to convert in the next 12 months.
Now consider where SYM trades: around $39 per share as of October 27, down more than 55% from its 52-week high of $87.88. Analyst consensus targets average $60.75, implying roughly 56% upside from current levels. The stock’s implied volatility has remained elevated, reinforcing that the market is treating this as a higher-variance outcome vehicle, not a stable mid-cap compounder.
On the Walmart side, the infrastructure logic is compounding. Walmart’s fiscal 2026 capital expenditure reached $26.64 billion, with analysts projecting roughly $29 billion this year. The company opened its fifth next-generation fulfillment center in Stockton, California on October 8, using the facility for both direct and Walmart Fulfillment Services marketplace orders. A sixth center in Carnesville, Georgia is planned at $1.3 billion and 1.5 million square feet. Walmart U.S. CEO David Guggina has explicitly tied automated fulfillment to a goal of reaching 75% of the U.S. population with next-day or two-day delivery.
Symbotic is simultaneously expanding its own technology base. On October 13, it completed the acquisition of cellumation, a Bremen-based maker of software-driven sortation systems, marking its third acquisition of 2026. A broader platform is a more defensible asset, and a more expensive one to replicate.
Specialized hardware with no easy substitute commands a different kind of moat. Component suppliers whose parts cannot be swapped out mid-build hold structural pricing power across the automation and infrastructure stack.
The structural risk for Walmart is competitive, not operational. Automation delays at approximately 200 warehouses have surfaced. Rivals including Knapp, Dematic, and others are actively pitching alternative architectures. If Symbotic’s execution slips, Walmart loses the switching cost argument for keeping this relationship exclusive. Owning the company outright removes that exposure entirely and locks proprietary AI-enabled robotics software away from Amazon, which is accelerating its own fulfillment automation in parallel.
Scenario Modeling
Bull Case: Walmart makes a formal tender at a 40–50% premium to current prices, roughly $54–$58 per share, consistent with analyst target ranges. SYM squeezes to acquisition price. Trigger: Q4 earnings on November 23 show clean execution, removing the deployment-delay overhang.
Base Case: No acquisition announced near term. Walmart deepens the commercial relationship while SYM grinds toward $50–$55 on fundamental momentum. The ownership stake remains strategic leverage rather than a precursor to a bid.
Bear Case: Warehouse deployment delays worsen into fiscal 2027, Walmart accelerates diversification toward Knapp or Dematic, and the concentration risk premium widens further. SYM tests its 52-week low near $36.47.
Active Trader Framework
SYM is trading below its 200-day moving average, making outright long equity positions high-variance into the November 23 earnings window. Traders focused on the M&A angle should treat $36.50 as the structural support level where the risk-reward for a long position improves materially. The $55–$60 zone represents the first meaningful resistance band and aligns with analyst consensus. Position sizing should reflect the binary nature of deployment execution as the near-term catalyst. Preparation, not anticipation, is the discipline this situation demands.