Last week closed with a jolt. Stocks rallied Friday as yields initially retreated following a surprisingly weak September jobs report that suggested the Federal Reserve may stay on hold at this month’s policy meeting. That single number reset the board. Prior to the report, traders assigned a high probability to a rate hike at the October 27-28 FOMC meeting; within hours of the data release, those odds fell sharply, based on CME Group’s FedWatch tool. Now, heading into the October 5-9 week, three distinct events will either confirm or unwind that shift in expectations.
Monday: Services PMI Opens the Week
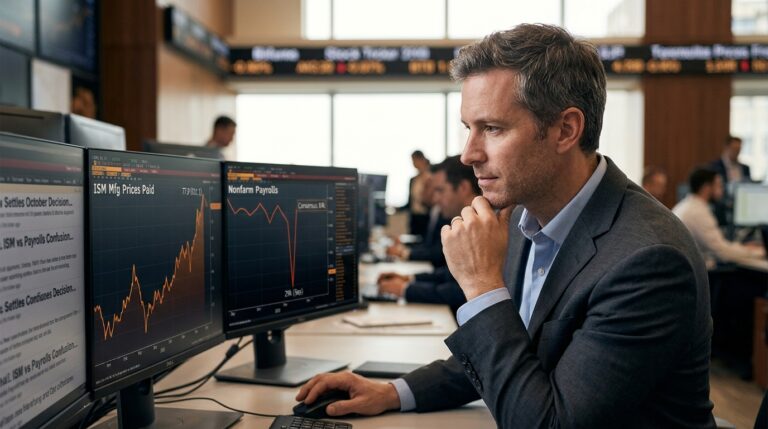
On Monday, the Institute for Supply Management will release the September ISM Services PMI. The market will focus on headline PMI, new orders, employment, and prices paid indices. The prior reading was 55.4, with consensus sitting at 55.7. That prices-paid sub-index is the critical number. Recent inflation data show inflation running cooler than earlier feared: the Commerce Department’s late-September PCE release showed headline PCE inflation at 3.4% year over year in August and core PCE at 3.0%. So any acceleration in services-sector price pressure could swiftly reassemble October hike odds. The primary risk into Monday is a reversal in higher-beta leadership if the 10-year yield persists higher, with SPY ETF support at $766.97 and QQQ ETF support at $746.57 as the key failure levels to monitor.
Wednesday: The Fed’s Own Words
The main event of the week is the release of the minutes from the Federal Reserve’s September meeting on Wednesday. At that September 16, 2026 meeting, the FOMC voted unanimously to increase the federal funds rate target range by 25 basis points to 3.75%-4.00%. The September Summary of Economic Projections signaled that most participants expected policy to end 2026 modestly higher than the post-meeting range, with a median year-end 2026 projection around 4.1% and a large majority penciling in at least one additional hike this year. The minutes will reveal how much internal debate surrounded that dot plot. Vice Chair Philip Jefferson and New York Fed President John Williams have emphasized the need to stay data-dependent, and traders will parse every line for whether that caution has deepened or faded since the September 16 decision. The 10-year Treasury yield had climbed to about 5.34% earlier in the week, and was around 5.205% on Friday morning following the jobs data. Whether that relief holds depends heavily on Wednesday’s tone.
Thursday and Friday: Earnings Season Opens
Q3 earnings season starts Thursday, October 8 with PepsiCo, followed by Delta Air Lines on October 9 and the big banks on October 13 and 14. PepsiCo is the week’s most instructive read on consumer health. Analysts forecast earnings of roughly $2.30 per share and revenue of approximately $25 billion, versus management’s full-year EPS guidance of $8.55-$8.71. PepsiCo is facing softer snack momentum and cost pressure, and investors will focus on volume and mix as a clean signal of whether consumers are trading down. Delta follows Friday and lands as the first real fuel-cost data point, at a moment when crude is hovering around the $100-a-barrel zone and volatility in energy is feeding directly into rates and cyclical risk appetite.
The Framework That Matters
FactSet’s published Earnings Insight for Q3 2026 points to a much lower growth profile than the draft headline suggests, with analysts projecting earnings growth in the mid-teens and revenue growth in the mid-single digits. That headline is still generous in context, but the concentration risk inside it is real. The market-cap-weighted S&P 500 looks firm and the SOX and NDX look bullish, while the equal-weight index, the Dow, and the Russell 2000 remain in bearish intermediate-term downtrends. Oil prices and the trajectory of Treasury yields will likely be the primary driver of price action until Q3 earnings season fully arrives October 13. Preparation over prediction: the ISM prices-paid number Monday, the Fed’s internal debate Wednesday, and PepsiCo’s North American volume Thursday are the three data points worth owning a view on before the open each day.