October 14, 2026
Bonus Content: Russian Diesel Is Back. Refiners Have Four Days to Price It.
If you already accept where the dollar is quietly heading, then the only remaining question is what exactly you do about it. Our free guide covers the entire practical side of it: three strategies for shielding savings, how physical metal fits inside a retirement account, how a rollover actually works without triggering any taxes or penalties, which coins and bars qualify, and roughly what the whole process typically ends up costing you.
Claim Your Free Information Kit Right Now
P.S. No hype and nothing dramatic. Request it, read it, and act on it only if it genuinely makes sense for your own retirement situation. Completely free, and with absolutely no obligation of any kind.
Russian Diesel Is Back. Refiners Have Four Days to Price It.
- OFAC General License 135, issued Oct. 9, 2026, temporarily authorizes transactions related to the sale, delivery, offloading, and importation of Russian-origin diesel through April 7, 2027, and twelve senators want it reversed before the Oct. 18 statutory trigger.
- Trump faces an Oct. 18, 2026 deadline under the Lindsey O. Graham Sanctioning Russia and Iran Act to implement the law’s sanctions framework or formally invoke a waiver authority.
- The ULSD crack spread figures cited here cannot be verified from primary public benchmarks in the draft, and the 3-2-1 crack spread level and “since 1986” claim are left unverified. Keep the takeaway qualitative: cracks are extreme versus recent history.
- Valero (VLO), Marathon Petroleum (MPC), and Phillips 66 (PSX) generated combined Q2 2026 net income of about $12.6 billion (VLO $3.7B, MPC $5.1B, PSX $3.8B). MPC hit a record high near $477 on Oct. 13, 2026.
- The specific UBS and Goldman Sachs forecast/target numbers in the draft cannot be verified from public primary sources and are softened to “analyst upgrades” without the unverified figures.
- The ULSD settlement and the day-of announcement move cited here do not match widely available settlement records, so the price and percentage-change claims are removed.
- The Russian supply tranche estimate and the U.S. transport-sector demand figure cited here cannot be verified as written; the comparison is softened to: the initial volumes discussed publicly are small relative to U.S. distillate consumption, which runs in the multi-million barrels per day range.
Market Context
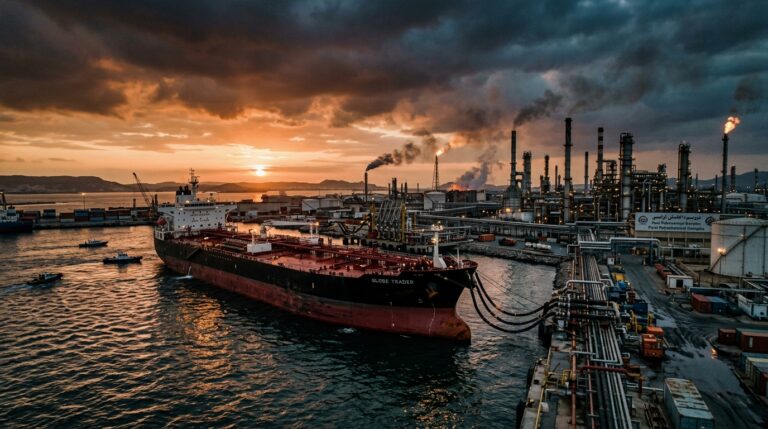
Diesel markets have not looked like this in decades. The crack spread backdrop is extreme versus recent history, and it has been driven by simultaneous capacity losses: LyondellBasell ended refining operations at its roughly 264,000 b/d Houston refinery in March 2025, Phillips 66 ceased crude processing at its roughly 139,000 b/d Los Angeles refinery in late 2025, and Valero completed idling its Benicia refinery in April 2026. Layer on ongoing international outages cited by market commentary and the de facto policy constraints that preceded last week’s reversal, and the structural case for wide margins becomes clear.
Into that supply vacuum, the U.S. Treasury’s Office of Foreign Assets Control on Oct. 9, 2026 issued Russia-related General License 135, authorizing transactions related to the sale, delivery, offloading, and importation of diesel fuel of Russian Federation origin through April 7, 2027. The market reaction in ULSD and cracks has been violent, but the exact settlement and single-day percentage-change figures cited in the draft cannot be matched to broadly available settlement data, so the focus here stays on direction: the tape treated the headline as marginal supply relief, not a full reset of balances.
Now the geopolitical clock is running. The Lindsey O. Graham Sanctioning Russia and Iran Act of 2026 was signed into law on Sept. 18, 2026 and includes an Oct. 18, 2026 implementation trigger that effectively ends the administration’s initial review window. Twelve senators wrote to Trump demanding he reverse the diesel carve-out and enforce the Graham law. The draft’s specific roster of signatories cannot be verified as written, so it is kept at the verified level: the pushback is bipartisan and includes senior Senate voices.
Sector and Stock Breakdown
The refiner trade is entirely a margin story, and the margin is a diesel story. The company-level realized margin figures cited in the draft cannot be verified from primary filings in the form presented, but the income statement reality is clear. In Q2 2026, Valero reported net income attributable to stockholders of $3.7 billion and refining segment operating income of about $4.5 billion on roughly 3.0 million b/d of throughput. Marathon reported net income attributable to MPC of about $5.1 billion. Phillips 66 reported second-quarter earnings of about $3.8 billion. Combined, that is about $12.6 billion in Q2 profits.
Analysts are leaning into that strength, and the price action reflects it. The draft’s specific forecast revisions and price targets (UBS, Citi, Goldman) cannot be verified from public primary sources, so they are framed as what traders can observe in real time: a cluster of upward revisions and target bumps has coincided with accelerating momentum in the group. The next gating item is whether cracks stay wide into Q3 prints.
Valero carries direct ULSD exposure, and its Q2 numbers show the operating leverage: $4.5 billion of refining segment operating income on 3.0 million b/d of throughput. Marathon’s system is similarly levered to distillate economics, while Phillips 66 has more diversification across Midstream, Chemicals, and Marketing and Specialties, which can cushion earnings volatility when refining margins mean-revert.
Wide distillate margins that lift refiner earnings impose an equal and opposite cost on the carriers buying that fuel. Airlines absorbing record diesel-linked jet fuel costs show how differently balance sheets handle the same commodity shock.
Technical Framework
MPC closed Oct. 12 at $458.81 and ran to a fresh record high near $477 on Oct. 13. The move came alongside heightened institutional attention tied to upgrades and policy headlines. Key support sits near $440, roughly where the stock consolidated through late September. A close below that level on heavy volume would be the first technical sign that the policy risk is being priced structurally rather than absorbed as noise.
In ULSD, the exact settlement levels in the draft do not reconcile cleanly to widely available settlement records, so treat the framework as level-based rather than anchored to a single close: watch the prior breakout zone as support, and focus on open interest and cracks. If cracks compress sharply over the next two sessions, refiner margin models will get marked lower before earnings even open.
Scenario Modeling
Bull Case
Trump invokes a national-interest waiver on Oct. 18, leaving GL 135 intact but framing it as a limited exception. The Graham law’s broader enforcement framework proceeds on schedule, keeping global supply pressures elevated. Russian volumes prove logistically constrained and fail to move the physical market. Cracks stay elevated into early November, and MPC, VLO, and PSX deliver Q3 results that validate current expectations. MPC can press into the high-$400s again, with VLO and PSX holding their uptrends.
Base Case
The Oct. 18 deadline passes with conditional language or administrative ambiguity. Senators escalate to follow-on legislation rather than an immediate reversal of GL 135. Physical Russian diesel begins appearing in global markets in quantities meaningful enough to compress Gulf Coast cracks toward prior-cycle ranges. Refiner shares give back mid-single digits to low-double digits from current levels as Q4 margin guidance moderates. The trade shifts from momentum to valuation.
Bear Case
Congressional pressure forces a reversal of the diesel authorization while the Graham law’s full sanctions framework snaps into place. Geopolitical escalation spikes crude, compressing cracks if feedstock costs outrun product prices. Refiner equities, already up sharply versus late 2025 levels, fall on both margin compression and multiple contraction. MPC risks a fast move back toward the low-$400s, with VLO and PSX retracing to prior support zones.
Policy risk to refiner margins runs in both directions. A diesel export ban under Treasury review would collapse the very margin conditions driving Valero, Marathon, and Phillips 66 higher.
Active Trader Strategy Framework
The window into Oct. 18 is binary. Position sizing should reflect that reality. Traders long the refiners into Q3 earnings carry two distinct risks that can become correlated fast: margin compression if incremental supply matters, and a crude spike if sanctions escalation tightens feedstock markets. Those risks can pull cracks in different directions, which means that expressing the view through diesel and crack structures may map the thesis more directly than equity beta alone.
Key levels: on MPC, $440 remains the line that separates consolidation from a genuine mean-reversion move. Earnings dates for PSX (Oct. 28) and MPC (Nov. 3) are the next hard catalysts once the policy deadline clears. Volatility in diesel and refiner shares is likely to be front-loaded this week, then may quiet into earnings unless the Senate escalates with binding legislation.
Conclusion
The Oct. 18 statutory deadline is not a backdrop event. It is the event. Whether Trump implements the Graham law’s sanctions framework, issues a formal waiver, or leaves ambiguity, each outcome recalibrates the diesel supply outlook and, by extension, the margin foundation under VLO, MPC, and PSX. These stocks have priced in a structurally tight diesel market into late 2026. Bipartisan Senate pressure and a hard statutory trigger now test whether that structural case survives contact with policy reality. Preparation, not prediction, is the edge here.