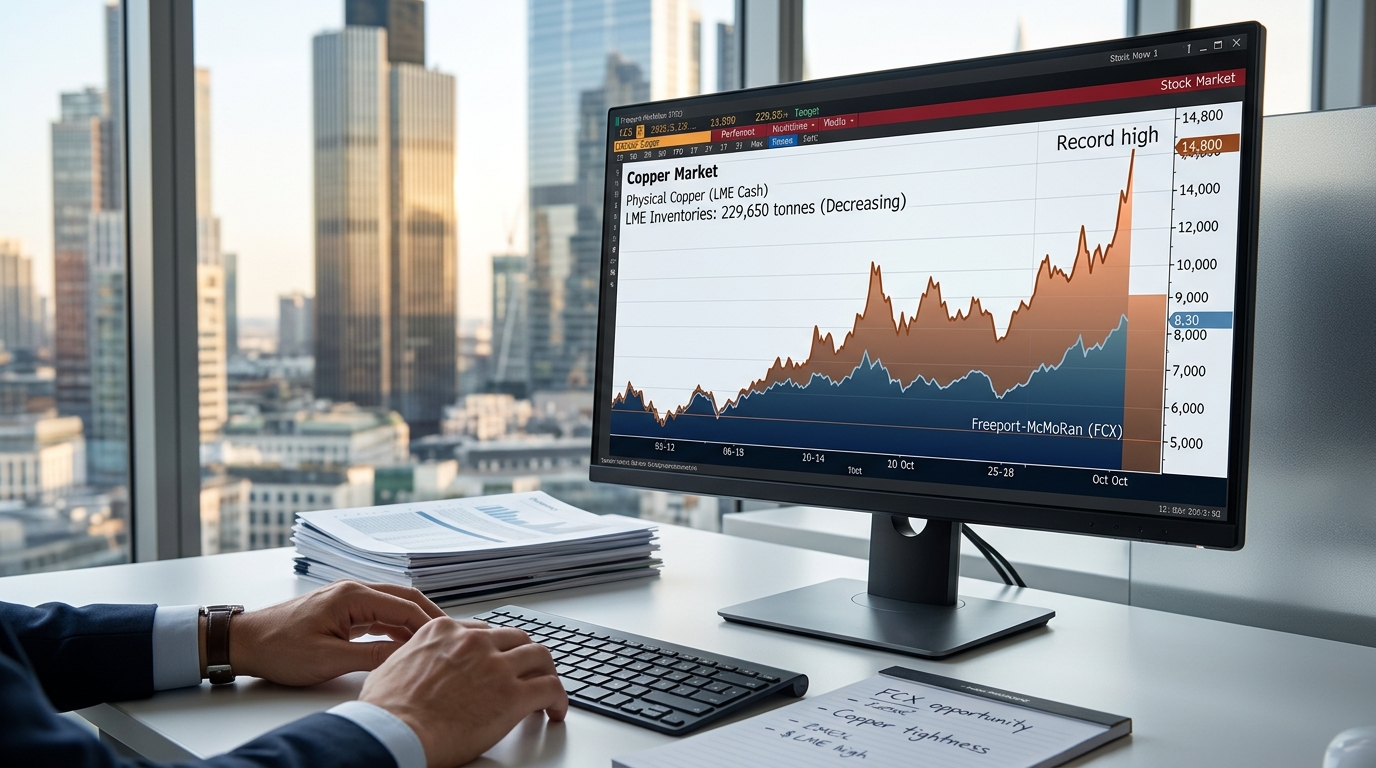
Cash copper settled at a record $14,822 a tonne on Monday. By Tuesday it was $14,741. On Wednesday, three-month LME copper climbed as far as $14,700 before easing to $14,532, while LME inventories fell for a seventh straight session to 229,650 tonnes. The physical market is screaming tightness. The equity market, for Freeport-McMoRan at least, has not fully listened.
FCX closed at $69.62 on October 14, down 3.9% on the day, against a 52-week range of $38.54 to $80.24. The stock still sits roughly 13% below its 52-week high even as the commodity it mines set an all-time record this week. That gap is the thesis.
The Business
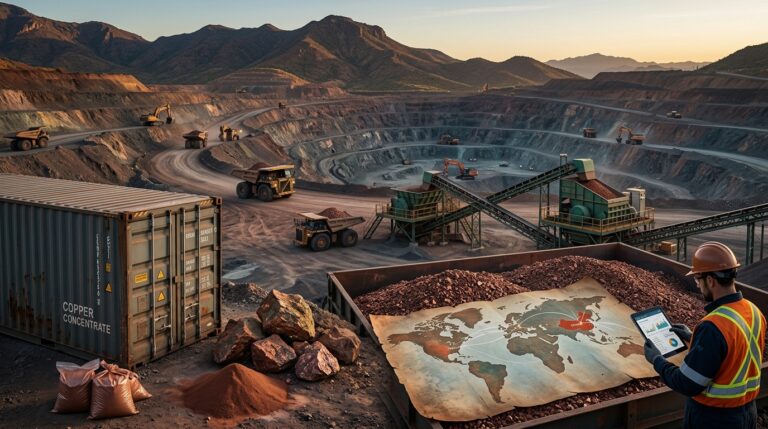
Freeport is the world’s largest publicly traded copper company. Its Grasberg complex in Indonesia is one of the planet’s premier copper-gold deposits, and its U.S. operations in Arizona and New Mexico provide geographic diversification that most pure-play rivals cannot match. With a market capitalization above $100 billion, FCX plays a central role in supplying copper essential for electrification and AI-driven power demand. That demand is not softening: the International Copper Study Group has forecast refined copper usage rising about 2.1% in 2026 and has projected a deficit in its 2026 outlook.
Why Wall Street Is Paying Attention
The analyst community moved fast in early October. On October 6, JPMorgan maintained its Overweight rating on FCX and raised its price target from $77 to $92, a 19% jump. It was not alone. UBS lifted its target from $77 to $88 and maintained a Buy. Wells Fargo moved its target from $70 to $87. Those revisions followed FCX’s Q3 operational update, which confirmed consolidated copper production of approximately 830 million pounds, in line with expectations. The company expects its Q3 average realized copper price to exceed $6.50 per pound.
FCX’s trailing EPS stands at $2.03. Q2 was the third consecutive beat: the company reported $0.74 per share against $0.62 expected and $7.03 billion in revenue. Full Q3 results are expected October 27.
What’s Driving the Opportunity
Copper’s 2026 advance has forecasters raising their numbers for the second time in three months. Macquarie now has the metal averaging $13,573 this year, BMO Capital Markets $13,619, and BMI, a unit of Fitch Solutions, $13,500. Deutsche Bank believes copper could make another attempt at the record high in the near term, while Citi sees $15,000 within twelve months.
The supply side is not cooperating with bearish scenarios. A mudslide following heavy rainfall at Chile’s major El Teniente mine is fuelling supply disruption concerns, and Chinese importers have been paying a premium of roughly $118 over the LME price, the highest since 2022. Meanwhile, FCX is up 46.1% year-to-date and about 68% over the trailing twelve months, yet the stock pulled back sharply this week even as cash copper made history. That dislocation rarely persists.
What Could Go Wrong
The risk is not subtle. A Reuters analysis this week described how tariff uncertainty has helped build a large U.S. copper stockpile and argued that the policy path will be a key swing factor from here. If that stockpile eventually unwinds back into global markets, it would pressure the LME spread that has driven the record cash prices.
Total global stockpiles are relatively high but heavily concentrated in the U.S., as metal in the LME’s global network has dwindled. That has sapped short-term availability and put pressure on short positions, helping send prices to records even in a tepid demand environment. A tariff resolution that redirects that metal outward could compress the backwardation quickly. FCX, with its beta of 1.39, would feel the move in both directions.
The Bottom Line
FCX is the most direct, liquid way to hold copper exposure at a moment when the metal is setting records and institutional analysts are racing to raise targets. The stock’s drop this week while cash copper hit $14,822 is not a reason to walk away. It is the entry. With Q3 earnings expected October 27 and consensus EPS around $0.75, investors have a clear near-term catalyst to focus the thesis. The tariff unwind risk is real and deserves position sizing discipline. But the combination of record commodity prices, consecutive earnings beats, and a stock trading 13% off its high makes FCX today’s single strongest idea.