The credential-based breach has been enterprise security’s most predictable cost for a decade. Microsoft just moved to close it permanently, and the commercial architecture behind that shift is worth understanding before the company reports Q1 FY2027 on October 28.
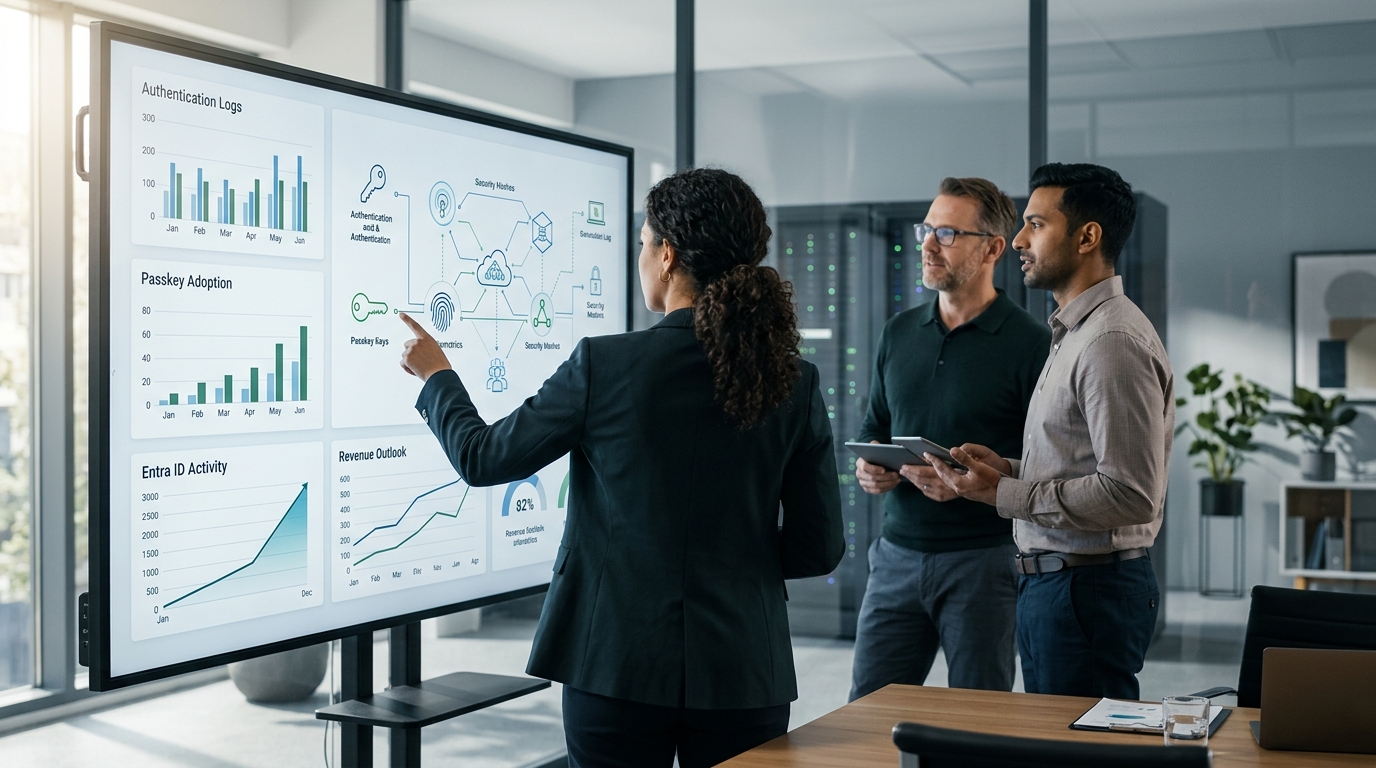
On September 1, passkeys became the default authentication experience that Microsoft began rolling out across Microsoft Entra ID for tenants with users enabled for SMS or voice authentication. The transition is not a pilot. Microsoft-provided SMS and voice-based MFA retire for most users on February 1, 2027, but Global Administrators and external users move to a July 1, 2027 retirement date. Every enterprise tenant running Microsoft 365 is now on a migration clock, pushing users toward hardware-isolated biometric credentials anchored in TPM 2.0 silicon rather than a shared secret that can be intercepted or replayed.
What the Architecture Actually Does
Windows Hello for Business sits at the center of the stack. It delivers TPM 2.0-backed biometric or PIN authentication on managed workstations, with Entra ID brokering federated access across SAML and OIDC applications. The credential lives in the device’s secure enclave. There is nothing on a server to steal. Microsoft’s own threat intelligence reported AI-enabled phishing campaigns reaching click-through rates of 54%, against roughly 12% for traditional campaigns, which is the risk vector the hardware binding directly neutralizes.
The September update also added Resource Accounts that replace legacy password-based authentication with hardware-protected, device-bound credentials across shared workstation environments, a segment that had resisted passwordless migration for years. Entra Cloud Sync, which reached general availability in September, now provisions identities bidirectionally between Entra ID and on-premises Active Directory, which closes the hybrid-deployment gap that stalled enterprise rollouts.
The Security Revenue Line
The identity shift is not background engineering. It sits directly inside a security business that hit $20 billion in annual run-rate revenue, more than doubling since 2021. Microsoft Entra now reaches one billion monthly active users. The IAM market itself stood at $25.2 billion in 2026, projected to reach $45.2 billion by 2030 at a 15.7% compound annual rate. Entra holds the largest mindshare position at 16.4% in independent October 2026 tracking data, ahead of Okta at 8.6%.
Azure crossed $100 billion in FY2026 revenue for the first time, up 41% year-over-year. The Intelligent Cloud segment posted $39.3 billion in Q4, up 32%. Analysts expect Q1 FY2027 revenue of $90.6 billion, with Azure guidance pointing toward 45% constant-currency growth. TD Cowen raised its price target to $625; UBS to $675.
The Structural Risk Multi-Cloud Traders Are Underweighting
Zero trust functions cleanly inside a homogeneous Microsoft estate. The integration gaps emerge in heterogeneous environments where Salesforce, AWS workloads, and legacy on-premises systems sit alongside Azure. Extending device compliance signals and risk-based access controls to third-party platforms remains the unresolved friction. Enterprises running AWS or Google Cloud alongside Azure carry real integration overhead that neither Entra licensing nor passkey adoption eliminates.
That multi-cloud integration overhead is not just an architectural inconvenience — it is becoming a regulatory exposure. European regulators are now requiring enterprises to demonstrate they can exit a cloud provider without causing a financial incident, a compliance burden that makes Entra-native consolidation more attractive, not less.
That friction is not a knock on the architecture. It is the commercial moat. Every migration toward Entra-native credential management pulls workloads toward Azure’s billing surface. The passwordless rollout is, in structural terms, a churn-reduction mechanism dressed as a security upgrade.
Scenarios Into Oct. 28
Bull Case: Azure accelerates above the 45% guidance midpoint. Management quantifies Entra seat growth with hard figures and links it to enterprise security consolidation. MSFT revisits $625 short-term.
Base Case: Azure lands in the 43 to 45% range. Identity segment mentioned directionally but not broken out. Stock holds the post-July 40% rally, consolidates above $580 support.
Bear Case: Any guidance commentary suggesting multi-cloud integration complexity is slowing enterprise Entra adoption, or gross margin compression from infrastructure build-out exceeds the 67% FY2026 baseline, reopens the $540 level as a downside reference.
The identity market Entra is competing in has its own valuation dynamics worth tracking. Okta’s position in enterprise identity security illustrates how sticky this spending category is and why displacement is so difficult to price.
Framework for Active Positioning
The October 30 deadline for configuring customer-managed telecom providers in the Microsoft Security Store is a concrete near-term catalyst. Enterprise IT teams that miss it face disruption in February for users in scope. That administrative pressure is a revenue pull-forward for Entra SKU upgrades happening now, ahead of the earnings print. Watch Intelligent Cloud segment margins and any disclosure on Entra paid seat adds for the cleaner read on whether the identity mesh is converting security architecture into durable recurring revenue at scale.