At a time when copper demand is growing, a long-dormant copper property is about to thrust one little-known mining company into the spotlight.
It’s all happening in Canada’s Yukon territory, an area with a rich mining history and the kind of infrastructure and friendly regulatory environment that mining companies fight tooth and nail for.
In the case of copper mining, there is one area that has more than a century of history with past production of over 265 million pounds and yet there’s still more to be discovered.
And it couldn’t have happened at a better time.
Countries need copper to build their power grids and move away from fossil fuels.
Tech giants need copper to power their data centers.
And new mines just aren’t coming online at the pace they need to in order to keep up with that kind of surging demand.
It’s a reality the market is only just beginning to wake up to, and that fact is showing up in the price of copper as it marches steadily toward new all-time highs.
Since the process of bringing a mine online and getting the metal out of the ground is so intensive, the few companies capable of doing it are the ones in line to drive returns as more nations and corporations scramble to secure copper supply.
One mining company with assets in that storied Yukon territory is perfectly positioned to seize the opportunity to become a leading name in the copper mining industry thanks to district-scale projects that have produced exceptional results in the past.
Some of these areas haven’t been explored or drilled in over 40 years because of price collapses. But with demand resurging and mining technology having advanced in the time since, now is the time for this area to come back into the conversation.
Results so far have already been promising. Recent results have turned up thick, continuous zones of mineralization that have not only confirmed what past drillers knew, but have expanded beyond that and into new territory.
So this company is only just getting started.
Thanks to its robust treasury, experienced leadership, and ongoing work, it’s well-positioned to profit from rising copper demand into the foreseeable future.
Now’s the perfect time to buy in before more traders become aware of it.
You can learn more about how to do that in our brand-new FREE report where we go over the company, its history, its current assets, and its plans for the future in the unfolding copper bull market.
Click here to access the report now, before time runs out and more people learn about this opportunity.
The AI Trade Just Lost $1.6 Trillion in Six Days
This was the week the market demanded receipts from the AI trade, and the AI trade could not produce them.
Bullet Summary
- The Philadelphia Semiconductor Index fell roughly 10% across six consecutive sessions, its longest losing streak since May 2025, erasing an estimated $1.6 trillion in market value.
- The S&P 500 closed Wednesday at 7,718.94, down 1.11% on the day; the Nasdaq shed 1.88% to 26,692.87 after September CPI came in at 3.7% year-over-year.
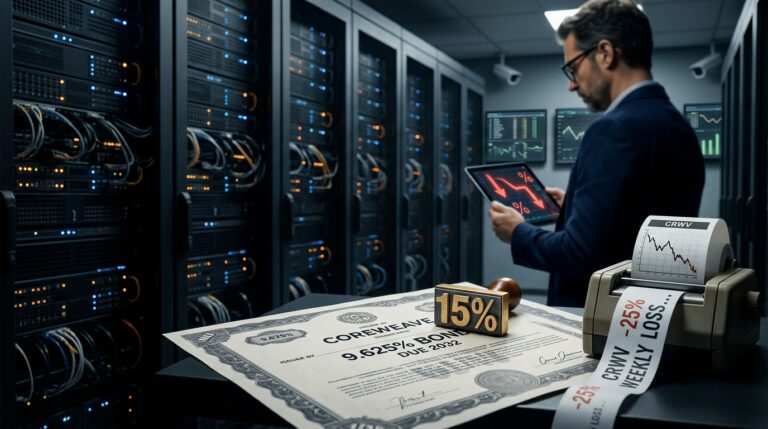
- CoreWeave’s five-year credit-default swap spread briefly exceeded 1,140 basis points; its bonds hit distressed levels, with the June-issued note yielding about 15% against a coupon of 9.625%.
- ARM Holdings fell nearly 20% during the rout; Applied Materials shed 15%; Intel dropped 11%; Nvidia closed Wednesday at $221.30, down 3.16%.
- Thursday brought partial relief: the Dow rallied 556 points to 52,177.69, and the S&P gained 0.33%, as investors rotated into healthcare, materials, and consumer discretionary.
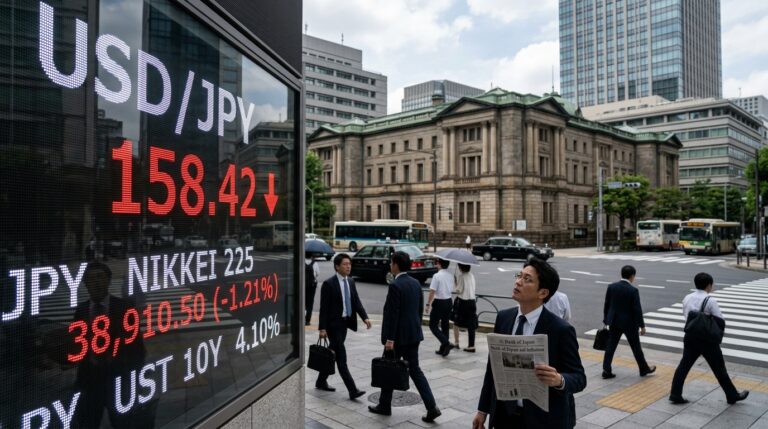
- The 10-year Treasury yield ended Thursday at about 5.10%, around nine basis points lower on the week, after bonds rallied as equity sellers sought safety.
- By Friday midday, the major indexes were choppy, with the Nasdaq down about 1.3% on the day.
A Week Built on Three Collision Points
The rout had a clear architecture. Monday opened with China’s CXMT reporting progress on a proprietary memory chip structure, rattling Micron, which dropped 3.9% that session alone. Tuesday’s bank earnings were mixed: Goldman beat, JPMorgan missed on fixed-income trading, Wells Fargo’s CFO flagged slowing trading activity late in September. None of that helped tech sentiment.
Wednesday delivered the decisive blow. September CPI exceeded market expectations; the S&P 500 fell 1.11% to 7,718.94 and the Nasdaq fell 1.88% to 26,692.87. The strong inflation report bolstered worries that rising interest rates will make it more expensive for companies to fund AI investments. Shares of CoreWeave fell sharply, while Oracle declined almost 9%.
Credit stress at CoreWeave intensified, with its five-year credit-default swap spread briefly exceeding 1,140 basis points. CoreWeave, a data center and compute provider backed by Nvidia, is under scrutiny from analysts as rising interest rates complicate the outlook for the company, which has tens of billions of dollars of debt on its balance sheet.
Thursday’s Rotation and What It Signals
Thursday was not a recovery. It was a rotation. The Dow added 556.21 points to end at 52,177.69; the S&P 500 gained 0.33% to 7,744.06; the Nasdaq closed up just 0.08% at 26,713.03, rebounding from session lows. More than half of S&P 500 stocks are trading above their 200-day moving averages, an improvement from less than 40% at the end of September when gains were more concentrated within tech stocks. Breadth expanding while the sector driving the bull case sells off is not a clean bullish signal. It is capital looking for a safer address.
Strong quarterly results from TSMC and ASML were not enough to arrest the chip selloff. TSMC recorded another record profit and forecast double-digit sequential revenue growth for the fourth quarter, yet the stock fell with the sector. That divergence between fundamentals and price action tells you this week’s move was driven by financing risk and valuation compression, not demand destruction.
What Traders Watch Next
The central question heading into next week is whether the credit stress at leveraged AI infrastructure names spreads to the broader capex supply chain. BlackRock’s research arm downgraded its U.S. stock outlook to neutral, citing potential volatility around the AI buildout; the IMF warned that the consequences of an AI correction could be global. At the same time, several analysts noted that the selloff may reflect positioning and financing costs rather than deteriorating AI demand fundamentals.
The 10-year at about 5.10% and the October 27-28 Fed meeting still on the calendar means the rate variable is not resolved. Traders should monitor CoreWeave’s bond levels as a real-time proxy for stress in the broader neocloud funding market. If those bonds stabilize above 85 cents on the dollar, the equity pressure likely moderates. If they do not, the re-rating of heavily leveraged AI infrastructure names has further to run. Preparation, not prediction, is the only framework that holds in a week like this one.
The rate and credit variables do not resolve in isolation from valuation. Nvidia’s forward multiple cut in half while volume guidance doubles frames exactly how far valuation compression can run before the math forces a resolution.