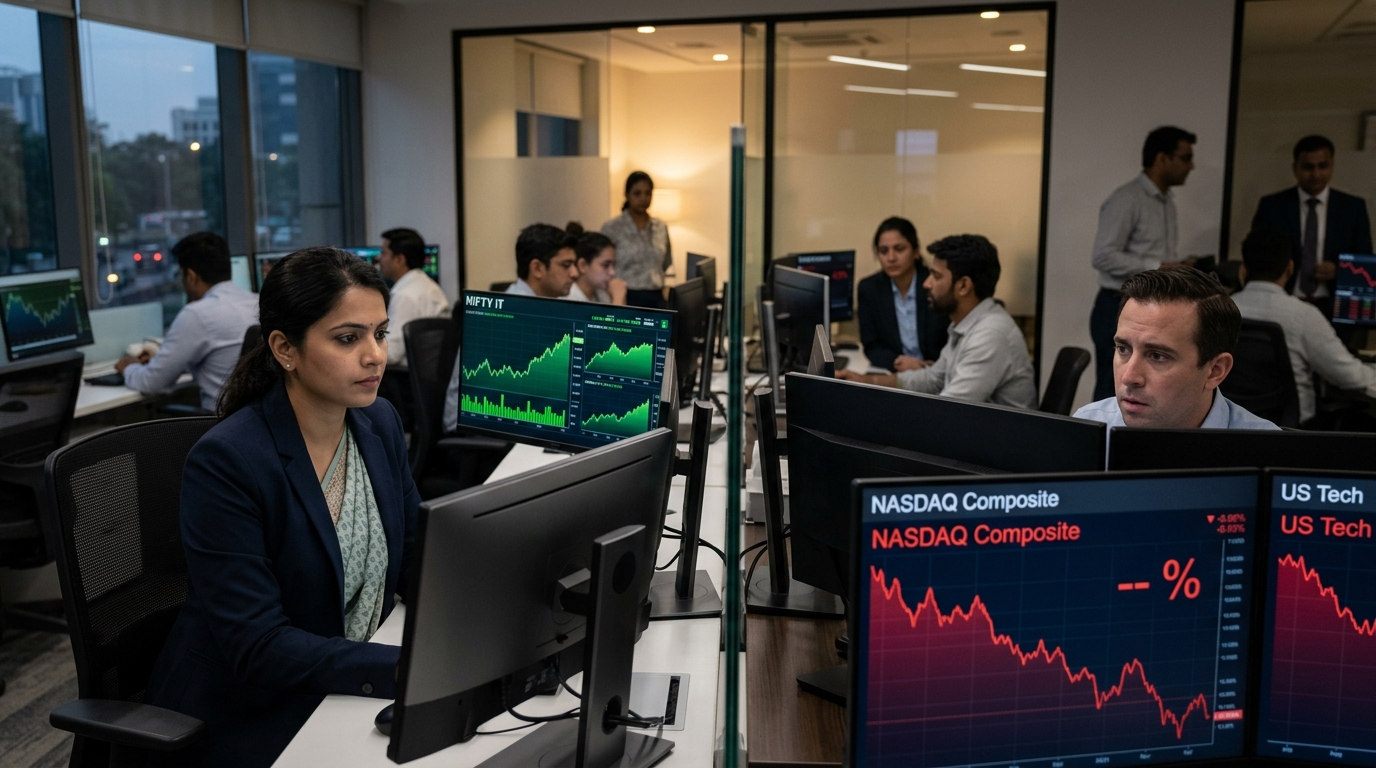
The week ending October 16 produced one of the cleanest divergences in global technology in years. The Nifty IT index surged 11.72%, its biggest weekly gain since April 2008, while the Nasdaq tumbled 4.5% for its worst week since June. That is not noise. That is a rotation with a thesis behind it, and traders who can hold two ideas at once, that AI is real, but that its current capital spending levels may be overextended, now have a concrete instrument to express it.
The catalyst was earnings, not sentiment. Tech Mahindra, TCS, HCL Technologies, Infosys, and Wipro posted strong double-digit weekly gains, powered by stronger-than-expected September-quarter results and a weakening global AI trade that prompted investors to rotate into the software sector. Six of the ten Nifty IT constituents finished the week with gains exceeding 10%, with Tech Mahindra leading after surging 18.7% across four consecutive higher closes.
The numbers underneath those moves are hard to dismiss. TCS reported consolidated Q2 FY27 revenue of ₹73,188 crore, up 11.2% year-on-year, and maintained an operating margin of 24%, securing $9.6 billion in deal wins while lifting its annualised AI revenue run rate to $3.1 billion. That AI revenue figure crossed 10% of total company revenue, signaling faster adoption of AI-led services rather than disruption from them. Meanwhile, HCLTech posted revenue of ₹35,620 crore, up roughly 11.5% year-on-year, with net profit climbing 21.2% to ₹5,132 crore and new deal bookings reaching approximately $3.26 billion.
Tech Mahindra reported consolidated revenue of ₹16,180 crore, a 15.6% year-on-year increase, with net profit surging 32.7% to ₹1,586 crore, underpinned by AI partnerships including its Indus family of models and alliances with Nvidia and AWS. Wipro was the outlier: gross revenue rose 9.1% year-on-year to ₹24,752.7 crore, but net profit fell 1.4%, and total bookings were about $2.6 billion. That split matters for stock selection within the theme.
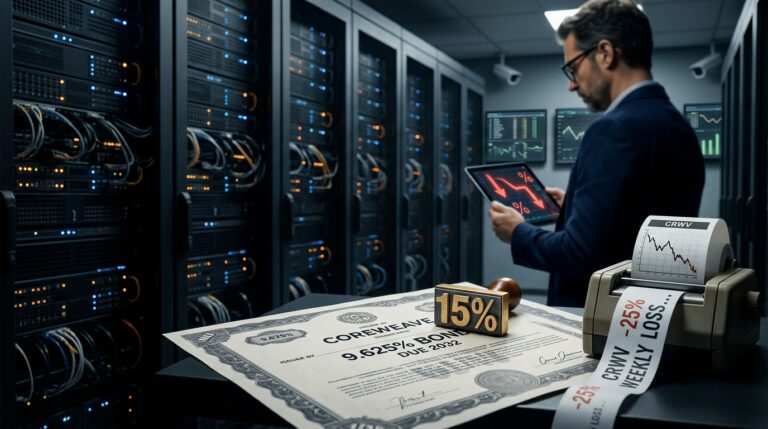
On the other side of the ledger, the U.S. AI infrastructure trade is cracking under its own weight. Investors have grown increasingly concerned that higher borrowing costs could weigh on the massive capital spending required to build out AI infrastructure, putting pressure on companies that have benefited from the AI investment boom. The semiconductor ETF SMH fell about 9% for the week, and it has been led lower by bellwethers including Micron and AMD. AI cloud provider CoreWeave fell 11.9% on Friday and about 25% for the week, and Axios reported that, at the end of June, it had about $35 billion in debt plus roughly $16 billion in debt-like lease liabilities.
The Trade Structure
For U.S.-based traders, the practical entries are the ADRs. Infosys trades on the NYSE under ticker INFY, with one ADS equal to one equity share, while Wipro trades on the NYSE as WIT on the same ratio. INFY closed at $12.24 on October 16, still down sharply from its 52-week high of $30.00, meaning the recovery has room even after last week’s move. TCS and HCL Technologies are accessible via Indian exchanges for those with international brokerage access.
The recent rally has helped the Nifty IT index recoup some of its 2026 losses. Managements are pointing to AI-led revenue rather than AI-led disruption, deal pipelines are healthy outside of Wipro, and the rupee has been a tailwind.
Risks and Levels to Watch
The thesis breaks if U.S. enterprise spending slows sharply, pulling discretionary IT budgets globally. A Fed rate hike, with the 10-year Treasury yield around 5.09% as of Friday’s close, would compress multiples on both sides of this trade. Within the Indian names, Wipro’s bookings slide is a warning worth monitoring as the others report full-quarter results. Infosys reports on October 23; that result will either confirm or complicate the sector bid.
The Nifty IT index reclaimed the 30,000 level last week and closed Friday at 31,924. A pullback toward 30,500 on any near-term Nasdaq stabilization would represent an attractive re-entry. The highest-conviction long within the ADR universe remains INFY on valuation grounds, with WIT as a secondary position for traders who want broader exposure. TCS and HCL Technologies, accessible through international accounts, offer the cleaner earnings momentum.