October 19, 2026
Bonus Content: HON Reports in Three Days. The sCO2 Valve Question No One Is Asking.
|
A SPECIAL INVESTOR STORY · FALL 2026 Are Pesticides An essential global industry is facing a familiar collision of public pressure, regulation and technological change. |
For decades, tobacco looked permanent.
It was deeply embedded in daily life, supported by powerful companies and protected by enormous demand. Then the evidence, lawsuits, regulation and public sentiment began to converge.
The industry did not disappear overnight. But capital, consumer behavior and corporate strategy began to move.
|
Chemical pest control is essential to agriculture, public health, homes and businesses. Yet concern around conventional formulations continues to grow – from exposure and residues to resistance and environmental impact.
That creates a paradox investors should not ignore:
|
The world could quit smoking. |
If pressure forces the category to evolve, demand does not vanish. It may migrate toward products designed to meet changing expectations.
|
One small company has spent years building botanical pest-control products for professional and consumer use. Its name is Med-X, Inc. The company is currently private and has reserved MXRX for possible use following a successful future Nasdaq listing. Its Nature-Cide portfolio sits directly inside this developing conversation.
This is not a prediction that pesticides will become tobacco. It is a question about what happens when an indispensable industry can no longer remain exactly as it was.
|
Discover the evidence, the market transition and the company positioned inside it.
HON Reports in Three Days. The sCO2 Valve Question No One Is Asking.
Honeywell International reports Q3 2026 results before the open on October 22. Consensus sits at $2.17 in earnings per share on $5.01 billion in revenue, a reported decline of 51.8% year over year driven largely by the Q3 reporting reset after the Honeywell Aerospace spin-off completed June 29. Strip the separation noise and the automation business underneath is tighter than that headline implies.
The segment traders should map carefully is Process Automation and Technology. In Q2 2026, PA&T posted $1.679 billion in sales, up 4% year over year on a reported basis but down 1% organically, with segment margin compressing 180 basis points to 22.1%. Analysts now expect Q3 PA&T sales near $2.01 billion, a 7% year-over-year rise, but the thesis is complicated: softness in refining catalyst volumes and project timing in the Middle East weigh directly on the segment’s near-term conversion rate.
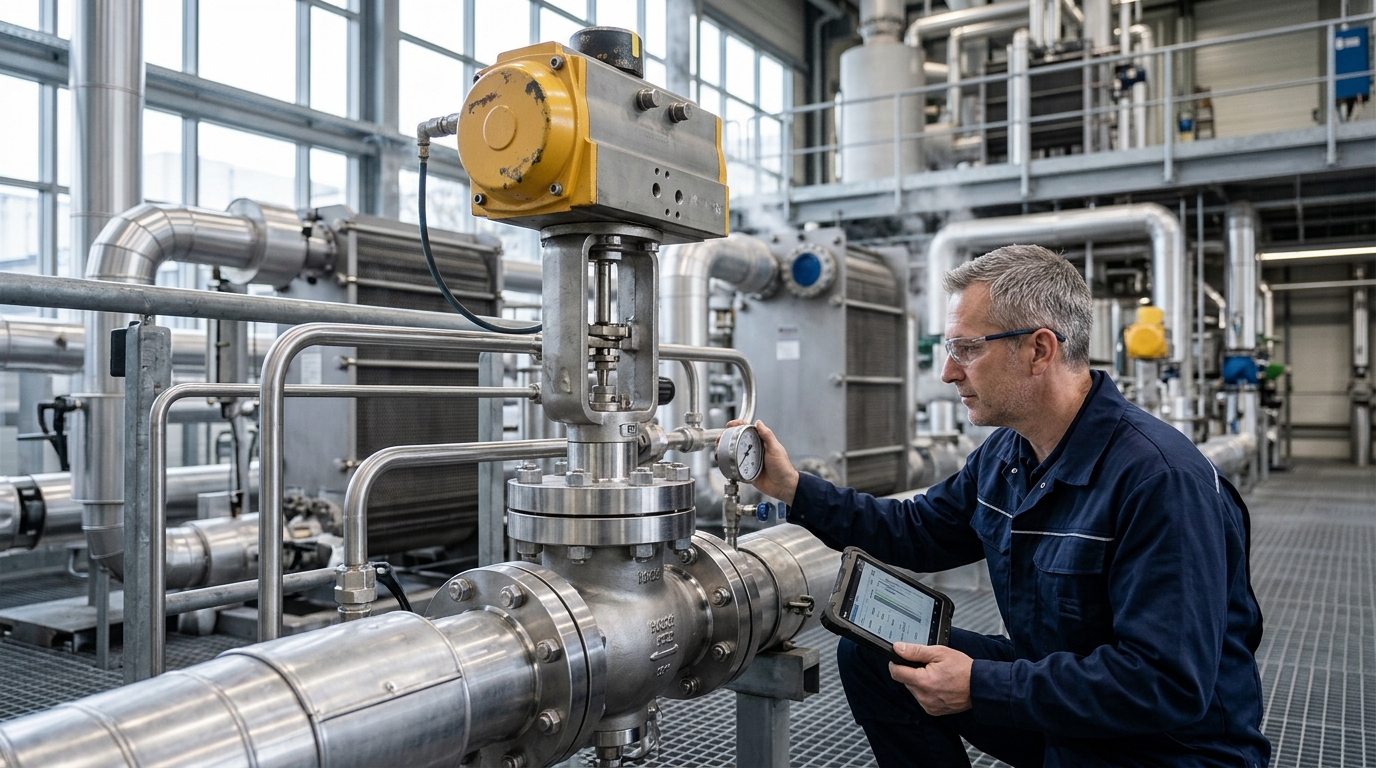
Here is what that segment disclosures do not cleanly surface. PA&T sits directly in the path of a supercritical CO2 infrastructure buildout that is accelerating on two fronts simultaneously. Carbon capture and storage is generating demand for extreme-tolerance control valves rated above 73.8 bar, the threshold at which CO2 becomes supercritical and sealing requirements tighten materially. At the same time, sCO2 power cycles are moving from DOE-funded pilots toward commercial scale. A Denver-based startup called American Supercritical emerged from stealth last month with $8 million to commercialize factory-built sCO2 power blocks, pitching a 50% electricity uplift bolted onto existing gas turbine exhaust stacks with no re-permitting required.
Honeywell’s position in this value chain is not accidental. The $2.16 billion acquisition of Sundyne, completed in June 2025, brought in high-head, low-flow compressors and pumps designed for high-pressure process applications. Those are the same pressure regimes relevant to dense-phase CO2 transport and injection. What matters for traders is not whether any single product line is “the” sCO2 answer, but whether incremental high-spec valve and turbomachinery demand shows up in orders, backlog, and margin mix inside a segment that still screens, on the surface, like a steady mid-single-digit grower.
The high-temperature floating ball valve market, which captures part of the sCO2 and high-heat-transfer media use case, is projected to grow in the mid-single digits through 2035 in recent IndexBox analysis, with global baseline growth closer to the 4% range than the headline numbers traders typically assume. Separately, some market-research estimates place the broader transcritical CO2 systems market near $41.4 billion in 2026 with a path toward roughly $120.7 billion by 2033, implying a mid-teens CAGR. Neither of these growth rates shows up in PA&T’s current organic sales trajectory.
Scenario Framework
Bull case: PA&T organic growth reaccelerates in Q4 on LNG project backlog conversion and initial sCO2-related contract disclosures. HON guided full-year adjusted EPS of $8.05 to $8.35; upside of 5 to 7% in segment margin would push the stock toward the $240 area.
Base case: Q3 PA&T delivers near the $2.01 billion consensus with margin near 21%, consistent with the company’s second-half framing after Q2. sCO2 contract activity remains unquantified in segment reporting. HON trades in a $215 to $225 range into year-end as the automation re-rating thesis grinds rather than catalyzes.
Bear case: Middle East project deferrals deepen, catalyst volumes disappoint a second consecutive quarter, and PA&T margin falls below 20%. At 20 times forward earnings on $8.10 EPS, the stock finds support near $200, with the Sundyne integration timeline becoming a consensus concern.
Trading Framework
The October 22 release is three days out. Implied volatility on HON is pricing a moderate move given the separation complexity in reported numbers. Watch PA&T segment margin and orders commentary for any mention of sCO2 or CCUS project pipeline. The backlog context is not small: as of June 30, 2026, Honeywell reported total backlog of $38.0 billion, which means the revenue question is largely a timing question. The structural positioning question is different: at what point does Honeywell’s exposure to extreme-pressure CO2 environments appear as a line item rather than a footnote inside a $5 billion automation company.
Preparation means knowing those levels before the October 22 open. The segment margin will tell you whether the quarter is a miss or a beat. The order commentary will tell you whether the sCO2 buildout is already inside Honeywell’s backlog or still priced at zero.