October 25, 2026
Bonus Content: Microsoft’s Factory AI Won Its Own Award. Now Traders Must Price What Comes Next.
Dear Reader,
The stock market just entered a highly dangerous new phase. And if history repeats, it will have drastic consequences for investors.
The signs are everywhere:
Two wars are raging. Our government is $40 trillion in debt. And everywhere you look, people are predicting a crash.
But if you’re thinking of selling everything and hiding in cash… hold that thought for a moment.
Something very strange is happening…
I’ve published my research every month since 1980.
In that time, I told my readers to sell everything a few weeks before Black Monday.
Then, in January 1995, I said the Nasdaq would “double, then double again.”
And in March 2009, the exact month stocks bottomed, I told investors to get back in.
But what I see coming today could come as an even bigger surprise.
If you care about your wealth, your family and your retirement, you need to understand what’s going on.
I’ve laid out exactly what I see in a free broadcast with my colleague, Matt McCall, along with the specific steps I recommend you take with your money today.
I strongly encourage you to check it out here.
Yours for peace, prosperity, and liberty, AEIOU,
Dr. Mark Skousen
Macroeconomic Strategist, The Oxford Club
P.S. What’s happening today could make or break your retirement. If I’m even half right, it’s going to have a huge impact on your money and your future. Get the details here…
Microsoft’s Factory AI Won Its Own Award. Now Traders Must Price What Comes Next.
Microsoft’s generative spatial-twin engine is no longer a lab project. It is a production system that won the 2026 INFORMS Franz Edelman Award, a top prize in applied operations research. The angle most coverage missed: Microsoft built this on its own supply chain first, and the commercial implications for Azure’s industrial vertical are only beginning to surface as MSFT heads into its fiscal Q1 FY2027 report on Wednesday, October 28.
What the IFS Numbers Actually Say
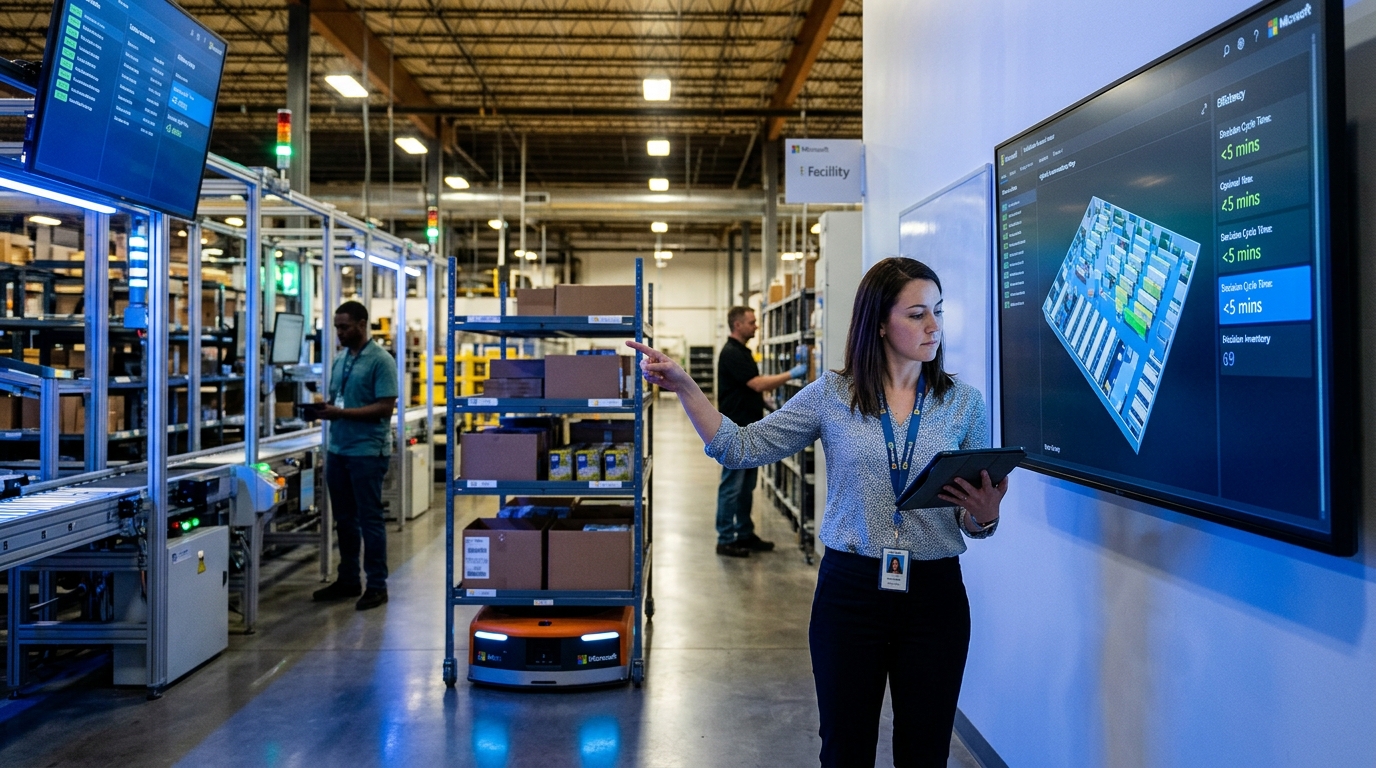
Microsoft’s Intelligent Fulfillment Service (IFS) integrates machine learning, mathematical optimization, and generative AI to coordinate hyperscale fulfillment decisions across cloud demand, server supply, and data center capacity, cutting cycle times by more than 50% and delivering hundreds of millions of dollars in annual savings. That is not a pilot metric. It is an operational result across Microsoft’s own cloud supply chain spanning more than 70 Azure regions and over 400 datacenters.
The specific mechanism matters for traders evaluating the commercial replication story. IFS’s LLM-powered assistant, based on the OptiGuide framework, reduced fulfillment team workload by 23% and compressed decision-making from days to minutes. Microsoft has deployed more than 25 AI agents and applications across its supply chain, with a goal of operating over 100 by the end of 2026. The scaling trajectory is explicit.
The competitive pressure on that workload reduction claim runs in both directions. Falling inference costs from rivals are compressing the unit economics for every enterprise AI pipeline, which shapes how aggressively Azure can price IFS-style commercial deployments.
The Digital Twin Layer Underneath
What distinguishes the current enterprise digital-twin push from earlier iterations is deeper integration of generative AI and large language models, plus the operational push to connect multiple twins into a single thread across the supply chain, so planners can quantify how upstream performance propagates into downstream production and service levels. Claims of 88-97% failure prediction accuracy and 60-90 days of early warning vary sharply by asset type, data quality, and how narrowly the failure mode is defined, so treat those figures as best-case case-study outcomes rather than a baseline expectation.
That said, meaningful early-warning lead time can still restructure maintenance economics. For a factory running $50M in annual parts spend, even a modest reduction in unplanned downtime can justify a six-figure Azure contract if the implementation is scoped tightly and the data estate is already in order.
The MSFT Earnings Lens
In Microsoft’s fiscal Q4 FY2026, Azure and other cloud services revenue grew 43%, up from 40% in the prior quarter; the Intelligent Cloud segment posted revenue of $39.3 billion, up 32%. Commercial remaining performance obligations rose 84% to $678 billion. That backlog is broad-based and includes multi-year enterprise commitments, but it is not a clean proxy for industrial digital-twin or IFS-specific demand.
Microsoft reports fiscal Q1 FY2027 results on October 28. Bank of America reiterated a Buy rating ahead of earnings and forecast roughly 45% Azure growth. MSFT price levels, moving averages, and month-to-date highs should be checked against live market data.
Scenario Modeling
Bull Case ($570+): Azure reports 46%+ growth Wednesday, and management quantifies industrial vertical contract wins. The IFS commercial licensing story gains analyst attention as a separate revenue driver. RPO re-accelerates.
Base Case ($520-545): Azure meets the 44-45% consensus. Industrial digital twin revenue remains bundled inside Azure, so the market prices it generically. Stock holds near its 50-day moving average as earnings confirm the growth rate without surprising to the upside.
Bear Case (below $505): Azure disappoints at 41-42%, capex guidance rises further, and gross margin compresses below 67%. Q4 FY2026 capex was about $41 billion; any signal of acceleration without corresponding revenue pull-through weighs on sentiment.
Active Trader Framework
The $508 level, the 50-day moving average, is the structural anchor. A post-earnings close above $545 opens a retest of the October high near $551. Position sizing before earnings carries binary risk; the more controlled framework is to wait for the Azure growth figure Wednesday and then assess whether the industrial digital twin business is being broken out in management commentary. That disclosure, or the absence of it, tells traders how seriously Microsoft is taking the commercial monetization of IFS. Volatility around the report will be elevated. Discipline in level selection matters more than conviction on direction.