November 6, 2026
Bonus Content: IREN’s AI Revenue Nearly Tripled. Its Stock Hit a 52-Week Low.
Dear Reader,
My name is Jeff Brown, founder and CEO of Brownstone Research.
And I want you to circle one date on your calendar…
That’s the day a tiny company could announce a huge supply deal with Elon Musk.
It’s a stock trading at under $1…
In an overlooked sector you’d never associate with tech.
But Musk’s robots, microchips and AI satellites all rely on it.
And on page 37 of the SpaceX IPO filing, Musk names this sector directly.
Why does that matter?
Because Musk raised $85.7 billion from the SpaceX IPO…
And a further $25 billion by selling bonds.
That money is about to flow downstream.
And when a Musk supplier in this sector announced a deal before…
The stock soared 395% in a single day.
That’s almost five times your money…
Before the sun goes down.
I recently sat down with an insider in this sector to talk about what could happen on November 11.
A man who once turned $13,140 of his own money…
Into around $1.85 million in under a year.
In our urgent strategy session, we reveal the name and ticker of a crucial Musk supplier…
Entirely for free.
But once November 11 arrives, this opportunity could be gone.
Click here to watch the strategy session before November 11.
We have so much to look forward to,
Jeff Brown
Founder & CEO, Brownstone Research
IREN’s AI Revenue Nearly Tripled. Its Stock Hit a 52-Week Low.
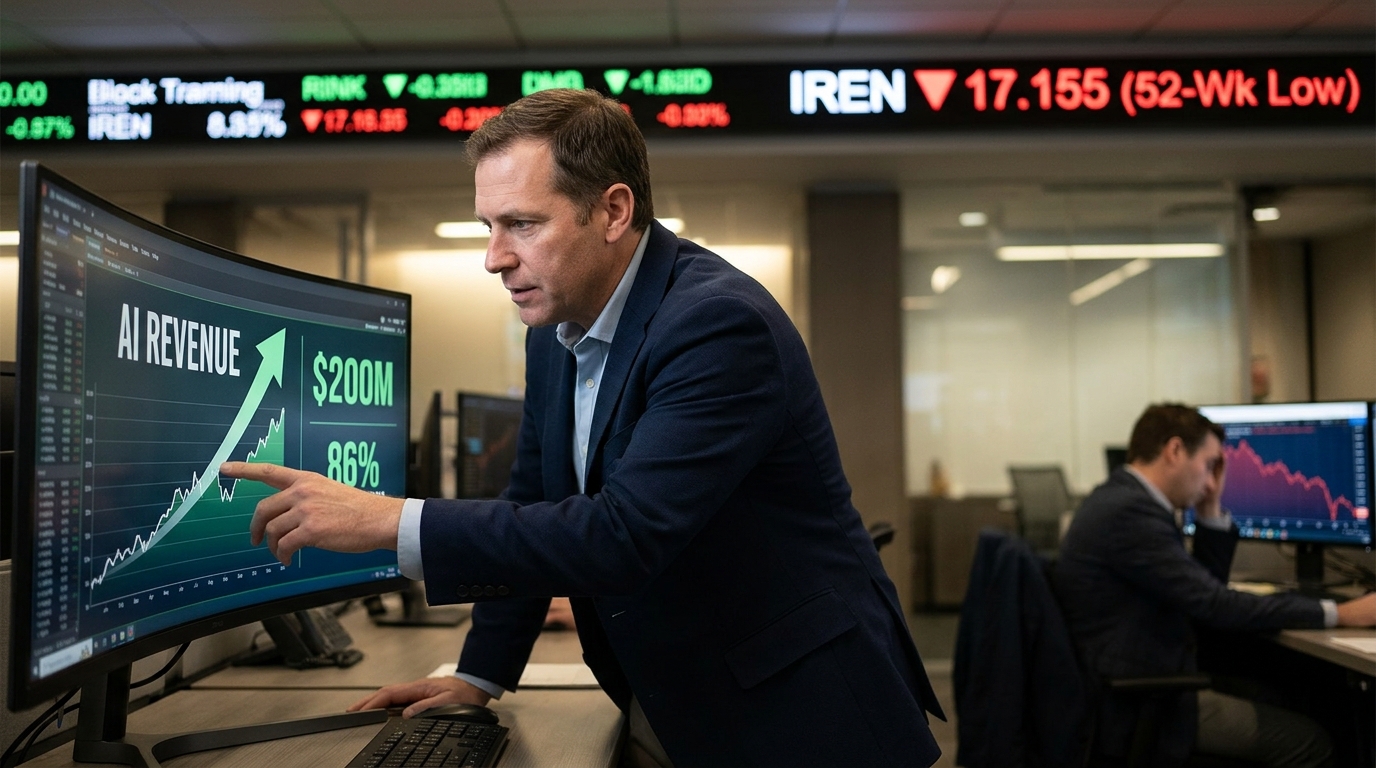
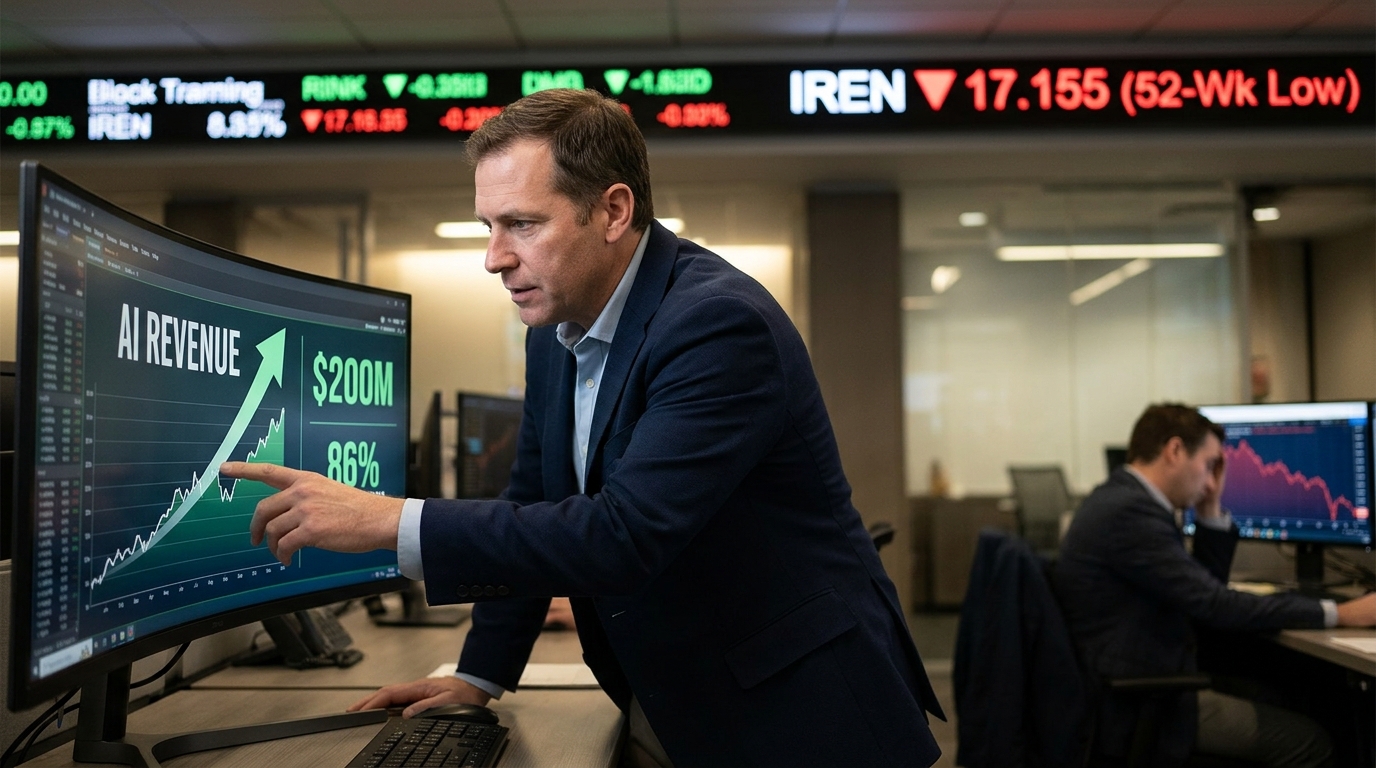
Two numbers landed Thursday and they point in opposite directions. IREN reported total quarterly revenue of $228 million, up 66% sequentially, with AI Cloud revenue rising 182% to $200 million at an 86% segment gross margin. At the same moment, the shares hit a fresh 52-week low of $17.155 as the neocloud complex was hammered following a Bloomberg report that Microsoft was tightening oversight of data center projects involving IREN, Nebius, and Nscale.
What the Quarter Actually Showed
Revenue of $228 million beat the $221.71 million average analyst estimate, per Yahoo Finance’s LSEG-derived consensus data. AI Cloud Services contributed $135 million and AI Cloud Lease revenue added $65 million, bringing total AI Cloud to $200 million versus $71 million the prior quarter. Bitcoin Mining delivered $28 million, down from $67 million, as the company continues decommissioning mining hardware to prioritize GPU installations. The revenue backlog rose 22% sequentially to $20.3 billion, approximately two-thirds with investment-grade counterparties.
Operating ARR doubled to $1 billion, and the backlog growth helped reassure some investors that the underlying demand picture remains intact. IREN said its assets and revenue are underpinned by customer contracts with NVIDIA, Microsoft, and 13 other customers.
The Microsoft Overhang
The selloff predated the earnings release. IREN closed Thursday, November 5, 2026 at $18.03, down 16.95%, after Bloomberg reported that Microsoft had tightened oversight of neocloud data center projects at Nebius, IREN, and Nscale. Microsoft is reportedly stepping back from projects it considers risky and weighing whether to sign new deals with neocloud providers as it focuses more heavily on expanding its own data centers.
IREN disclosed that more than $4 billion of ARR that had previously been targeted for year-end 2026 is now targeted for January 2027 and may extend to the end of February 2027, following a customer-requested change and supplier timing. On the company’s earnings call, co-CEO Daniel Roberts said Microsoft requested a reconfiguration and upgrades to part of the network infrastructure so that the 200 megawatts of capacity could support the latest generation of frontier models.
Sector Context
IREN is not alone in the pressure. The broader liquidation reflects a capital-structure problem that has been building for weeks. IREN’s balance sheet is structurally different: the company said it has $9 billion of cash and committed GPU financing and prepayments, with a further $6 billion of target GPU financing, prepayments, data center financing, and other corporate-level sources described as subject to market conditions.
The financing structure underneath the neocloud buildout is itself under scrutiny. Nvidia’s move to mobilize institutional capital for GPU financing reshaped how lenders think about AI infrastructure as collateral.
Technical Framework
IREN has produced a series of lower highs and lower lows since reaching its significant high, with the weekly structure remaining bearish. Thursday’s intraday low of $17.155 is now the reference point. Volume on Thursday ran roughly 2.8x the 46-million-share daily average, a capitulation-scale reading that often precedes at least a tactical low. RSI readings entered deeply oversold territory.
Scenario Modeling
Bull Case: The more than $4 billion ARR target lands operationally by January 31, Microsoft’s network-design changes prove routine, and price action above $20 holds. Analyst price targets vary widely across providers, with some published ranges reaching as high as $139 on the top end and nearer to the high-$30s on the low end, implying substantial recovery potential if the backlog converts on schedule.
Base Case: ARR deployment slips toward late February. Revenue continues compounding at high margins but sentiment stays depressed until Microsoft’s posture toward neocloud partners clarifies. Shares trade a $17-$25 range pending the next operational milestone update.
Bear Case: The $6 billion in target financing, described as subject to market conditions, does not close on schedule. Microsoft signals further project scope reductions. The $17.155 intraday low breaks on renewed volume, with no structural support until the low-teens.
Active Trader Framework
The divergence between IREN’s operational metrics and its share price creates a classic information-asymmetry moment. The 86% AI Cloud segment gross margin on a $200 million AI Cloud quarter is a real number; so is the $17.155 low. Neither resolves the other on its own.
Traders focused on the long side should require Thursday’s low to hold on a closing basis and watch for confirmation that the more than $4 billion ARR target is operational by January 31, 2027, as guided. Position sizing must account for a beta above 4 and a capital structure that still carries $6 billion in market-dependent target funding. Analyst ratings are not uniform across all data providers, so any single count of “buy” versus “sell” recommendations should be treated as source-dependent rather than definitive. Manage size accordingly, and let the January ARR milestone do the confirming work before scaling.