Dear Friend,
I’m giving you a free stock pick today.
It’s not Tesla. It’s not SpaceX.
It’s the American company sitting on the one metal Elon can’t launch without.
Silver.
Every solar panel on every Starlink satellite is printed with it.
And Elon just filed to launch 1,000,000 satellites.
On January 1st, a deadline Congress set squeezes Chinese suppliers out of America’s solar factories.
American silver becomes the prize.
Dylan’s found the company with a legendary silver mine and a refinery 1 mile away.
He believes this stock takes off January 1st.
See today’s free silver pick here >>
The Buck Stops Here,
Kelly Maguire
Behind the Markets
P.S. It trades on the NYSE, so a few clicks in any brokerage account and it’s yours. Just don’t wait past January 1st.
Franco-Nevada Reports Wednesday. The Volume Question Matters.
Franco-Nevada posts its Q3 2026 results after the close on Wednesday, November 11, with analysts expecting about $1.77 per share on about $568 million in revenue. Those numbers look conservative against a macro backdrop that has gold trading around $4,128 on Monday morning, up about 1.3% on the session and pressing toward the $4,147 resistance level that capped Thursday’s post-midterm rally. The real question for traders is not whether revenue beats. It is whether gold equivalent ounce volume finally stops declining.
The Margin Math Is Exceptional. The Volume Trend Is Not.
In Q2 2026, Franco-Nevada delivered $580.9 million in revenue, up 57% year-over-year, on 132,405 GEOs sold, an 18% volume gain. That sounds strong until you realize GEOs fell sequentially versus Q1 2026. Adjusted EBITDA landed at $529.7 million, a 91.2% margin, down from 99.0% a year earlier. The company missed the $1.95 consensus EPS estimate by $0.14, posting $1.81. The margin compression and volume softness drove the miss, even as the first-half revenue record of $1.231 billion was set. Price did the work. Volume did not.
The core dynamic here is structural. Franco-Nevada converts non-gold revenue to GEOs using fixed conversion ratios based on the commodity-price assumptions in its 2026 guidance, including $4,500 per ounce gold. With spot gold currently near $4,100, realized pricing sits below that guidance assumption, which mathematically shrinks reported GEO counts on diversified assets. That is not a business deterioration. It is an accounting effect. Traders who confuse the two misprice the stock.
The Cobre Panama Wildcard
The Cobre Panama stream, halted since late 2023, is the single largest potential volume catalyst. After Panama’s government authorized stockpile processing in early Q2, management guided for 9,000 to 10,000 GEOs from the asset in the second half of 2026. The company was already tracking toward the upper half of its 510,000 to 570,000 GEO annual guidance range due to elevated oil prices and anticipated deliveries from the stockpile processing program. A full Cobre Panama restart at capacity could add 150,000 to 175,000 GEOs annually, implying roughly 45% five-year GEO growth from current levels. Wednesday’s call will specify how much of that stockpile processing actually landed in Q3.
Scenario Modeling
Bull Case ($270+): Q3 GEO volume recovers sequentially above 135,000, Cobre Panama contributions come in at the high end of guidance, and management raises full-year GEO outlook. Gold holds above $4,107 through CPI on Tuesday. FNV re-rates toward the $282 consensus analyst target.
Base Case ($235-255): Revenue meets or modestly beats at $570-580 million. EPS prints near $1.80. Volume is roughly flat sequentially, Cobre Panama delivers on guidance, and the stock holds its current range. No re-rating catalyst, but no breakdown either.
Bear Case (below $220): Volume declines a third consecutive quarter, EPS misses again, gold slides below $4,054 support after Tuesday’s CPI surprises to the upside, and the stock tests the $213-220 zone. FNV’s low historical beta limits the downside, but a simultaneous gold selloff and volume miss is a punishing combination at any margin multiple.
Active Trader Framework
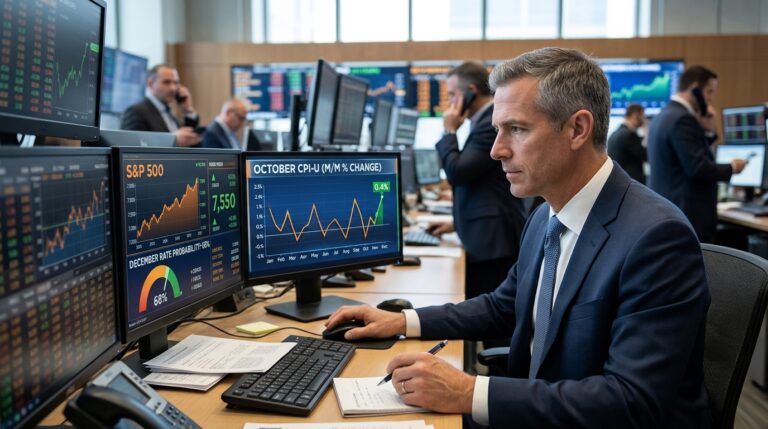
Key levels: $4,107 is gold’s intraday support today; a close below that number ahead of the earnings release shifts sentiment quickly. For FNV specifically, the 52-week range runs $188.47 to $285.67. The stock is mid-range. Position sizing should reflect that the report lands after the close on Wednesday, while CPI lands at 8:30 a.m. Eastern on Tuesday, concentrating two separate volatility events into a tight 36-hour window. Options implied volatility typically expands into FNV earnings; traders should account for that when setting stops rather than assuming the stock moves in line with gold tick-for-tick.
Preparation beats prediction here. The margin engine is elite. The volume trajectory is the only variable that changes the medium-term valuation. Wednesday’s GEO count is the number that decides which case you are in.