Back in the 1860s, settlers from France, Italy, and Germany built grand Parisian boulevards…
…neoclassical facades…
… and cobblestone Bavarian villages halfway across the globe.
Then the rest of the world largely forgot about them.
Today, expats are uncovering a European standard of living…
… Lakefront rental homes for $721 a month…
… private chauffeur service…
… and elite healthcare – completely free from tourist crowds and inflated European price tags.
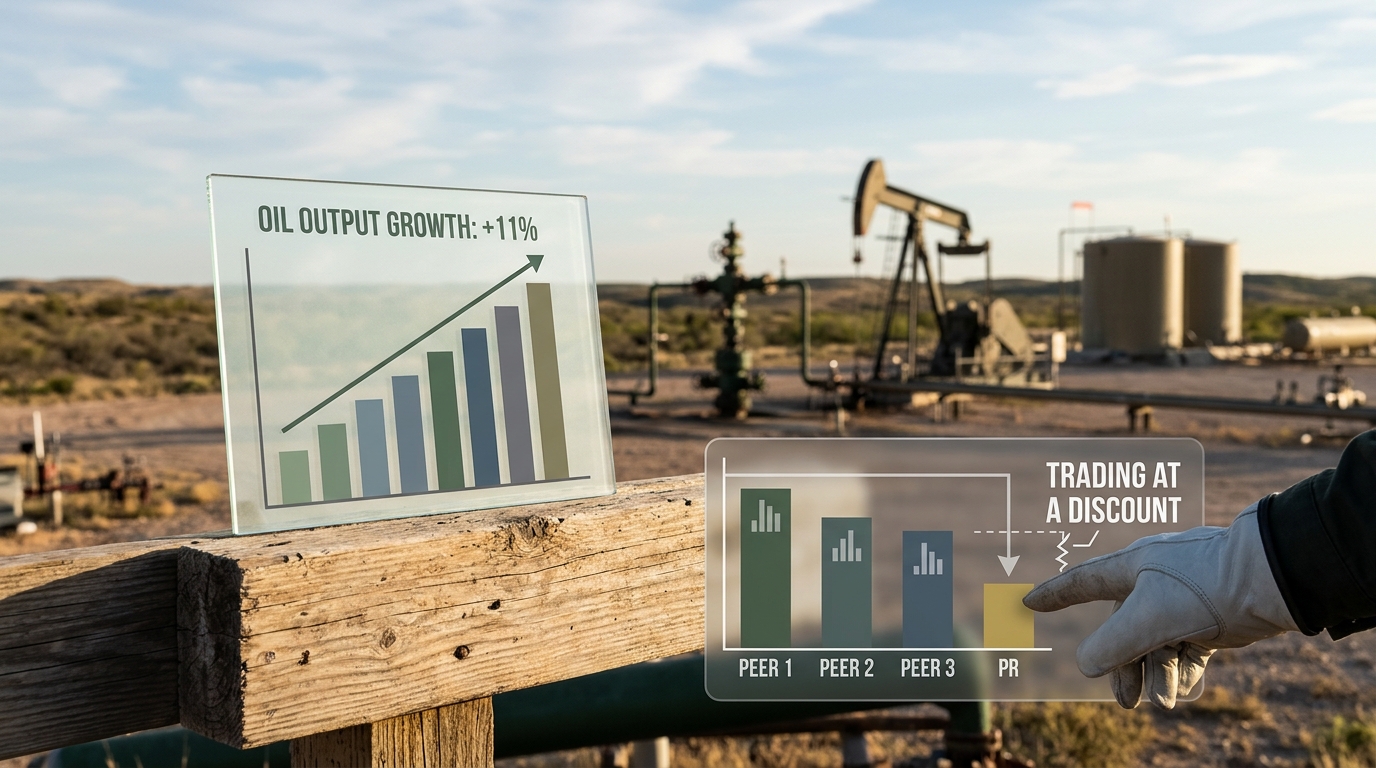
Permian Resources Is Growing Oil Output 11% While Its Stock Trades at a Discount to Peers
Permian Resources (NYSE: PR) reported Q3 2026 results on November 4 that should have been a catalyst. They were not, at least not yet. The stock closed that session at $22.43 and has since drifted to roughly $21.52 as of the November 10 close. The sell-off created a measurable gap between what the company is producing and what the market is currently pricing in.
The Numbers Behind the Dislocation
Q3 oil and gas sales were $1.96 billion, up 48% year-over-year. The company also reported record free cash flow of $0.98 per share, driven by higher production and lower costs. Controllable cash costs hit a record low of $7.05 per Boe.
Management reiterated it is on track to grow oil production 11% for the full year while reducing costs year-over-year, and it raised the full-year oil production midpoint to 202,000 barrels per day. Q4 oil production is expected to exceed 210,000 barrels per day.
That is operating leverage working exactly as intended: volume growth absorbing a fixed cost base. Through continued strong free cash flow generation, the company expects to hold less than 0.5x leverage at year-end 2026.
Where the Valuation Argument Lives
PR currently trades at a forward EV/EBITDA of about 5.7x. The company itself has shown peer EV/2026E EBITDAX multiples around 7.5x for the “Permian Pure-Plays” group, implying meaningful upside if the valuation gap closes. The gap is not trivial, and it is the core of the bull thesis.
Twenty-two brokerages carry a consensus Buy rating with an average 12-month price target of $26.61. Raymond James reiterated a Strong Buy and set a $34 price target on November 2. Against a current price near $21.52, that is a 58% implied return from one of the more visible energy desks on the Street.
Permian pure-plays are not the only upstream names trading at a discount to their production growth. Shell’s acquisition of ARC Resources added 370,000 boe/d and reset the benchmark for what a low-cost upstream growth story can command in valuation.
The Cost Discipline Story
PR has continued to point to structurally lower drilling and completion costs per lateral foot versus prior years. The key takeaway for traders is unchanged: the company is growing production while unit costs compress, supporting free cash flow that is less dependent on a single quarter of commodity price strength.
Scenario Framework
Bull Case: WTI stabilizes above $75, Q4 oil production clears 210,000 bpd as guided, and the EV/EBITDA multiple re-rates toward the 7.5x peer level shown in company materials. Price approaches $27 to $29, within the mid-range of analyst targets.
Base Case: Oil prices hold in the low-to-mid $70s. Free cash flow generation remains strong at current unit costs. The stock grinds toward $24 to $26 as the valuation discount narrows incrementally. The $0.64 annualized dividend remains the company’s base payout level.
Bear Case: Crude drops below $65 on demand weakness or a resolution of supply constraints. The 50-day moving average is near $23.3 and the 200-day is near $20.6 as of November 10. A loss of the longer-term trend level would reopen a test of the mid-$18 range.
What Traders Watch Next
The critical levels are about $20.6 on the downside, where the 200-day moving average sits, and roughly $23.3 on the upside, the 50-day. A reclaim of the 50-day on volume would shift near-term momentum. In Q3, adjusted free cash flow was about $846 million, giving management capital flexibility, including bolt-on acquisitions and debt reduction, that the market appears to be discounting. The cost structure and the balance sheet both argue for patience. Oil price direction will determine the timeline.