November 16, 2026
Bonus Content: China’s October Miss: What It Means for Copper and Ore
Editor’s Note: Hedge fund legend Larry Benedict, who delivered $274 million in profits to his hedge fund clients, says Washington sets the days billions could pour into the market months in advance… and the next one could come December 9. He’s revealing his ONE ticker for those days, FREE. Click here to see the details or read more below…
Dear Reader,
Grab this three-letter ticker before Wednesday, December 9.
Because Washington just triggered a rare wealth-building window…
Where billions of dollars could surge into the market about every 11 days…
Handing everyday Americans a shot at pocketing YEARS of gains in ONE trade.
And hedge fund legend Larry Benedict…
A man famous for going 20 straight years without a losing year…
Says December 9 is just one of more than 30 days like it over the next 12 months.
The best part is, every one of them is pre-determined.
Which makes this one of the most predictable and exciting opportunities he’s seen in decades…
Especially since the last time it opened, anyone who followed Larry’s trades…
Could have collected YEARS of market gains over and over again, like:
More than FIVE years in a week…
Almost SEVEN years in six days…
Even 17 YEARS of gains… in a matter of HOURS.
All around pre-determined days, just like December 9.
If you act now, you could have a chance to potentially pocket tens of thousands of dollars over the next 12 months.
In a new interview, he walks through his strategy step by step…
And names the ONE three-letter ticker he trades most on days like these.
It’s FREE to watch.
Regards,
Lauren Wingfield
Managing Editor, The Opportunistic Trader
P.S. The last time this wealth-building window opened, anyone who followed Larry Benedict’s trades could have made more than 57 YEARS of market gains in under 11 months. Click here to get his ONE ticker FREE before December 9.
China’s October Miss: What It Means for Copper and Ore
China’s National Bureau of Statistics released October activity data at 10:00 a.m. Beijing time Monday, and the key headline lines missed expectations. Retail sales rose 0.4% year on year versus a 0.8% forecast, down from 1.1% in September. Industrial output climbed 4.8% y/y, short of the 5.3% estimate and down from 5.5% in September. Fixed-asset investment fell 8.1% year to date (January to October), worse than the expected 7.0% decline. October should have benefited from the seven-day national holiday and the extended Singles’ Day promotional period, but consumers still delivered the weakest spending pace since August.
Bullet Summary
- Retail sales: +0.4% y/y vs. +0.8% forecast; prior +1.1%
- Industrial output: +4.8% y/y vs. +5.3% forecast; prior +5.5%
- Fixed-asset investment (Jan-Oct): -8.1% vs. -7.0% expected; prior -7.2%
- Property investment (Jan-Oct): -21.6%
- Copper (COMEX, Nov. 16): about $6.01/lb, down about 1% on the session
- Iron ore (Singapore benchmark): roughly low-$90s per tonne into mid-November
Market Context Analysis
These numbers land at the worst possible diplomatic moment. The White House has confirmed President Donald Trump will meet Chinese leader Xi Jinping in Shenzhen on Thursday, November 19, 2026, including a bilateral working lunch. U.S. officials have also confirmed an unprecedented trilateral meeting on the APEC sidelines involving Trump, Xi, and Russia’s Vladimir Putin. With a trade truce described publicly as extended into January (without a clearly confirmed day in the White House readouts), the market is left with a narrow window where headlines can matter as much as hard data.
Sector Breakdown: Where the Data Actually Bites
China’s fixed-asset investment contraction over January to October is the macro transmission channel traders need to respect. The more that capex and construction remain weak, the more iron ore and coal feel it through steel throughput and inventory behavior. Copper is not immune, but it is cushioned by supply tightness and electrification plus AI-related demand, which is less directly tied to Chinese household consumption.
Stock-Specific Financial Breakdown
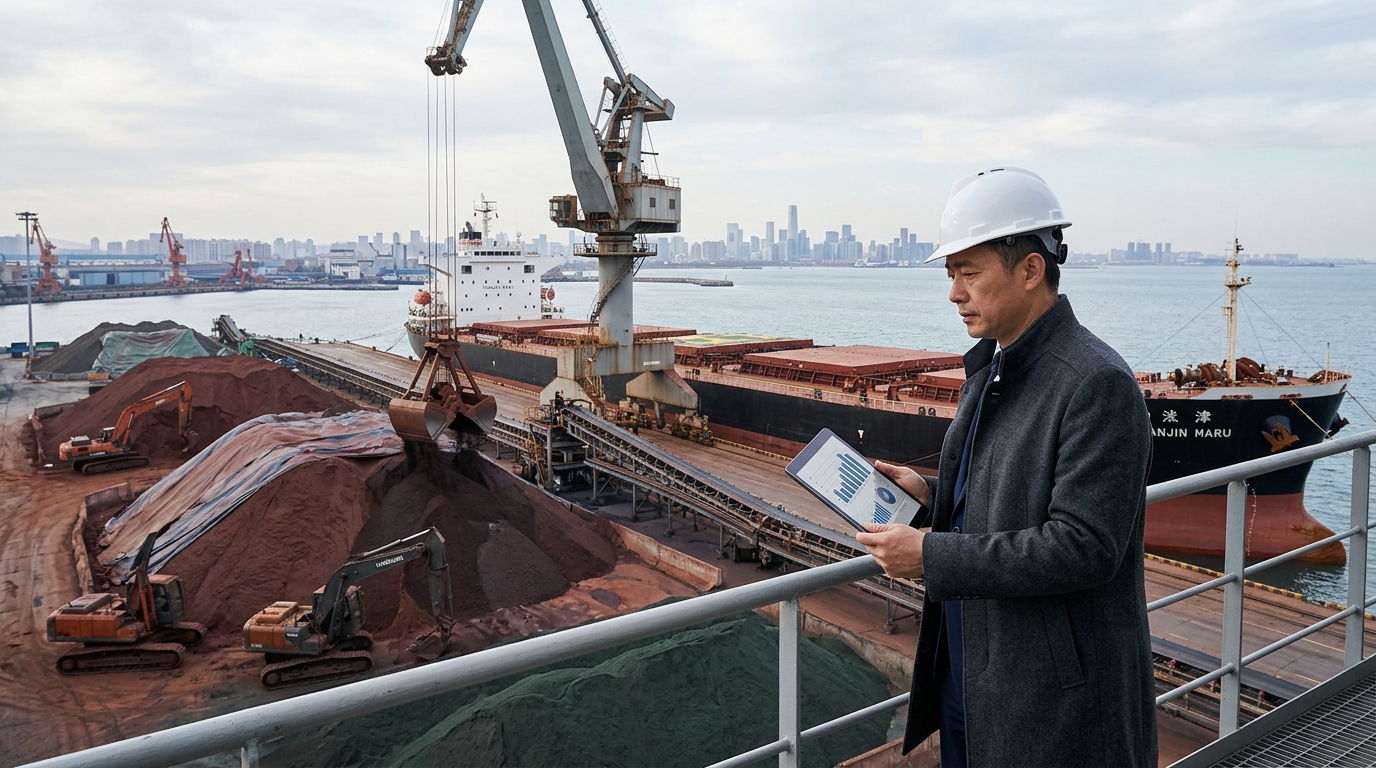
BHP sits directly in the crossfire. In fiscal 2026, BHP reported revenue of about $58.8 billion, with copper revenue about $29.0 billion and iron ore revenue about $23.9 billion. BHP’s filings also show China as its largest end-market at roughly $34.2 billion of revenue in FY2026, about 58% of the group total. The implication for positioning is straightforward: if iron ore drifts toward the low-$90s or lower, the drag can offset part of the copper upside traders expect from the electrification and data-center capex theme.
On the consumer side, Alibaba, JD.com, and PDD remain tethered to the same problem the October retail sales number quantifies: demand is fragile and heavily policy-dependent. A widely circulated October 2026 market note highlighted that JD’s inventory-and-logistics model corresponded with a smaller year-to-date drawdown (around 9% at the time), while Alibaba and PDD were down by roughly the low-30% range. A 0.4% retail sales print does not break that linkage, it reinforces it.
Technical / Trading Framework
The divergence between copper and iron ore remains the structural trade. Copper around $6.01/lb is roughly 8% below its one-month high and still about 20% higher year over year by commonly cited market pricing measures, pulled lower recently by a stronger dollar and uncertainty around China’s demand impulse. That keeps the focus on levels and catalysts: copper is sensitive to U.S. dollar swings and rate expectations, while iron ore remains sensitive to China construction and steel margins.
The supply side adds another layer to that divergence. Copper’s processing economics have structurally reversed upstream, with spot TC/RCs turning deeply negative and smelter leverage collapsing.
Iron ore in the low-$90s is the zone where marginal economics start to matter. Below that area, higher-cost supply can come under pressure and curves can steepen, but the timing is not clean because demand can deteriorate faster than supply adjusts. For traders using BHP as a copper proxy, that mismatch is the core risk: you inherit iron ore beta whether you want it or not.
Scenario Modeling
Bull case: Trump and Xi agree in Shenzhen on November 19 to extend the trade truce into 2027 and signal incremental tariff relief. Beijing follows with additional property stabilization measures in December. Iron ore holds the low-$90s and defends $90; copper reclaims $6.30. China internet multiples stabilize and BABA and PDD rebound with broader risk appetite.
Base case: The truce is extended again without structural resolution. Domestic data stays soft into year-end and exports remain the main support. Iron ore trades roughly $88 to $95; copper consolidates near $6 on supply tightness; Chinese e-commerce names stay range-bound into year-end with event-risk around policy and U.S.-China headlines.
Bear case: Shenzhen talks produce no extension and tariff risk is marked down across Chinese assets. Iron ore breaks $85, triggering curtailments at the margin, but steel demand falls faster than supply. BHP tests multi-month lows. BABA, JD, and PDD see renewed outflows as macro risk overwhelms company-level fundamentals.
Active Trader Strategy Framework
Keep it tactical: treat Thursday, November 19 as a defined catalyst, and anchor exposure to observable levels rather than macro opinions. For copper, monitor $6.00 as a psychological line and $6.30 as the upside reclaim level tied to a softer dollar and improved China headline risk. For iron ore, treat $90 as the first line of defense and the mid-$80s as the failure zone where second-order impacts on miners and cyclicals can accelerate.
Policy architecture is shaping copper’s price floor as much as demand data. Section 232 tariffs and a phased U.S. copper duty framework have quietly restructured cost exposure for importers and miners alike.
For China consumer tech, the data argues against increasing exposure ahead of the Shenzhen meetings. Resolution risk is binary, and a 0.4% retail sales outcome means there is limited fundamental cushion if the headline path turns hostile. Size accordingly, use defined invalidation points, and assume gaps are possible.
Professional Conclusion
Preparation is the edge here. The October miss is quantified, and the diplomatic calendar is explicit. What remains unknown is whether November 19 produces a durable framework or another short extension. For active traders, disciplined risk management and level-based execution matter more than the temptation to forecast the outcome.