September 23, 2026
Bonus Content: Europe’s Best Growth in Two Years. The Bond Market Has Questions.
Washington Is Building. This Market Could Create a New Nasdaq Winner.
The biggest market opportunities rarely come from one product.
They emerge when a new technology begins changing several industries at once. That may be what investors are looking at now.
The global drone market is projected to reach $182.4 billion by 2033. But the defense sector is only one part of the story.
Drone technology is also expanding across public safety, medical delivery, emergency response, infrastructure and agriculture.
One little-known Nasdaq company has spent more than 25 years building across those markets.
Its business extends beyond aircraft. It also includes software, AI, sensors and professional services.
For investors, that range provides options.
The company is not dependent on one customer, one mission or one path to growth. As government and commercial adoption expand, several parts of its business could benefit.
Wall Street may still see a small drone company, but the opportunity is much broader than it looks.
Explore the Nasdaq with several ways into America’s next technology boom.
Europe’s Best Growth in Two Years. The Bond Market Has Questions.
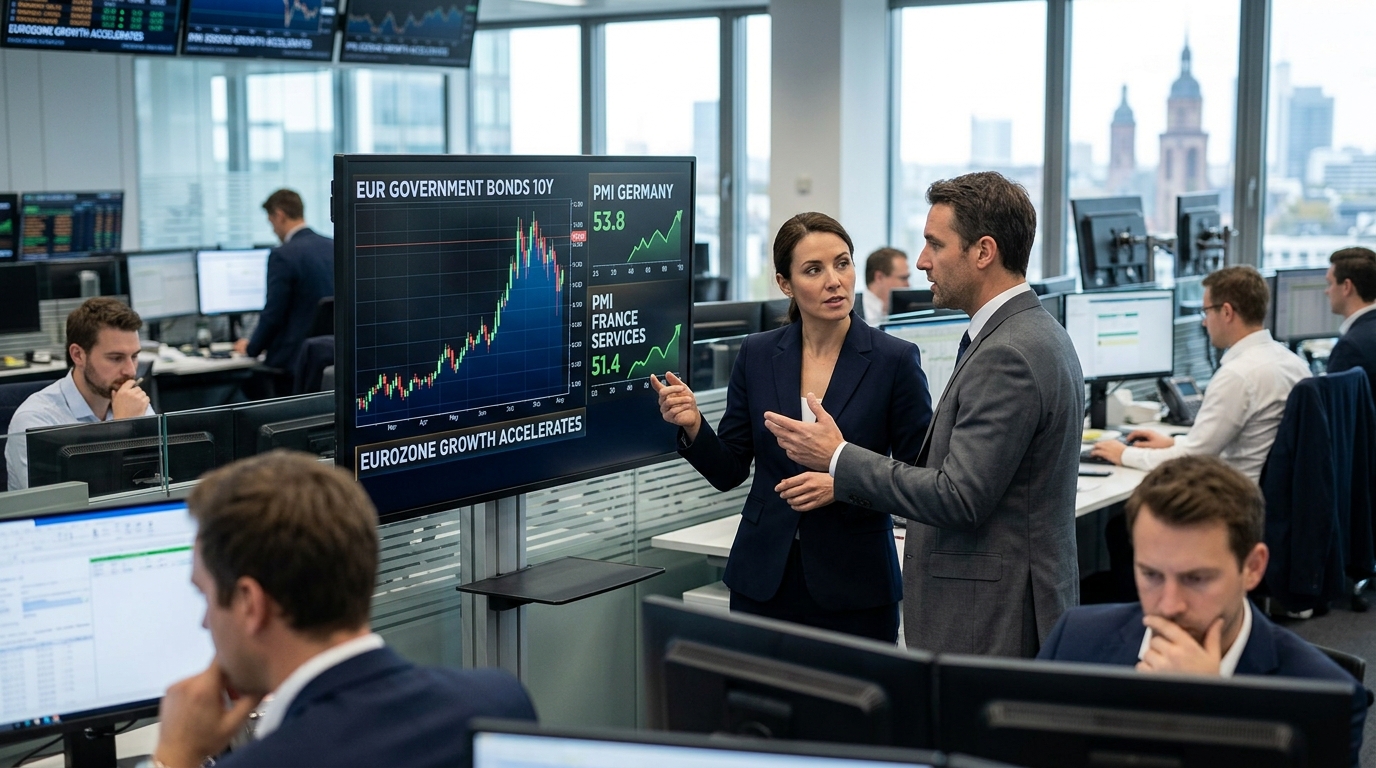
The headline figures are real and they are large. Germany’s composite PMI jumped to 53.8 in September from 51.8 in August, its highest reading since October 2025, driven by a services sector that rose to 52.9 from 49.7, reaching a seven-month high and ending a five-month sequence of contraction. France came in even more decisively: the composite output index rose to 51.2 in September from 48.5, marking a return to growth and a 25-month high, with services climbing to 51.4 from 48.0. Both prints blew past consensus by wide margins. These are not soft beats; they are regime changes in the survey data.
The context matters. The ECB raised its key deposit rate by 25 basis points to 2.5% on September 10, with the move taking effect on September 16. August euro area inflation reached 3.3%, the highest since September 2023, with energy prices up 14.3% year on year as the Iran conflict keeps crude supply constrained. September’s flash PMIs are therefore the first activity readings collected entirely after that hike, after the BoJ’s move to 1.25%, and after the Fed’s own tightening decision. The central bank cycle that markets spent months debating is now live in the data. European private sector activity accelerated anyway.
The Bond Market’s Problem
Germany’s 10-year Bund yield reversed an early rise to fall below 3.45% on Tuesday, its lowest level since September 9, as oil prices resumed their recent slide. But the structural pressure remains. Eurozone bond yields have climbed to multi-year highs in recent weeks as concerns over an energy-driven inflation shock have strengthened expectations for higher interest rates. Markets are now pricing in two ECB rate hikes in 2026, with the deposit rate seen reaching 3% by late 2027.
A PMI beat of this magnitude injects an uncomfortable variable into that rate path. Strong activity at 53.8 composite gives ECB hawks the growth cover to stay hawkish, while the ECB is already telling markets it expects the energy shock to leak into everything else through second-round effects. The combination: higher-for-longer rates against an economy that, for now, is absorbing the shock better than expected.
Sector and Equity Positioning
European equities advanced Wednesday morning, with the pan-European STOXX 600 gaining 0.4% to trade near two-week highs as softening crude oil prices, triggered by Saudi pipeline restarts and Middle East diplomatic progress, soothed corporate margin anxieties. European semiconductor-related firms such as ASML and Infineon have jumped more than 60% in 2026 and remain the dominant weight in EZU’s technology allocation. The Stoxx 600 Banks index is among the biggest gainers this year with a rally of about 23%.
EWG, the iShares MSCI Germany ETF, captures a manufacturing-heavy economy where manufacturing represents roughly 19% of German GDP versus about 12% for the US, exposing the sector to a triple headwind: direct energy cost escalation, supply chain disruption from Middle East logistics routes, and weakening export competitiveness. Today’s services rebound partially offsets that structural drag, but it does not eliminate it.
The 9:45 Catalyst
US flash PMIs land at 9:45 ET. The composite is projected to land in the mid-50s, still the most expansionary of the major economies. A miss below 54 would compress the divergence between US and European activity, potentially weighing on the dollar and shifting EUR cross rates. A beat above 56 sustains the divergence and adds fuel to the global rate-higher argument, pressuring both Bunds and Treasuries simultaneously.
Scenario Modeling
Bull Case: US PMI comes in at or above 56.0, confirming synchronized global expansion. Brent holds below $100 on diplomacy progress, relieving margin pressure for European industrials. EZU and EWG extend the morning’s gains; the Bund yield drifts toward 3.35% as the growth-inflation mix looks manageable for risk assets. DAX tests September highs.
Base Case: US PMI prints near consensus in the mid-50s. European equities hold modest gains, the Bund yield stabilizes near 3.45%, and EUR/USD trades sideways in a 1.08-1.10 range. Markets have already priced in more ECB hikes than economists project, so a moderate US read moves December odds only marginally. EZU and SPY continue their recent sideways consolidation.
Bear Case: US PMI misses sharply, below 53.5, with services weakening. The divergence between a strong European read and a softening US read triggers confusion rather than relief: bond markets question whether the global cycle is stalling, risk-off flows hit European equities disproportionately given their energy exposure, and with Brent having surged to a peak of around $120 in April before rebounding to above $100 later in the summer, any renewed crude climb above $105 reopens the margin compression trade across EWG’s industrial holdings.
Trading Framework
Watch the 9:45 release against the manufacturing and services consensus. A beat in services, the larger component, carries more weight than a manufacturing miss given the pattern seen in today’s European data. The Bund at 3.45% is the pivot: sustained movement above 3.55% on a hawkish PMI combination reactivates the pressure on rate-sensitive EZU financials, even if the headline equity index holds. Position sizing ahead of the release should reflect both the opportunity and the binary nature of the catalyst. Preparation, not prediction, is what the next 90 minutes rewards.