September 28, 2026
AI ACV crossed $1 billion in Q2 2026
Enterprise software is mid-rotation. The specific tools gutting back-office administrative pipelines are no longer prototypes, and the revenue attached to them is no longer rounding error. ServiceNow is the clearest example of what that transition looks like when it actually works.
In at 9:35 AM. Out by 10.
I call it the “Opening Bell Breakout.” It’s the same setup I used to catch moves like 113% on GOOGL and 240% on META. I trade one simple 15-minute window each morning – and I’m usually done by 10 AM.
- ServiceNow Q2 2026: total revenue $3.987B, +24% YoY; subscription revenue $3.877B, +24.5%
- AI annual contract value crossed $1B in Q2 2026, up more than 40% quarter over quarter
- Agentic AI production deployments grew ninefold over nine months; first-time agentic buyers up 45% YoY
- 123 transactions over $1M in net new ACV in Q2, up nearly 40% YoY; 658 customers above $5M ACV
- Full-year 2026 subscription revenue guidance raised to $15.76–$15.78B; AI ACV target lifted to $1.5B
- NOW stock sits roughly 30% below its 52-week high of $194.73; trailing PE near 84
- UiPath ARR at $1.901B, +12% YoY; 16 of its top 20 deals in the latest quarter included AI products
Where the Automation Money Is Actually Going
The 10-year yield hovering above 4.5% is compressing multiples across growth software. That creates the surface-level reason NOW is down. The less-examined question is what the business itself is doing while the stock retreats.
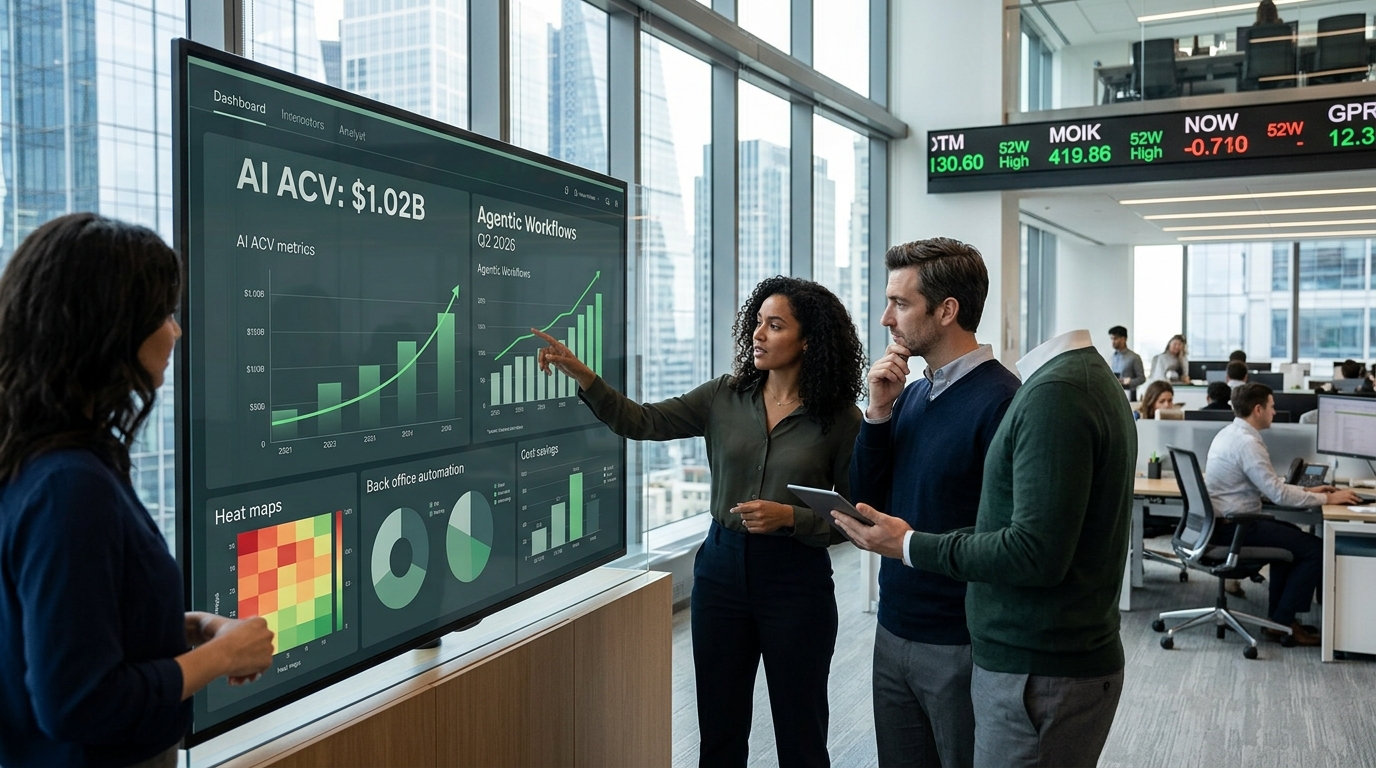
AI ACV crossed $1 billion for the first time in Q2 2026, up more than 40% quarter over quarter, while agentic AI production deployments grew ninefold over nine months and first-time agentic buyers were up 45% year over year. These are closed contracts, not pipeline projections.
The back-office angle is specific. ServiceNow’s HR Service Delivery product automates routine HR tasks including onboarding, leave management, transfers, offboarding, and career development, allowing employees to access information efficiently and enabling HR teams to shift from administrative tasks toward strategic priorities. The internal savings case is equally concrete: ServiceNow’s CFO walked through the math at Financial Analyst Day, noting that a team of 20 support analysts costs over $1 million annually with roughly 90% in labor, and that autonomous agents can resolve 75% of that team’s work, cutting the customer’s total cost by 65% while freed-up seat licenses convert into AI agent consumption at 6.5 times the value.
In 2026, ServiceNow expects $200 million in incremental OpEx savings, for a total of $300 million in hard cost reductions flowing to the bottom line, while maintaining flat headcount for the full year. That is not a soft productivity claim; it is a number the CFO put in front of analysts in May.
A 96% win rate using this strange trading approach
There’s a way to profit from the AI boom that has nothing to do with picking stocks.
Wall Street legend Larry Benedict calls it “AI Profit Loops.”
This pattern hits the market every 90 days. Over the last five years, it has come around 23 times.
In 22 of them, Larry handed his members multiple winning trades. That’s a 96% win rate, and the next “Loop” is due to hit on December 8.
Watch this presentation to learn how to get positioned today.
The Competing Platform: UiPath
UiPath is chasing the same back-office queue from the robotic process automation side. CEO Daniel Dines reported annual recurring revenue growing at a 12% clip to reach $1.901 billion, and management has emphasized that customers are moving agentic products from pilot to production. The deal mix confirms that trajectory: 16 of UiPath’s top 20 deals in the latest quarter included AI products.
The competitive split matters for positioning. ServiceNow owns the workflow layer inside large enterprises, the system of record that HR, IT, and security already run on. UiPath owns the execution layer for individual task automation. Both are expanding toward each other, but ServiceNow’s roughly $29 billion RPO base and 98% renewal rate give it a stickier revenue floor.
Valuation and Technical Context
The stock now sits at roughly 30% below its 52-week high of $194.73. Trailing P/E is roughly in the mid-80s based on the latest tape, and third-party estimates of forward P/E vary by source and methodology.
The 200-day moving average sits well above the current price. Resistance around the $150 level held through the July earnings run-up and remains the near-term ceiling. A close above $150 on volume meaningfully above the 20-day average would signal institutional re-engagement. Support near $125 aligns with the June trough. Q3 earnings arrive late October and carry the next catalyst.
Scenario Modeling
Bull Case ($175+): Q3 subscription revenue beats the $3.975–$3.980B guidance range; AI ACV trajectory toward $1.5B remains on track; macro rates stabilize, compressing the discount rate applied to outer-year earnings. The long-term target of $30 billion-plus in subscription revenues with 30% of ACV from AI and a Rule of 60+ by 2030 starts to get priced in incrementally.
A bet that doesn’t fit the pattern
A wealth manager overseeing $31.7 billion owns hundreds of stocks, mostly the names you’d expect.
Then there’s one exception: a small industrial company they’ve poured roughly $705 million into. The position is so large they must disclose every move. Their latest filing wasn’t a sale.
They bought more.
Base Case ($130–$150): Revenue growth holds near 20–22% through Q4 but valuation multiples stay compressed while rates remain elevated. The AI ACV story builds credibility quarter by quarter without triggering a re-rating. NOW drifts sideways into year-end, consolidating above the June low.
Bear Case (sub-$120): Macro deterioration accelerates SaaS spending freezes at enterprise clients; Now Assist upsell cycles lengthen; a Q3 miss on cRPO growth reignites concerns about AI displacing seat-based software revenue rather than adding to it. The FX headwind flagged for Q3 becomes a larger-than-expected drag.
Active Trader Framework
Traders sizing into NOW should distinguish between two separate risks: business execution risk, which the data suggest is low, and multiple re-rating risk, which is purely a function of the rate environment. Keeping position size proportional to that distinction is the discipline the trade requires. Earnings late October are the binary event; implied volatility will expand into that window, making defined-risk structures worth considering over outright long exposure. UiPath (PATH) offers a lower-multiple, higher-beta expression of the same agentic automation theme with a trailing P/E near 19 and ARR growth holding in the low teens.
The back-office automation trade is no longer a thesis about what might happen. The contracts are signed. The agents are in production. The question active traders need to answer is whether the current price reflects that, and by most measures, it does not.