There are two kinds of losses in trading.
The first kind is a surprise – the news nobody saw coming, the move nobody predicted. Those losses are the cost of doing business. Every trader takes them. No shame in it.
The second kind is different. The second kind was announced in advance. Published on a schedule. Posted for free where anyone could see it – sometimes a full year ahead of time.
Losing to the first kind is trading. Losing to the second kind is stepping on a landmine that had a sign next to it.
There are 4 of these scheduled events that do most of the damage to beginner options trades. My new report names all four, explains exactly why each one detonates options positions, and gives you the 5-minute check that avoids every one of them.
The Options Landmine Calendar. Normally $29.97. Free today.
Good Trading,
Bill Poulos
P.S. You can’t eliminate surprise from the market. But you can absolutely eliminate losing to a schedule. Get the calendar free.
France’s Debt Gap Over Germany Just Hit Its Widest Since 2012
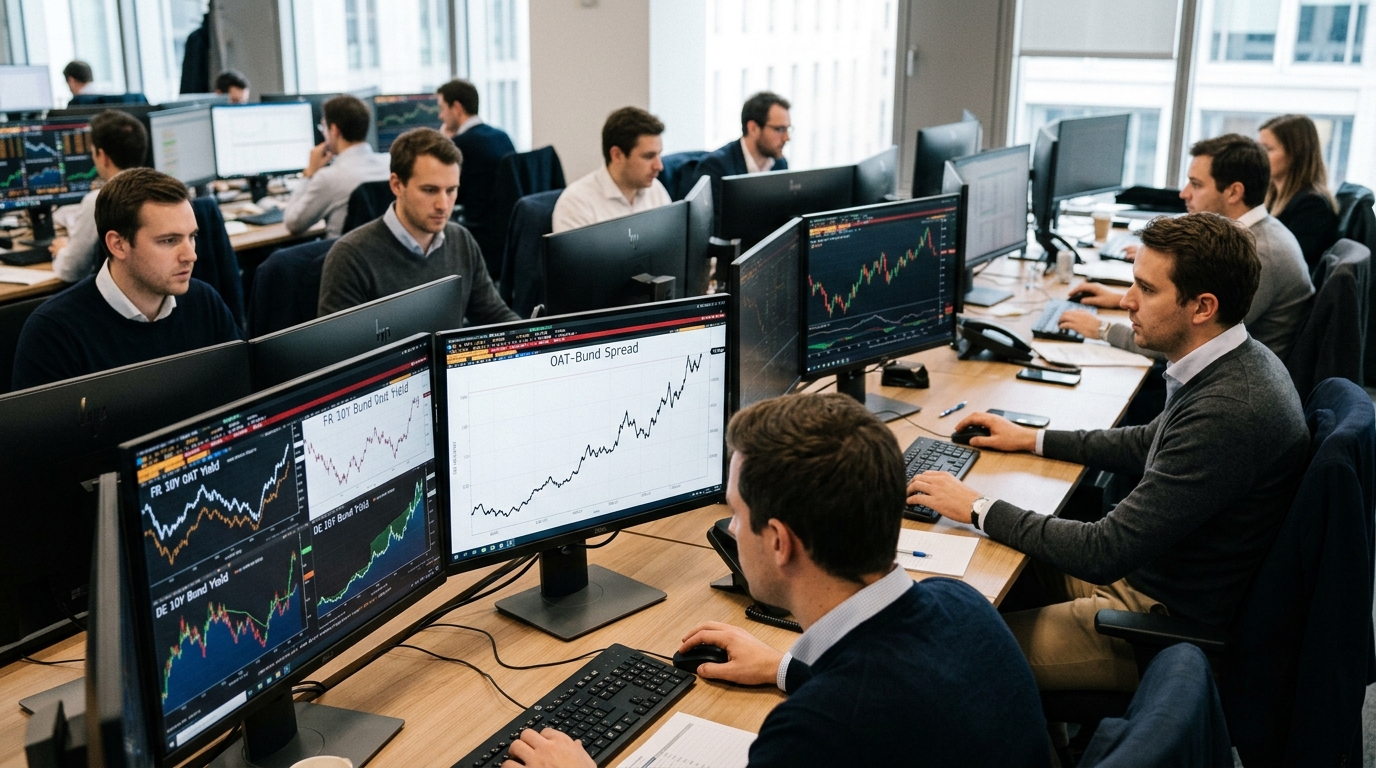
The OAT-Bund spread closed Monday at levels not seen since the height of the eurozone sovereign debt crisis. French 10-year yields surged to an 18-year high in September 2026, driving the yield spread between French OATs and German Bunds to about 1.05 percentage points, its widest margin since the 2010–2012 eurozone sovereign debt crisis. By late last week, the spread had pushed further, with the 10-year OAT trading more than 110bp over Bunds. The assignment for traders this week is not to chase France. It is to trade the core rates regime that France’s collapse is exposing.
Market Context
The French 10-year OAT yield rose to about 4.75% on September 28, 2026, touching its highest level since mid-2008, as elevated energy prices fuel renewed inflationary concerns and hawkish central bank signals lift rate expectations. That move does not exist in isolation. The US 10-year Treasury yield has been trading around 5.2%, after pushing to the highest levels since 2007 in recent sessions as oil-price volatility and tighter financial conditions hit duration. Duration is under assault on both sides of the Atlantic simultaneously.
The French story has a distinctly domestic dimension layered on top of that global selloff. The move is driven by a widening budget deficit, persistent political fragmentation, and a roughly €54 billion adjustment plan, with investors on high alert as France heads into a contentious 2027 budget season. France’s finance ministry has put 2026 public debt at 119.3% of GDP and the deficit at 5.4%. According to the government, the deficit could reach about 6.5% of GDP without corrective measures, while debt-servicing costs are expected to keep rising into 2027.
Sector and Stock Breakdown
French financials bear the heaviest cross-asset exposure to this reset. BNP Paribas reported 2025 revenue of €51.22 billion and carries a market capitalization near €127 billion. The bank hit a 13% Common Equity Tier 1 threshold ahead of its own timetable, providing a capital buffer, but sovereign bond holdings and domestic loan books tie it directly to OAT volatility. French banks, including BNP Paribas, fell close to 4–5% in a single session earlier in late August amid domestic political uncertainty, illustrating how quickly risk premiums translate into equity drawdowns.
AXA, one of Europe’s largest insurers, holds a large sovereign bond portfolio with meaningful exposure to French government debt. Rising OAT yields mechanically compress the mark-to-market value of those holdings. A European rates strategist at HSBC flagged that the move in the OAT-Bund spread was larger than expected, and noted that the rise in non-domestic ownership of OATs raises questions about where swing buyers will emerge and at what price.
The comparison to Italy, which spent years trading at wide spreads to Germany during the worst of the 2010s crisis, is now being made openly by analysts. That framing needs discipline: France is not Italy, and daily cross-country comparisons can flip quickly as relative growth, fiscal headlines, and supply calendars change. The structural shift is that France is no longer being treated as an unquestioned core proxy, and that is what feeds CAC 40 underperformance when political risk spikes.
Technical Framework
The OAT-Bund gap started 2026 materially tighter than where it sits now and was significantly tighter into late June. The move from the summer lows to above 110bp in roughly three months is not routine widening: it is a trend break. On the US side, the 10-year around 5.2% is above the 5.0% level that capped yields through most of 2024 and early 2025. Resistance is thin above here, with the next credible structural level near 5.40–5.50%, the range last visited in 2007. For OATs, the 2012 crisis peak was roughly 150bp over Bunds. Above 110bp, the market has room to move further if the budget impasse deepens.
Scenario Modeling
- Bull Case: Prime Minister Sébastien Lecornu secures parliamentary support for the roughly €54 billion plan without invoking Article 49.3, reducing the risk of a government collapse. OAT-Bund spread retraces toward 85–90bp. The US 10-year stabilizes below 5.2% on softer PCE data. French bank stocks recover 5–8% from current levels. CAC 40 reclaims 8,200.
- Base Case: The budget passes via constitutional maneuver but faces a no-confidence challenge, keeping political risk elevated. The OAT-Bund spread oscillates between 100–115bp. US 10-year holds 5.15–5.35%. French financials remain under pressure, with BNP Paribas and Société Générale trading at a discount to European peers.
- Bear Case: A no-confidence vote topples Lecornu before the 2027 budget is passed. The ECB’s Transmission Protection Instrument is theoretically available, but its design includes fiscal- and macro-eligibility conditions that can become politically and procedurally complex for a country under heavy fiscal scrutiny. OAT-Bund spread extends toward 130–150bp. US 10-year approaches 5.50%. Société Générale and AXA each sell off 10% or more.
Active Trader Strategy Framework
The editorial angle is clear: trade the core, not the periphery. Shorting Bunds into strength, or expressing US duration risk via Treasury futures, positions around a global rate environment that France is amplifying rather than creating. Direct OAT shorts carry ECB backstop risk. HSBC has noted the ECB would likely only intervene if market moves became disorderly. That threshold is ambiguous, which makes direct OAT positioning asymmetric and difficult to size.
For equity traders, French bank exposure warrants tight stops. On sovereign ratings, the clean way to frame it is: France is no longer rated AA across the board, and its outlooks are not uniformly positive. As of late May 2026, Standard & Poor’s rates France A+ with a stable outlook, while Moody’s rates it Aa3 with a negative outlook. Negative credit momentum in a rising-rate environment is a combination that compresses bank multiples. Monitor OAT-Bund spread daily as the primary leading indicator for CAC 40 financial sector direction.
Conclusion
This is not a replay of 2012. France has the euro, institutional depth, and a government actively attempting adjustment. What it lacks is a parliamentary majority willing to absorb the pain of a roughly €54 billion correction. That tension between fiscal necessity and political fragility defines the risk here. For active traders, the discipline is in reading the spread as a macro signal for core rates positioning, not as a trigger for speculative OAT shorts. Preparation, defined levels, and calibrated size matter more than conviction calls this week.