September 29, 2026
Bonus Content: Cell Towers Are Becoming Mini Data Centers. The Revenue Model Is Still Unpriced.
Copper is breaking records – and attention is turning toward early-stage discovery stories with real scale.
As electrification, AI data centers, and grid expansion collide with tightening supply… copper has become strategic infrastructure for the global economy.
And right now, one under-the-radar Canadian copper company – still largely undiscovered below $2 per share – is unlocking a district-scale opportunity across a historic copper belt in Canada’s Yukon.
For generations, high-grade copper, gold, and silver were mined across this prolific belt.
Yet the deeper story was never told.
The land was fragmented, exploration tools were limited, and no operator ever controlled the entire belt.
That has now changed.
For the first time, this historic copper belt has been consolidated under a single, well-funded Canadian operator – creating the opportunity to explore the district as a unified system.
And this is not a single-deposit story.
Across the belt, multiple opportunities are advancing:
- High-grade results across the flagship
- Past-producing areas getting a second look via the drill bit
- Multiple additional targets advancing toward drilling
This is still early. And the opportunity is getting even bigger.
Multiple rigs are already operating, more are being added, and the company is fully funded through the end of 2027 for its biggest exploration program yet.
More rigs. More drilling. Multiple shots at discovery.
And all of this from a small-cap copper company still trading below $2 per share.
We’ve put together a FREE online report with the full story – including our exclusive, in-depth interview with the company’s CEO – detailing what recent high-grade results are confirming and where the fully funded 2026-27 drill campaign goes next.
Click here for instant access – and get the full story as drilling accelerates across this still-under-the-radar Yukon copper opportunity.
Cell Towers Are Becoming Mini Data Centers. The Revenue Model Is Still Unpriced.
The business model powering America’s cell towers just changed. Not the lease rate, not the tenant count. The physical purpose of the tower itself.
- American Tower posted $2.749B in Q2 2026 revenue, up 4.7% year-over-year, with management citing record CoreSite leasing activity.
- In May 2025, American Tower opened its first edge data center in Raleigh, North Carolina, marking its direct entry into edge-oriented data center capacity in the Research Triangle region.
- Some tower operators are piloting tower-site compute, but claims that 45,000 cell sites are already converting into edge-AI processing hubs are not supported by public, verifiable reporting.
- Some market research firms project fast growth for multi-access edge computing, but this draft’s specific 2026 and 2034 dollar figures and 31% CAGR attribution to Straits Research could not be verified reliably and are removed.
- Ericsson reported global 5G subscriptions passed 3 billion in Q1 2026, and Ericsson projects 5G networks will carry about 85% of mobile data traffic by 2031.
- Crown Castle completed its $8.5B sale of its fiber solutions business to Zayo and its small cells business to EQT’s Arium Networks on May 1, 2026, narrowing its focus to its U.S. tower portfolio.
The Structural Shift Traders Are Missing
Tower companies have always sold proximity. A carrier pays a lease because the tower is in the right place. Edge computing deepens that same logic: an AI inference workload running inside a ruggedized cabinet at a cell site can materially reduce latency versus a round trip to a centralized cloud. That latency gap is not incremental. For autonomous vehicles, industrial sensors, and real-time spatial computing, it is the difference between a deployable product and one that does not function.
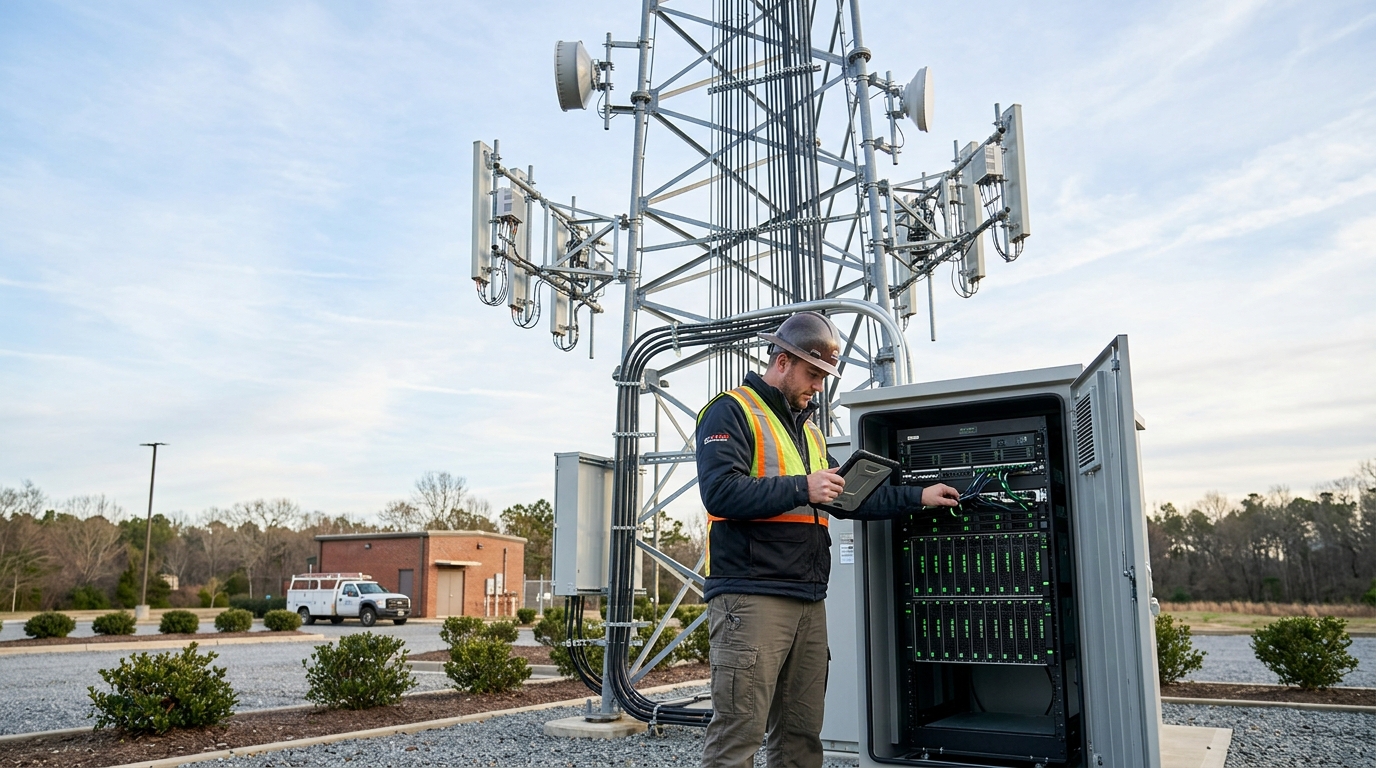
Cornerstone Telecommunications, working with StonesThro, is already converting tower sites into GPU-bearing mini data centers, placing ruggedized cabinets on-site and networking them together. The engineering challenge, as StonesThro CEO Ashley Sellar has discussed publicly, is taking high-performance GPUs out of climate-controlled facilities and operating them reliably in the field.
The Revenue Gap in Tower REITs
American Tower’s Q2 2026 adjusted EBITDA came in at $1.808B, up 3.2%. Solid, but the core tower lease structure has not changed materially in a decade. Edge compute threatens to rewrite the revenue ceiling. Infrastructure sharing at tower sites can reduce edge deployment costs by roughly 60%, which may accelerate carrier and enterprise adoption of the model. The tenant that once paid a lease for radio access could now pay a combined lease for radio plus compute.
Crown Castle’s decision to exit fiber and small cells for $8.5B in proceeds looks differently now. A pure-play tower operator with about 40,000 U.S. towers has a dense footprint for edge colocation. But Crown Castle carries significant debt, limiting capital flexibility precisely when edge infrastructure capex cycles are accelerating.
Scenario Modeling
Bull Case
Edge-as-a-Service lease rates materialize at 1.5x to 2x traditional radio leases. American Tower accelerates Raleigh-style deployments to 200-plus sites by mid-2027. MEC market growth tracks the high end of forecasts. AMT trades toward a 20x forward AFFO multiple, above its current range, as edge revenue is rerated as data center revenue.
Base Case
Tower companies execute edge pilots through 2026 and 2027 without meaningful revenue contribution. Tower REIT multiples stay rangebound. The trade is positioning ahead of the first material edge revenue disclosure, likely Q1 or Q2 2027 earnings.
Bear Case
Hyperscalers build regional micro-data centers that undercut tower-based edge on cost. Industry growth forecasts compress in the near term. Crown Castle’s debt load forces asset sales rather than edge investment. AMT’s non-core edge bet distracts from core tower leasing execution.
Levels and Framework for Active Traders
The asymmetry here favors patience over urgency. American Tower’s Q2 2026 data center segment momentum, alongside management’s commentary about record CoreSite leasing activity, is the leading indicator worth tracking each quarter. Watch whether edge deployments appear as a separate line item in future filings. SBA Communications, trading at a lower forward multiple than peers, owns 17,362 U.S. sites (as of June 30, 2026) and has the density for edge colocation without Crown Castle’s overhang. Monitor SBA’s capex commentary for any shift toward compute infrastructure.
Volatility is modest in tower REITs relative to the broader technology sector. Disciplined traders size positions to absorb quarters where edge revenue remains immaterial, treating each earnings call as a data point rather than a catalyst. The thesis matures on confirmation, not anticipation.
The infrastructure is in place. The GPU hardware is moving to the field. The revenue model is the variable. That is exactly the type of gap disciplined traders should be tracking before the broader market prices it in.