October 5, 2026
Bonus Content: Enterprise Software Bills Are Becoming Unpredictable. Here Is Who Profits.
Washington Wants the Next Drone Boom Built in America
America wants to dominate the next great weapons market.
For generations, military strength was measured by the size of a nation’s ships, tanks and aircraft. But the next era may belong to something smaller, faster and more intelligent: Drones.
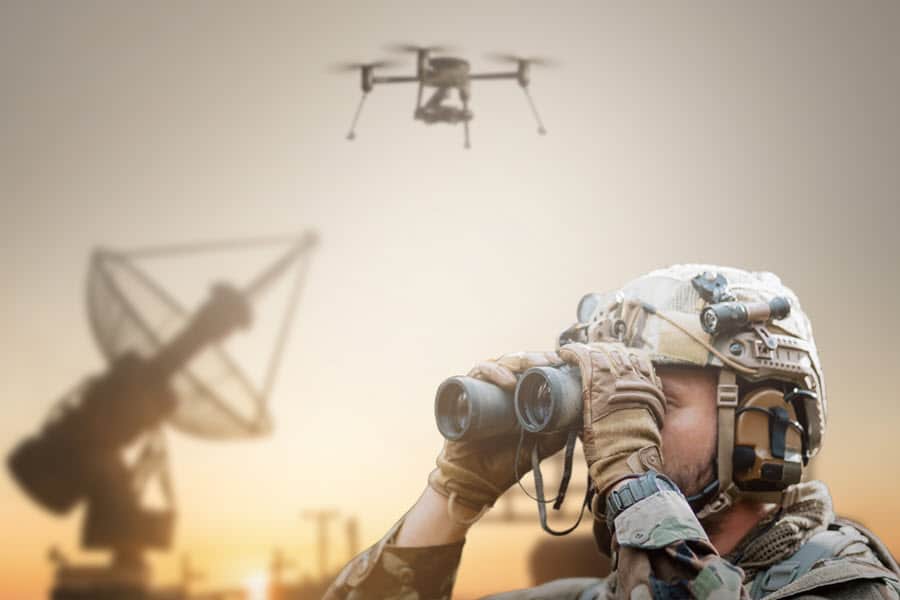
Drones can gather intelligence, move critical supplies and complete missions without putting pilots at risk.
And Washington is moving to bring that industry home. A new Executive Order calls for expanded domestic production, secure supply chains and greater military adoption of American-made drones.
The global drone market was valued at $83.8 billion in 2025 and is projected to reach $182.4 billion by 2033. A nearly 120% increase!
North America already accounts for more than 40% of that market. Yet one Chinese company still controls roughly 70% of the U.S. civilian drone market.
Washington wants to change that.
And with the Pentagon reportedly seeking around 300,000 drones, investors may want to know which American companies could benefit.
One little-known Nasdaq company has spent more than 25 years developing professional drone technology. It has patents, a broad product lineup and real-world deployments behind it.
If America leads the next drone revolution, this overlooked company may finally get Wall Street’s attention.
Enterprise Software Bills Are Becoming Unpredictable. Here Is Who Profits.
The CFO’s annual software budget is built on one assumption: a predictable seat count multiplied by a fixed monthly rate. That assumption is breaking in real time, and the financial consequences are already showing up in vendor earnings.
The mechanism is straightforward. Per-seat pricing is weakening because AI features and agents reintroduce meaningful variable compute costs into software economics. When an AI agent can complete hundreds of tasks without a human logging in, the seat becomes a weak billing unit. AI automation allows companies to shrink teams while simultaneously increasing their consumption of software utility. The vendor charging per seat loses revenue as headcount falls. The vendor charging per token, per action, or per compute minute captures the upside.
Where the Money Is Going
Snowflake and Databricks are the clearest proof. Both run pure consumption models, and both are accelerating. Snowflake reported product revenue of $1.23 billion in Q4 fiscal 2026, representing 30% year-over-year growth, with a net revenue retention rate of 125%. Databricks said it delivered more than 65% year-over-year growth in its Q4 and crossed a $5.4 billion revenue run-rate.
Salesforce is running the same playbook inside a legacy seat structure. Unlike per-seat license models, Agentforce pricing includes consumption-based options, including Flex Credits as a usage currency. Agentforce annual recurring revenue exceeded $1.5 billion in the quarter reported August 26, 2026, up over 240% year over year. Microsoft moved faster still: Copilot Cowork is generally available, and pay-as-you-go billing is priced at $0.01 per Copilot Credit, shifting more agentic usage from predictable per-seat spend toward a variable charge that scales with use.
The CFO Problem
When a single Copilot Cowork session or a Claude API call carries a variable cost, the CFO’s budget assumption from January may not survive July. Microsoft’s $0.01-per-credit structure sounds low in isolation; multiplied across thousands of employees and dozens of workflows, it becomes a material line item that most enterprise finance teams have not instrumented.
A single application can now generate cost from the seat license, from AI credit consumption, from API call volume, and from storage or compute overages. That is not a pricing trend. It is a contract-level financial event arriving at every enterprise renewal cycle.
Hybrid pricing is increasingly common in enterprise software in 2026. The hybrid structure, a fixed platform floor layered with a metered consumption tier, is gaining share precisely because enterprise CFOs dislike pure variable costs; they cannot budget for a number that fluctuates.
Trading the Transition
The vendors best positioned are those whose consumption growth exceeds churn risk on legacy seats. Snowflake’s remaining performance obligations of $9.77 billion, up 42% year-over-year, signal committed future consumption, not just current spend. Usage-based pricing adoption is also broadening across SaaS, and benchmarks commonly show faster growth for companies with a meaningful usage-based component versus pure seat-based models.
The risk sits on the buy side. Enterprises without real-time consumption monitoring are flying blind into budget overruns. Organizations that implement governance early will be best positioned to capture AI’s value without losing control of costs. That governance gap is itself a product opportunity, and several monitoring platforms are capturing it. The billing model transition is not theoretical. It is reshaping enterprise software contracts right now, renewal by renewal.