October 7, 2026
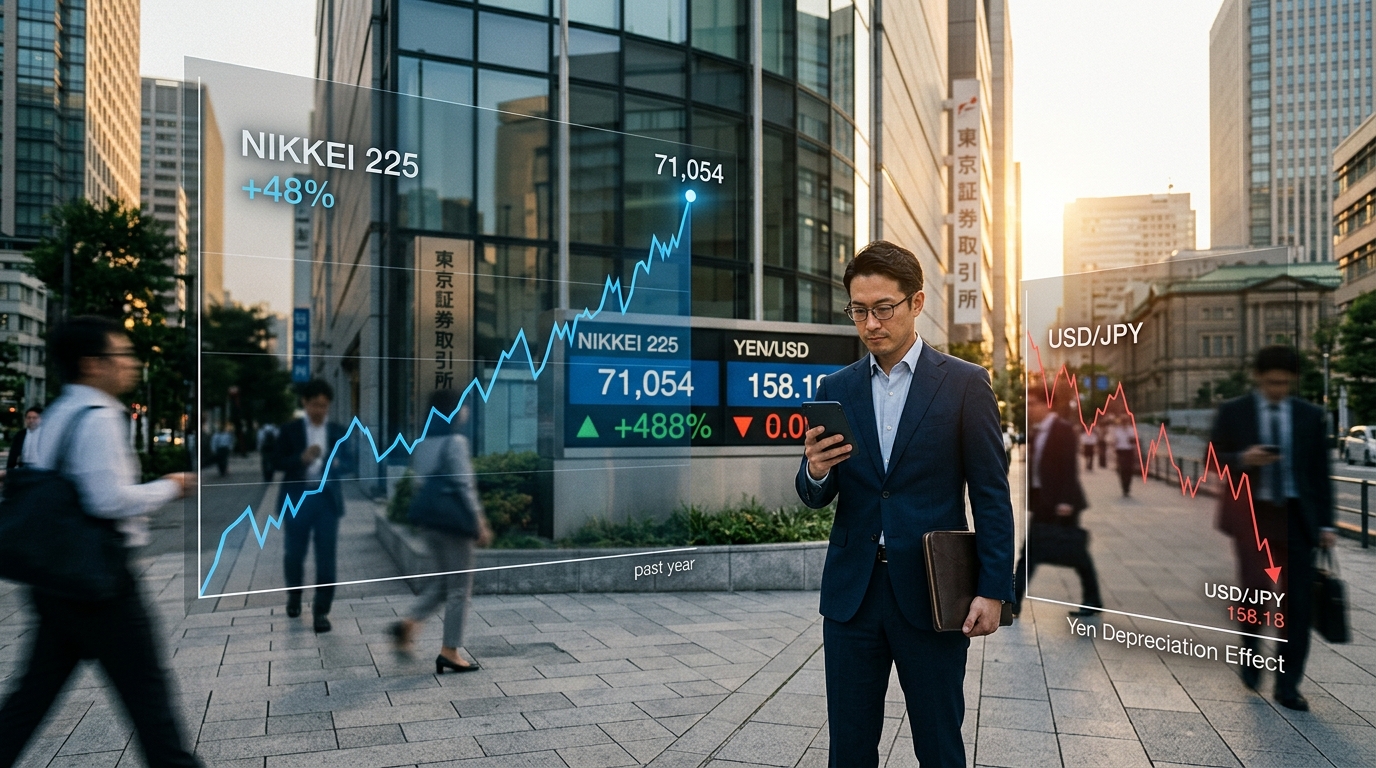
Bonus Content: Japan Is Up 48% in a Year. The Yen Has Eaten Part of That Gain.
Pentagon Wants 300,000 Drones. Which U.S. Companies Are Ready?
Investors follow the numbers. And right now, the drone market is telling a story that is getting difficult to ignore.
The global market was valued at $83.8 billion in 2025 and is projected to reach $182.4 billion by 2033. North America already accounts for more than 40% of it.
Those are the market numbers…
Now follow Washington’s numbers…
The Pentagon wants around 300,000 drones while a new Executive Order aims to prioritize domestic manufacturing, secure supply chains and wider adoption of American made systems.
Put those figures together and this opportunity starts to come into focus.
Making this Nasdaq drone manufacturer intriguing; as it has spent more than 25 years developing a patented technology.
This growing patent portfolio helps secure that position as demand expands.
As more of the world’s drone spending flows toward American companies, this unnoticed, Nasdaq may gain attention quickly.
Japan Is Up 48% in a Year. The Yen Has Eaten Part of That Gain.
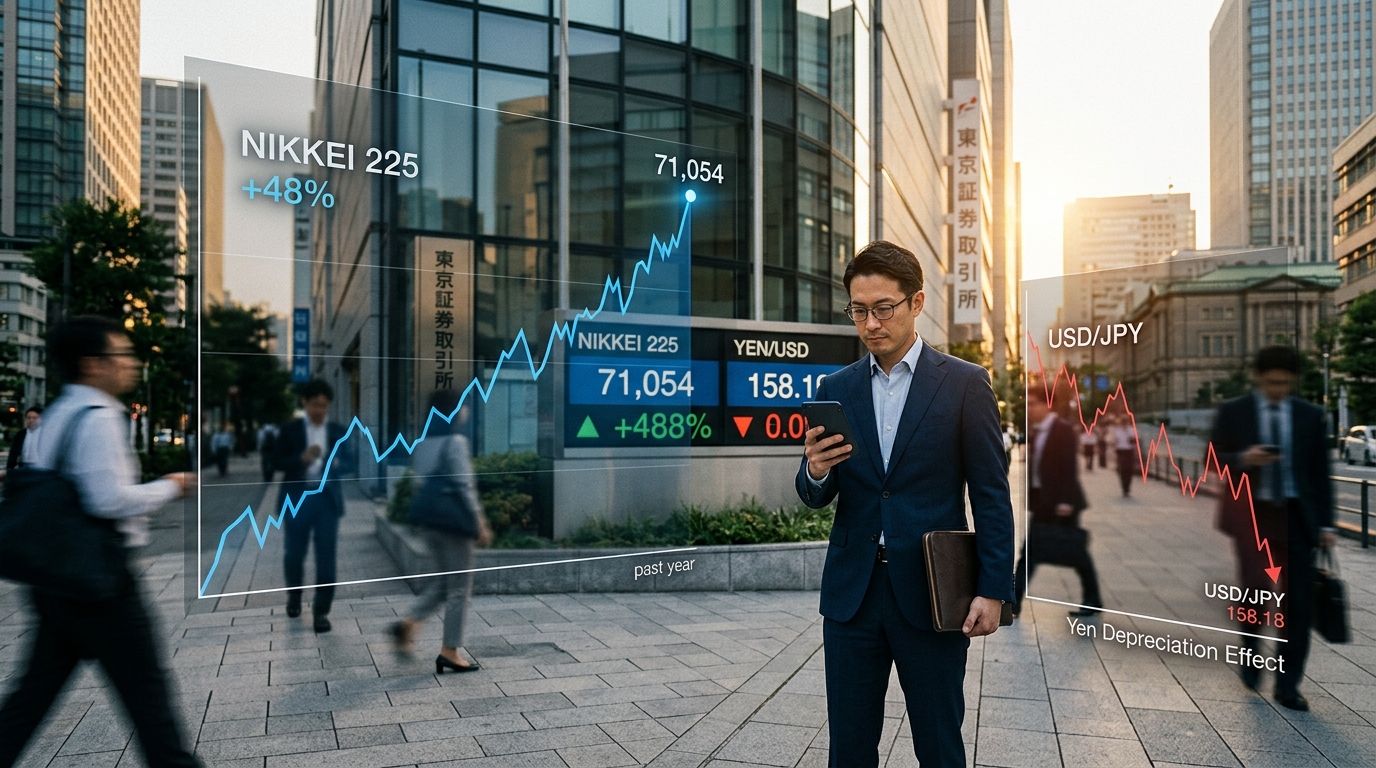
The Nikkei 225 closed at 71,054 on Tuesday, October 6, up 1.58% on the session and 48% over the trailing twelve months. For a trader sitting in Tokyo, that is an extraordinary run. For a dollar-based investor holding unhedged Japanese equities, it is something more complicated: a 48% yen-denominated gain that has been partially clawed back by a currency that has weakened 4.13% against the dollar over the same period, and another 2.47% in the past month alone. USD/JPY sat at 158.18 as of Tuesday’s close.
- Nikkei 225 at 71,054, +1.58% on October 6; +48.18% year-on-year
- USD/JPY at 158.18; yen down 2.47% over one month, 4.13% over one year
- BOJ policy rate at 1.25% after September 18 hike, highest since 1995
- Market-implied probability of BOJ hold at the Oct. 29-30 meeting: 83%
- EWJ (unhedged) up roughly 24% over one year; DXJ (currency-hedged) up roughly 45%
- 30-year JGB yield hit a record 4.235% on October 6 on fiscal concerns
- AI-linked names led Tuesday’s advance: Taiyo Yuden +6.58%, TDK +5.60%, Fujikura +4.85%
The Currency Gap Is the Trade
The Nikkei’s surge to 71,054 was driven by the same AI-related component names that have dominated the index all year. Taiyo Yuden and TDK signed a memorandum of understanding on September 29 to jointly develop multilayer ceramic capacitors and inductors for AI data centers, a move that reflects the broader theme: Japan’s electronics supply chain is a direct beneficiary of global AI capital spending. That is the bull case for the equity side.
The currency side is where the decision lives. A dollar investor in EWJ, the iShares MSCI Japan ETF, has returned roughly 24% over the past year. An investor in DXJ, the WisdomTree Japan Hedged Equity Fund, which neutralizes the USD/JPY drag through a rolling currency hedge, has returned closer to 45%. That 21-point gap is the yen’s cost, priced in real returns.
What the BOJ Has and Has Not Said
The BOJ raised its policy rate to 1.25% on September 18 in a 7-2 vote, the second hike of 2026. Governor Ueda spoke at the National Securities Convention in Tokyo on October 6 and gave markets nothing to work with on October timing. He reiterated that the BOJ will continue raising rates in line with economic and price developments, but offered no signal of acceleration. USD/JPY dipped briefly toward 157.50 on the remarks and recovered above 158.00 within the same session.
Three-month TONA futures currently price an 83% probability of no change at the Oct. 29-30 meeting. That is a meaningful shift: just a week ago, the hold odds stood at 30%. The September US payrolls figure of 29,000, far below the 84,000 consensus, removed a Federal Reserve hike from October’s table and simultaneously reduced the urgency for the BOJ to match with its own move.
Former BOJ executive director Kazuo Momma put October hike odds at 20% to 30% when he spoke to Bloomberg on September 27. Overnight-rate futures are now closer to 17%. The gap between those estimates reflects the payrolls shock, not a change in BOJ intent.
Scenario Modeling
Bull Case
The BOJ holds as expected. AI-linked names continue to benefit from global semiconductor demand. USD/JPY drifts toward 157, not 155, because the interest rate differential between Japan at 1.25% and the US at 3.75%-4.00% remains wide. The Nikkei retests its June 2026 all-time high of 73,007. DXJ outperforms EWJ as the hedge provides a cleaner capture of the equity gain.
Base Case
The BOJ holds and the Outlook Report signals a December hike at the current pace of roughly one move per quarter. USD/JPY trades in a 156-160 range through month-end. The Nikkei consolidates in the 69,000-72,000 zone. The hedging decision for EWJ holders becomes a question of time horizon: those with a horizon inside six months favor adding DXJ exposure; those with a longer view accept the currency drag as a secondary risk.
Bear Case
The BOJ surprises with a 25-basis-point hike or publishes language suggesting faster tightening. USD/JPY breaks below 155 in a move similar to the yen’s post-June volatility, when the pair reached 157 within a week of that hike. Unhedged Japan equity positions take a simultaneous hit from currency translation and potential multiple compression. The 30-year JGB yield, already at a record 4.235%, extends higher as fiscal concerns compound the rate path.
Active Trader Framework
The core decision ahead of the late-October BOJ meeting is not whether to own Japanese equities. It is whether to own them hedged. EWJ carries roughly $23 billion in assets and trades with deep liquidity, but every dollar deployed holds embedded USD/JPY exposure. DXJ at about $7.0 billion in assets hedges that exposure at a 0.48% expense ratio, one basis point cheaper than EWJ’s 0.49%.
Key levels: USD/JPY resistance sits near 158.50, where the last three sessions have capped. Support is around 157.00, with the yen’s September low at 153.42 providing a longer-term reference. On the Nikkei, the 70,000 level served as intraday resistance for weeks before this week’s break; it now functions as near-term support. The June all-time high at 73,007 is the next structural target if the AI bid holds.
September US CPI, due October 14, can still shift Fed odds for October 28. A hot number reopens the Fed hike debate and widens the US-Japan rate gap, which is bearish for the yen and, paradoxically, supportive of unhedged Japan equity returns in the short term. A soft number has the opposite effect. Traders should be positioned for both readings before that date.
Preparation, not prediction, is what the next three weeks require. The BOJ meeting in late October is a known catalyst. The only question is which side of the 83-17 market split turns out to be right.