October 7, 2026
Bonus Content: Luxury Cabins Are Setting Records. Economy Seats Are Struggling.
Dear Reader,
One of my colleagues – a 20-year Wall Street veteran – just shared something shocking…
He’s trying to move ALL of his money into Elon Musk’s new bank.
Not a few thousand dollars, or tens of thousands… but every single dollar he owns.
This guy worked at a $10 billion hedge fund for years, so he knows Wall Street inside out.
And now he’s saying he can see the writing on the wall for traditional banks.
I agree… I’ve been warning how Elon’s upending banking for months now… and what this means for your money.
Now, suddenly it feels like everyone’s moving their money at once.
Another colleague of mine says “I’m literally in the process of transferring a good chunk of savings… That sweet 6% yield.”
Sure, the yield Elon’s paying is nice – 15x the national average.
But that’s not the real story here…
This is about a fundamental change to the way our banking system works.
And whether you choose to join Elon’s new bank or not, you need to know what’s going on.
I show you how to get on the right side of this here.
Regards.
Luke Lango
Senior Investment Analyst, Investor Place
Luxury Cabins Are Setting Records. Economy Seats Are Struggling.
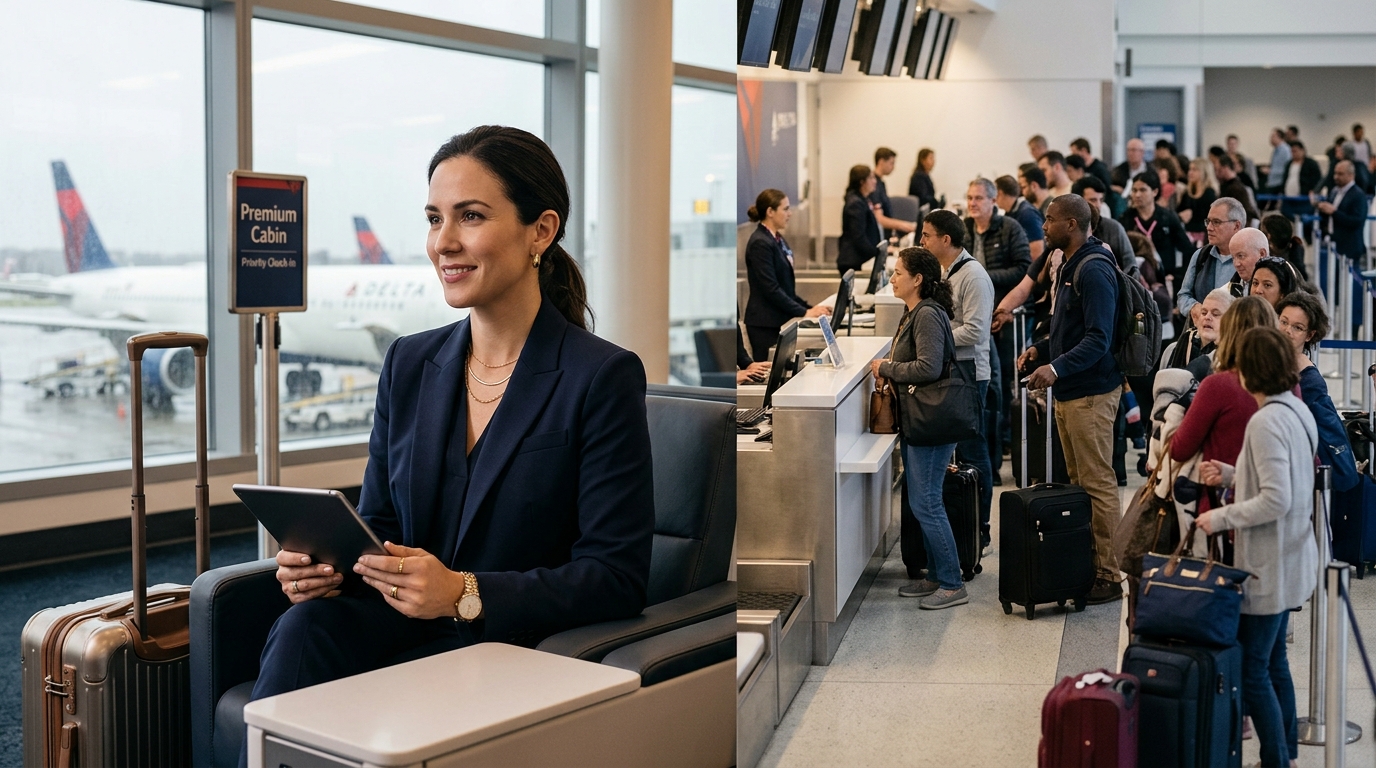
The consumer is not in retreat. One slice of the consumer is. That distinction is the most important macro trade of Q4 2026, and the numbers are no longer subtle.
- Delta Q2 premium cabin revenue: $6.92 billion, versus $6.85 billion in main cabin, a first for Delta
- Delta premium revenue up 17% year-over-year in Q2; United premium revenue up 16% in the same period
- Marriott composite U.S. & Canada luxury RevPAR up 9.5%, ADR at $496.46; select-segment RevPAR up only 4.4%
- Colliers reports at least one luxury or experience-led brand from each of Hilton, Hyatt, Marriott, and IHG posted double-digit RevPAR growth in H1 2026; economy remains under pressure
- Private jet charter activity remains well above 2019 levels; many brokers cite summer quotes 15% to 20% above comparable 2025 trips
- Luxury hotel ADR up 4.9% in North America; premium hotel ADR down 1.8%, per Internova research
- Delta Q3 2026 earnings are scheduled for October 9, before the open
The Split Is Structural, Not Cyclical
Delta CEO Ed Bastian has pointed to strong demand across the board, noting the carrier caters to higher-income customers in the K-shaped economy. The data backs that framing. Premium seat sales outpaced the back of the plane in coach, with premium products generating $6.92 billion in Q2 versus $6.85 billion for the main cabin.
United reported premium revenue up 16% compared to Q2 2025, with loyalty revenue up 11% and cargo up 23%. These are not cyclical bumps. They reflect deliberate capital allocation: Delta has emphasized continued investment in premium seats, with premium mix rising while main-cabin capacity has at times contracted year-over-year.
Hotels tell the same story with different metrics. Marriott’s composite U.S. and Canada luxury segment posted RevPAR of $357.49, up 9.5%, with ADR reaching $496.46, up 8.1%. Colliers has highlighted that across Hilton, Hyatt, Marriott and IHG, at least one luxury or experience-led brand posted double-digit RevPAR growth in the first half, while the economy tier remained under pressure.
Who Holds the Spending Power
The global HNWI population was about 25.3 million in 2025, with global HNWI wealth about $98.3 trillion, according to Capgemini’s 2026 World Wealth Report. That cohort is not pausing. Consumer surveys confirm that wellness and travel budgets are significantly more resilient during economic slowdowns than expenditures on retail luxury goods or general entertainment.
High-end consumers continue to spend and absorb higher rates, and luxury leisure remains the strongest demand segment in 2026, appearing structural rather than cyclical, reflecting a consumer base less sensitive to price fluctuations.
Scenario Modeling
Bull Case: Delta’s Q3 report on October 9 surprises to the upside on premium and corporate demand, and Marriott luxury RevPAR holds near recent highs through year-end. DAL trades toward the high end of its recent valuation range.
Base Case: Premium demand holds but the pace moderates. Delta delivers within the $2.00-$2.50 Q3 adjusted EPS guidance range. Luxury hotel ADR growth slows to mid-single digits as supply in top-tier markets absorbs some incremental demand. The spread between luxury and economy performance narrows modestly without reversing.
Bear Case: If higher-income travelers and frequent corporate travelers pull back spending, categories benefiting most from premium upgrading become particularly exposed, and the premium cabin upgrade trend could soften or plateau. A sustained equity market drawdown would pressure the balance sheets that underpin the entire segment.
Active Trader Framework
October 9 is the event to frame. Delta’s Q3 results are scheduled before the open, and the premium revenue line is the one number that matters. Watch whether the $6.92 billion Q2 premium figure holds directional momentum quarter-over-quarter. Any miss in premium yield, not total revenue, is the faster re-rating catalyst.
Marriott and Hilton report in November. The luxury RevPAR spread versus select-service is the positioning signal: if it compresses below five percentage points, the K-shaped trade weakens. If it widens further, the bifurcation deepens and capital rotation into premium-weighted operators accelerates.
Preparation here means knowing which metric breaks the thesis. Premium yield softening is the tell. Until that changes, the data argues for the divergence to persist.