October 8, 2026
Bonus Content: China’s Stock Market Reopened Into a Yield Shock
Wall Street loves a new story.
But sometimes the more interesting opportunity is a company that has been waiting years for the market to catch up.
One little-known Nasdaq company has spent more than 25 years developing professional drone technology that is now a priority in Washington.
This is not a company trying to invent itself around D.C.’s latest push.
It was developing these technologies long before America’s current drone demand started.
That experience matters as the Pentagon looks for scale and Washington directs more attention toward domestic manufacturers.
Yet the company is still trading under $5… for now.
If America’s drone industry is entering a much bigger chapter, investors may want to know why this pioneer remains so overlooked.
China’s Stock Market Reopened Into a Yield Shock
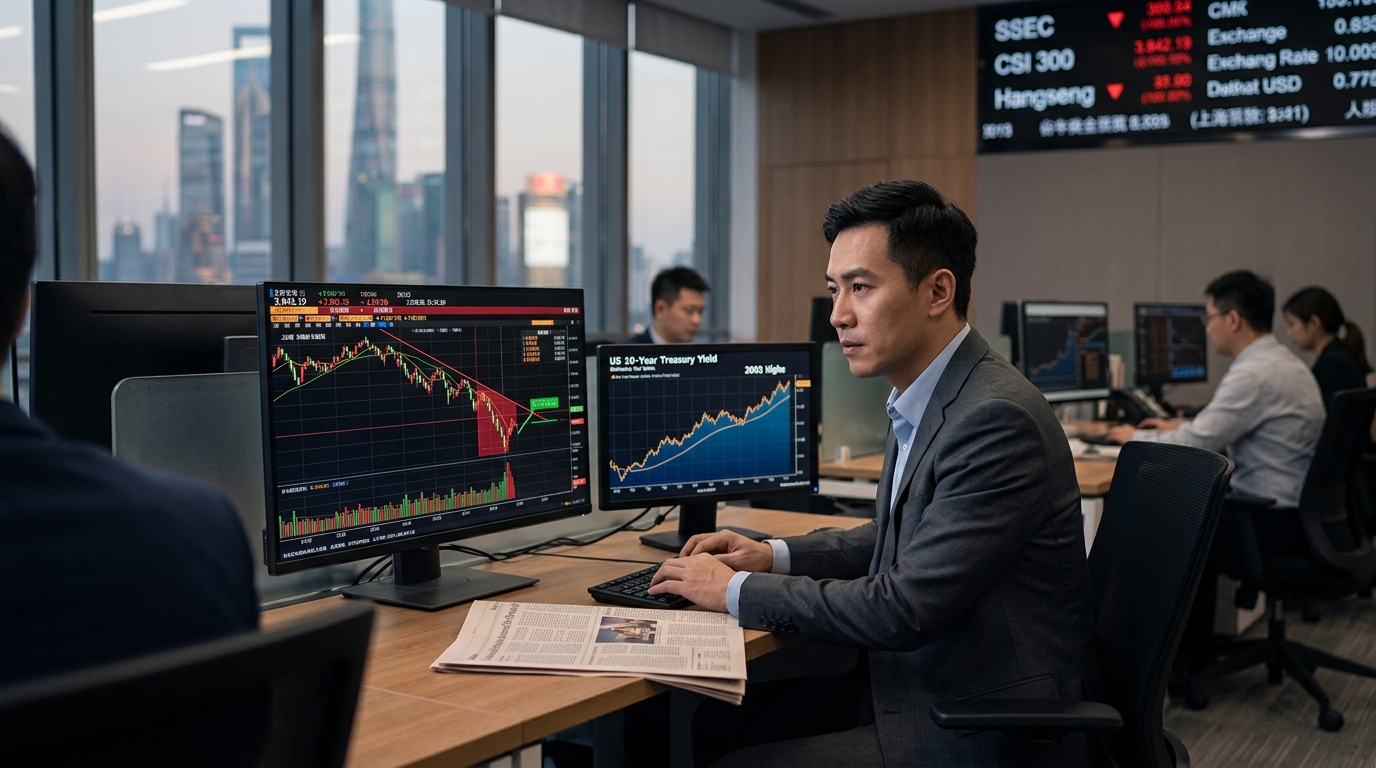
Mainland China’s equity markets reopened this morning after seven days dark. The Shanghai Composite resumed trading from its September 30 close of 3,842.19, and early price action offered a muted verdict: the index edged up roughly 0.26% to around 3,852 in the morning session, while the CSI 300 added 0.3% to 4,372.06. Neither move represents a clean signal. They represent a market still calibrating.
What those investors are calibrating to is significant. During the seven-day closure, the 10-year US Treasury yield traded in the 5.32% to 5.36% area, levels not seen since 2002. The 30-year pushed to about 5.69% intraday. And on Wednesday, the Fed minutes from the September meeting confirmed what traders feared: officials discussed that another 2026 hike could be appropriate, after a unanimous 25bp increase to 3.75%-4.00% in September that was the first hike since 2023.
What Hong Kong Already Priced
Hong Kong traded through the break without mainland participation, and the Hang Seng bore the initial shock. On October 2, the index dropped 2.6% to 23,972, its steepest single-session fall since March, as it reopened from its own holiday and caught up immediately with the global bond sell-off. The index staged a partial recovery over the following sessions, closing Wednesday at 24,130.50, down 0.62% on the day. That partial bounce came without southbound Stock Connect flows, which only resumed this morning.
The gap between Hong Kong’s absorbed repricing and Shanghai’s frozen pre-holiday levels is the central trading variable today. Without mainland buying for four sessions, Hong Kong-listed Chinese shares traded on thinner, more offshore-driven liquidity. Stock Connect restoration restores a major flow channel but does not automatically close the price gap.
Sector and ETF Positioning
FXI, the iShares China Large-Cap ETF, carries a year-to-date return of roughly -12.67%, with the price sitting about 20% below its 52-week high. KWEB, the KraneShares CSI China Internet ETF, has taken a harder hit: down approximately 27.9% year-to-date, and recently trading near $23.86, against a 52-week high of $43.08. That gap to the 52-week high reflects cumulative yield pressure and a structural de-rating of Chinese internet names that did not reverse during Golden Week.
Tech names face compounding headwinds. The Hang Seng Tech Index showed some resilience, gaining about 1.1% on October 6 before slipping on October 7. Alibaba and Tencent were both under renewed selling pressure heading into today’s reopening. High global bond yields are the explicit constraint: with the 10-year US Treasury above 5.3%, the discount rate applied to long-duration growth assets has shifted materially.
On the support side, Beijing introduced a new one-percentage-point mortgage subsidy effective October 1, offering a policy catalyst for property-adjacent names. Golden Week foot traffic at 78 monitored shopping streets and business districts rose 3.4% year-on-year from October 1 to 3, while revenue rose 5.3%, although Citi described broader early consumption data as underwhelming. Official travel and spending figures are still pending.
Technical Framework
The Shanghai Composite entered today’s session only 2.7% above its 52-week low of 3,741.11, and 9.8% below the 52-week high of 4,258.86. That placement in the lower quartile of the annual range means the index has limited cushion before retesting structural support. The 3,800 level is the first line. A sustained break below 3,741 would signal that policy support has failed to anchor sentiment.
To the upside, 3,900 is the first meaningful technical hurdle for a post-holiday recovery. China A50 futures came into today less than 1% below their September 30 close despite the turbulence in between, suggesting controlled expectations rather than panic. The USD/CNY rate sat at approximately 6.70 this morning, stable and not adding currency pressure to the equation.
Scenario Modeling
Bull Case
Beijing accelerates fiscal and monetary support, southbound Stock Connect flows absorb Hong Kong’s discount, and US yields stabilize below 5.20%. The Shanghai Composite reclaims 3,900 within two sessions and tech names in KWEB begin to narrow the gap to their offshore Hong Kong equivalents. FXI finds a bid as large-cap financials and energy benefit from the mortgage subsidy and commodity tailwinds.
Base Case
Today’s muted open extends into a choppy first week. The Shanghai Composite holds the 3,800-3,870 range while markets assess official Golden Week spending data and watch Fed speakers for confirmation of the December hike path. KWEB trades in the $23-$25 band. The Hong Kong discount narrows slowly as southbound flows return but do not surge.
Bear Case
US 10-year yields push decisively above 5.40%, the December Fed hike becomes fully priced, and the USD strengthens against the CNY. Stimulus disappointment triggers a break below 3,800 on the Shanghai Composite, with 3,741 as the next reference. KWEB tests its 52-week low near $23.23. FXI underperforms as financials reprice to a higher-for-longer cost of capital.
Active Trader Framework
The reopening creates a bifurcated risk structure. Watch 3,800 on the Shanghai Composite as the defining support level for the first two sessions; a sustained hold there with improving volume would be constructive. On the downside, position sizing around the 52-week low at 3,741 should account for the possibility that a second test of that level brings accelerated selling from domestic institutions under redemption pressure.
For offshore proxies, the Stock Connect resumption is the near-term catalyst. KWEB’s extreme distance from its 52-week high rewards patience over aggression; momentum indicators remain deeply negative on a six-month basis. FXI’s relative resilience, down only around 12.67% year-to-date versus KWEB’s roughly 28%, reflects the earnings defensibility of large-cap state-owned enterprises against a high-yield backdrop. That distinction matters when structuring exposure.
The macro environment does not reward complacency. Preparation over positioning is the discipline today demands. Monitor the first two full sessions for volume confirmation, watch the CNY at 6.70 as a currency stability signal, and treat any bounce toward 3,900 as a level requiring fresh fundamental justification, not a given.