October 15, 2026
Bonus Content: RTX Reports in Five Days. The Debris Cloud at 855 km Is the Unpriced Line Item.
JPMorgan, Bank of America and Morgan Stanley rarely agree about anything. Lately they have agreed that gold belongs in client portfolios. Central banks appear to agree too, buying at the fastest pace in roughly four decades. When institutions that normally argue about everything start moving in the same direction at once, it is usually worth asking why. The free Reagan Gold Group guide sets out all of their reasoning in plain language.
CLAIM YOUR FREE COPY OF THE GUIDE
P.S. Institutions do not buy hard assets because they feel optimistic. They buy them because they are managing a risk they can already see coming. The free guide explains exactly which risk, and why now.
RTX Reports in Five Days. The Debris Cloud at 855 km Is the Unpriced Line Item.
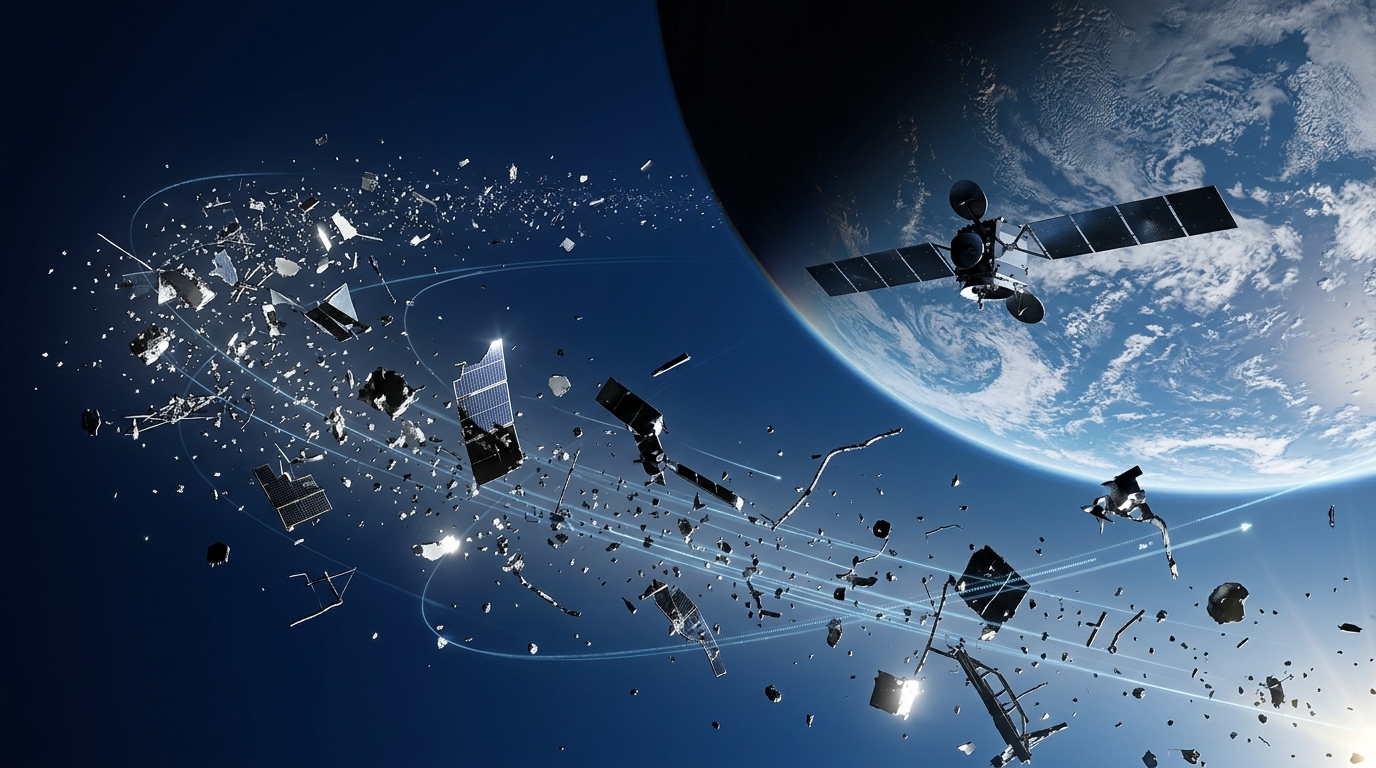
On October 5, a Soviet-era weather satellite that stopped functioning decades ago appears to have added new debris fragments to one of the most congested corridors in low Earth orbit. Launched in 1981, Meteor 2-7 is suspected to have fragmented at an altitude near 855 km, where analysts have suggested an internal energetic source as one possible driver. It was not isolated. The Meteor 2-7 event followed the confirmed fragmentation of the Cold War-era US satellite USA-32 on September 13, 2026. Two major breakups in six weeks, no binding international governance framework, and a debris population that, according to the European Space Agency’s space environment statistics, sits around the mid-40,000s of regularly tracked objects as of October 2026.
That is the structural backdrop for RTX’s Q3 earnings, due before the open on October 20. Analysts are focused on Raytheon margins and Pratt aftermarket output. What the consensus is not pricing is the compounding demand signal for space domain awareness services, the precise specialty where RTX has built a quietly defensible position.
The Business Behind the Debris Count
Raytheon NORSS, RTX’s UK-based space domain awareness unit, holds a contract with the UK Space Agency to provide Space Surveillance and Tracking data in LEO, using its ground-based LOCI camera network to collect observation data on objects including space debris, defense assets, and commercial satellites. Raytheon NORSS has expanded LOCI’s international deployment, with deployments extending beyond the UK to sites in the US and Australia. That sensor footprint is now operationally relevant in a way it was not eighteen months ago.
SpaceX’s Starlink satellites executed over 355,000 collision avoidance maneuvers over the past year, with each satellite now dodging debris on an almost weekly basis. ESA’s most recent space environment reporting underscores the same direction of travel: collision risk is rising in congested LEO regimes, and ESA has warned that collision-driven debris growth is already self-sustaining without active debris removal. Every avoidance maneuver is a data event. Every data event requires persistent sensing architecture. That is RTX’s lane.
What the Numbers Show Going into October 20
RTX reported Q2 2026 adjusted EPS of $1.89, with sales of $24.7 billion, and company backlog of $289 billion. For Q3, analysts forecast Raytheon segment net sales of $7.67 billion, representing year-over-year growth of 8.9%.
Those are the headline lines. The unmodeled driver is how rapidly space domain awareness spending scales as LEO operators, insurers, and defense ministries treat persistent tracking as non-discretionary. Investment by satellite operators in collision monitoring, automatic maneuvering, and controlled disposal technologies is accelerating as these capabilities shift from optional to operationally required.
Three Scenarios into Earnings
Bull case: Raytheon segment revenue clears $7.8 billion, management explicitly quantifies space domain awareness contract growth within the intelligence and space portfolio, and Raytheon’s Q2 book-to-bill of 2.42 proves less episodic than feared as defense backlog converts. RTX trades toward the roughly $228 average analyst target on accelerating defense backlog conversion.
Base case: Raytheon delivers near the $7.67 billion consensus. Space awareness contracts are mentioned qualitatively but not broken out. The stock holds recent levels, with the debris catalyst remaining a medium-term re-rating story rather than a near-term price mover.
Bear case: Raytheon margins disappoint against the 12.6% Q2 level, international mix pressures pricing, and the broader defense spending debate in Washington reintroduces budget ceiling risk. A more cautious sell-side tone and elevated insider selling chatter add a second layer of caution for positioning ahead of the earnings release.
The budget ceiling risk in the bear case sits inside a larger structural question. Global defense spending has risen for eleven consecutive years, and the NATO rearming cycle is reshaping how analysts value contractor backlogs.
What Traders Should Watch
RTX has a 52-week range of $155.64 to $226.88 and a market capitalization around $251 billion, with beta around 0.31. The low beta matters: this is not a momentum trade. It is a structural positioning decision around a defense platform with growing exposure to a deteriorating operating environment in orbit.
RTX is not the only defense platform where backlog size and conversion pace are diverging from the stock price. General Dynamics is carrying a record $136.5 billion backlog while Wall Street debates whether Electric Boat can actually build fast enough to convert it.
The key level to monitor after the October 20 call is whether management begins to carve out space domain awareness as a distinct reporting category. That disclosure shift, not the Q3 EPS beat or miss, is the event that re-rates the thesis. Prepare for it before it happens.