October 22, 2026
Bonus Content: Eaton’s $15.2B Backlog Is the Real AI Power Trade
Washington Is Building. This Market Could Create a New Nasdaq Winner.
The biggest market opportunities rarely come from one product.
They emerge when a new technology begins changing several industries at once. That may be what investors are looking at now.
The global drone market is projected to reach $182.4 billion by 2033. But the defense sector is only one part of the story.
Drone technology is also expanding across public safety, medical delivery, emergency response, infrastructure and agriculture.
One little-known Nasdaq company has spent more than 25 years building across those markets.
Its business extends beyond aircraft. It also includes software, AI, sensors and professional services.
For investors, that range provides options.
The company is not dependent on one customer, one mission or one path to growth. As government and commercial adoption expand, several parts of its business could benefit.
Wall Street may still see a small drone company, but the opportunity is much broader than it looks.
Explore the Nasdaq with several ways into America’s next technology boom.
Eaton’s $15.2B Backlog Is the Real AI Power Trade
ETN closed at $381.98 on October 20, off its August 12 all-time high close of $459.96 by 17%. The selloff has nothing to do with demand. It has everything to do with a question the market has not yet answered: can Eaton convert a historically large backlog into margin dollars fast enough to justify a near-40x multiple on its 2026 adjusted EPS guidance? Q3 results land November 3. That date now owns the stock.
- Q2 2026 revenue hit a record $8.5 billion, up 21% year over year, with organic growth of 18%
- Electrical businesses book-to-bill expanded to 1.3 (rolling twelve months)
- Electrical segment total backlog rose 43% year over year, with total backlog at the end of June up 103% versus June 2025
- U.S. data center backlog: 307 gigawatts, equal to 15 years of demand at 2025 build rates
- Data center organic revenue grew about 65% in Q2
- Full-year adjusted EPS guidance raised to $13.50 midpoint; Q3 adjusted EPS guided at $3.46 to $3.56
- Analyst consensus: Buy, with a mean price target near $486, implying about 27% upside from $381.98
The Backlog Is Not the Story. Conversion Rate Is.
Management disclosed that U.S. data center backlog reached 307 gigawatts, equivalent to 15 years of demand at 2025 build rates. That figure sounds imposing, but its tactical significance is more specific: the market is trying to handicap how much of that multi-year demand actually converts to shipped revenue inside the next few quarters versus being weighted to later deliveries. For a stock trading at nearly 40x on current-year adjusted EPS guidance, investors are being asked to pay now for revenue that, in a meaningful portion, sits further out on the delivery curve. That is a duration bet, and duration bets get repriced when ten-year yields move.
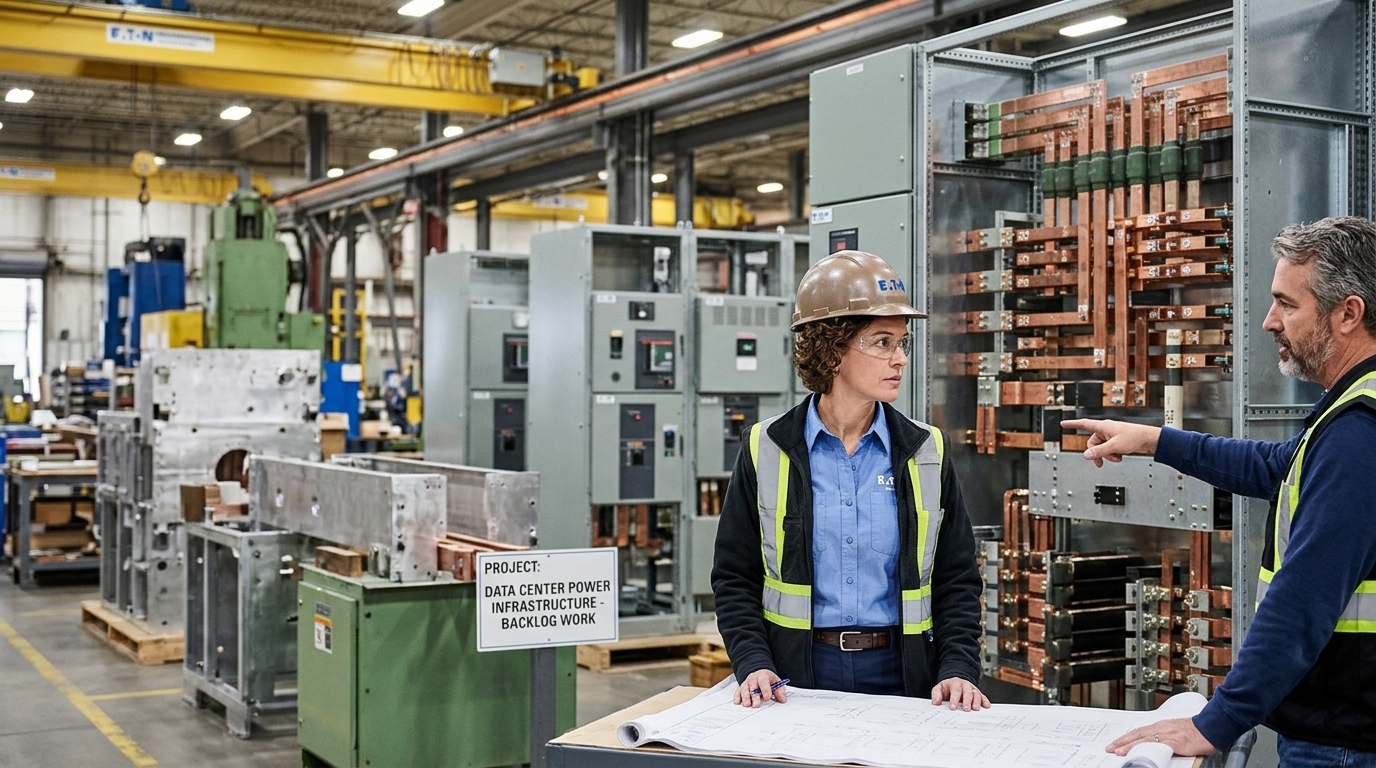
The transition from cloud data centers to AI data centers has increased Eaton’s content opportunity per megawatt, rising from $1.5 million in cloud applications to $3.4 million in AI applications after the Boyd acquisition. That per-megawatt content uplift is the margin lever the bull case depends on. If 307 gigawatts of contracted backlog eventually converts at $3.4 million per megawatt, the revenue math is transformative. The timing is not.
Where the Substation Bottleneck Creates Pricing Power
Wood Mackenzie has said power and generator step-up transformer lead times have roughly tripled since 2021 to around 150 weeks on average. That supply crunch hands Eaton structural pricing power competitors cannot easily replicate. Data center operators are securing factory production slots years in advance or paying substantial premiums, and 2026 has increasingly looked like a world where competition for factory capacity dictates project timelines. Eaton’s Nebraska switchgear expansion, an investment of over $30 million with production expected to begin in the first half of 2027, is partially a response to that squeeze. It is also a capacity constraint that will weigh on near-term shipment velocity.
Technical Framework
The 50-day simple moving average is about $423, and ETN is now trading below it. The 200-day SMA is about $390 as a next structural reference. With the stock at $381.98, price has essentially tested that zone. A close below $372 on meaningful volume opens the door toward $355, where the late-2025 base consolidation occurred. To the upside, reclaiming $408 on volume ahead of November 3 would signal positioning ahead of the Q3 report.
Scenario Modeling
Bull Case
Q3 adjusted EPS prints above $3.56, Electrical Americas margin expands sequentially above 28%, and management raises full-year guidance for the third consecutive quarter. ETN revisits $430 to $450 within two weeks of the report. Catalyst: shipment acceleration from the capacity expansion projects already funded.
Eaton is not the only power infrastructure name where backlog size and near-term earnings delivery are telling different stories. GE Vernova’s $176 billion backlog and record order velocity showed the same gap between headline EPS and underlying demand momentum.
Base Case
EPS lands in the middle of the $3.46 to $3.56 guided range. Margin commentary satisfies but does not accelerate upgrades. Stock stabilizes in the $390 to $415 range through year-end as the market waits for 2027 conversion evidence.
Bear Case
Factory ramp delays push Electrical Americas margins below 26%, and management acknowledges that near-term backlog conversion is running behind plan. Stock tests the 52-week low zone near $312. The risk is not demand. The risk is execution against a $15.2 billion obligation in a supply chain still constrained by roughly 150-week transformer lead times.
The 150-week transformer constraint is not unique to Eaton’s supply chain — it is the governing condition across the entire power equipment sector. Suppliers with locked-in long-term contracts have structurally separated themselves from those still exposed to spot procurement timelines.
Active Trader Framework
The November 3 earnings date is the event horizon. Implied volatility is likely to expand into the report, making long premium strategies worth considering for traders who want exposure without directional commitment at these levels. Key levels to monitor: $372 as near-term support, $408 as the level that must reclaim for the technical picture to neutralize. Company commentary in recent materials has pointed to EBITDA growth expectations accelerating into the back half of the year, powered by pricing actions already in place. If those numbers materialize, the valuation debate shifts. If they do not, the multiple faces real pressure at a near-40x starting point in a high-yield environment.
Preparation here means knowing what Q3 margin delivery actually implies for the 2028 backlog conversion thesis before the number hits. Position sizing should reflect that this is a high-quality franchise trading through a real execution question, not a distressed situation. Those are different risks, and they demand different frameworks.