October 23, 2026
Elon Musk’s Next Partnership: BuyThis Stock Now
Bonus Content: The Nasdaq Fell 2.6%. Most Stocks Rose. Here Is Where the Money Went.
Former tech executive Jeff Brown, the man who picked Nvidia in 2016, before it jumped as high as 37,800%, just got inside a Cybercab, Elon Musk’s new car that has no steering wheel or pedals… and what happens will shock everyone. Click here to see the details or read more below.
Dear Reader,
In April 2026, Elon Musk announced he was partnering with Intel.
The result?
Shares took off…
And were trading 177% higher just two months later.
I believe Elon is about to announce a NEW partnership with this little-known company…
To work on what he called “the most epic AI project in history.”
But you need to act fast…
Because Elon has already approached this company.
I believe he’s going to make it official by October 30…
Which should send shares higher than anyone can imagine.
Click here to see the details.
We have so much to look forward to,
Jeff Brown
Founder & CEO, Brownstone Research
The Nasdaq Fell 2.6%. Most Stocks Rose. Here Is Where the Money Went.
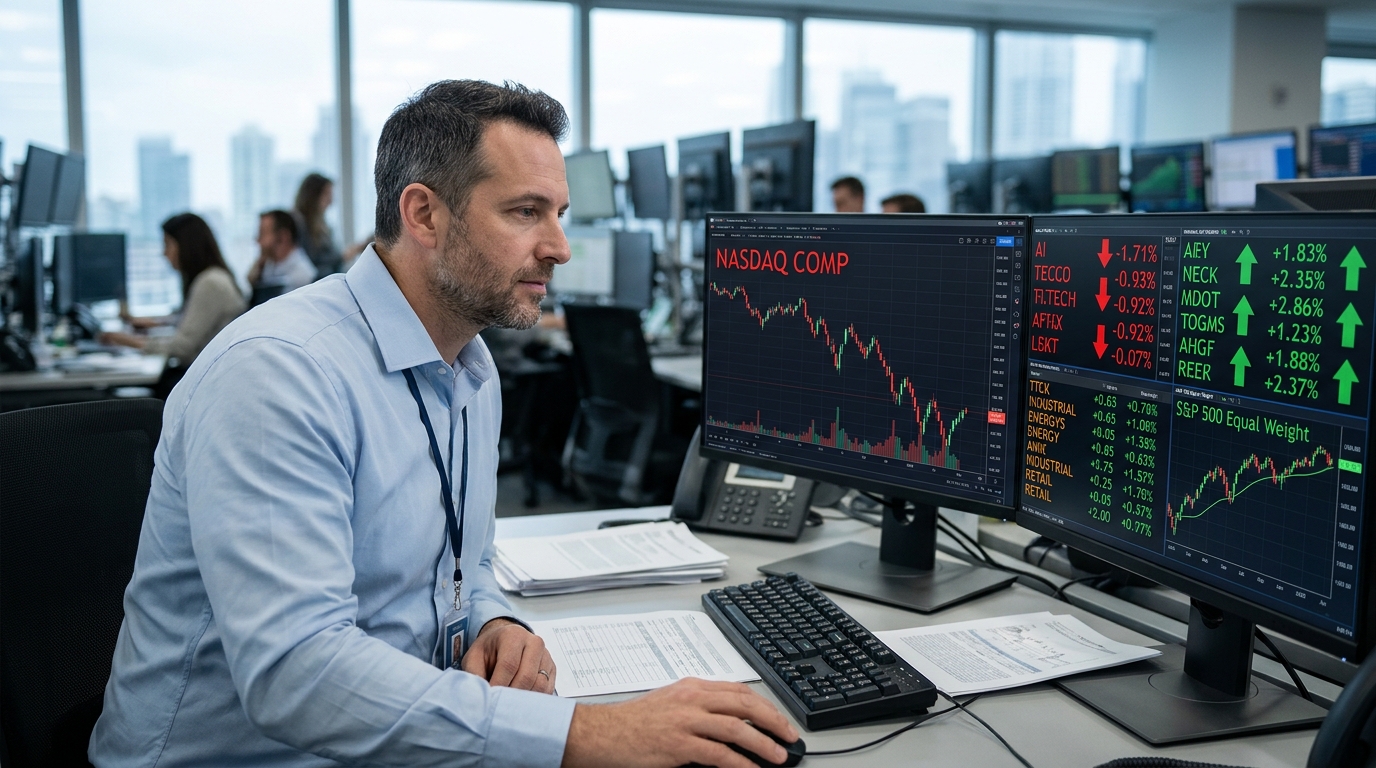
Thursday closed with two radically different markets sharing the same timestamp. The Nasdaq Composite dropped 2.60% to 26,008.86, its worst session since June, while the S&P 500 shed 1.21% to 7,663.43, its worst day since July. Yet the Invesco S&P 500 Equal Weight ETF finished up 0.73%, beating the cap-weighted index by nearly two full percentage points. High-yield credit spreads were roughly unchanged on the day. The majority of S&P 500 stocks advanced.
That divergence is the only fact that matters this morning.
What Actually Happened
Two catalysts hit in quick succession. First, Meta reported Q3 revenue of $64.6 billion, up 26% year over year, beating consensus of $63.34 billion. The market ignored the beat entirely and fixated on one line: full-year capex guidance narrowed to $135–$145 billion from the prior $130–$145 billion range. Quarterly capex was $34.9 billion. Operating cash flow was $32.8 billion, pushing free cash flow to negative $2.1 billion. Meta fell 6.98%.
Second, Lam Research’s CFO warned during its earnings call that supply constraints would push some December-quarter shipments into March, with the whole industry facing similar pressure as capacity and component bottlenecks get worked through. Lam itself closed down 11.76%. The damage radiated immediately: AMD fell 8.10%, Marvell dropped 8.70%, Intel shed 8.0%, Nvidia declined 4.40%, and the Philadelphia Semiconductor Index lost 6.72%, erasing roughly $200 billion in sector market value in a single session.
Rotation, Not Liquidation
The credit market’s relative silence told sophisticated traders what the index levels obscured. When capital genuinely flees risk, high-yield spreads widen. They did not materially move. Instead, money moved sideways within equities, rotating out of AI infrastructure and into sectors that have been largely ignored for months.
Consumer Staples (XLP) surged 3.29%, its best single-session performance in years, with Procter & Gamble alone gaining about 5.6% on a Q1 revenue beat of $23.28 billion. Utilities added 2.07%, Health Care rose 1.32%, Real Estate gained 1.09%, and Financials advanced 1.09%. Six of eleven S&P 500 sectors finished in positive territory. The 10-year Treasury yield fell into the 4.9% range, its first close below 5% since September.
XLP is now up 11.3% in October, on pace for one of its strongest months since the ETF launched in 1998. That kind of defensive surge has historically preceded periods of broader market stress, though it has also resolved to the upside. The rotation is real; whether it is a signal or a repositioning ahead of next week is the operative question.
The Setup Ahead: Oct. 28–29
Microsoft reports October 28 after the close, with options pricing implying a 4.6% move. Azure’s most recent quarterly growth rate was roughly 40%, trailing Google Cloud’s 82% and Amazon Web Services’ 37% acceleration. If Azure does not show acceleration, Microsoft could face relative underperformance regardless of headline numbers. Alphabet follows the same evening, with analysts projecting revenue of approximately $127.9 billion. Amazon reports October 29.
The capex-versus-returns tension is not new for Microsoft. Azure’s ability to convert AI spending into durable, measurable business results is exactly what the market will demand from Microsoft earnings.
The critical variable across all three is capex guidance. Meta’s number has already poisoned sentiment. If Microsoft, Alphabet, or Amazon signal spending above current expectations, the AI infrastructure trade faces another leg lower. If any of them suggests discipline or visible return on investment, the rotation back into semis could be sharp.
Scenario Framework
Bull Case: Microsoft and Alphabet report capex in line or below current estimates, Azure accelerates above 42%, and Google Cloud sustains triple-digit growth. Semiconductors reclaim the 6,700–6,900 range on the Philadelphia Semiconductor Index. QQQ recovers above 460.
Base Case: Capex guidance stays elevated but within range, results broadly beat on revenue, and the market digests the spending concern without a second leg lower. Equal-weight outperformance persists. QQQ consolidates between 445 and 460 through month-end.
Bear Case: A second hyperscaler raises its capex floor materially, free cash flow guidance disappoints, and the AI infrastructure theme faces a full reset. The Nasdaq tests the 25,200–25,500 zone. Defensive rotation accelerates, but that signal itself becomes a warning.
Active Trader Framework
The structural read from Thursday is that this is a sector-level event, not a systemic one. Credit confirmation of a broader breakdown is not yet present. Traders considering semiconductor exposure should monitor SOXX relative to its 50-day moving average and watch whether volume patterns on any recovery attempt show institutional accumulation or simply short covering. On the defensive side, XLP’s overbought condition after an 11% October run warrants sizing discipline on new entries. Position sizing ahead of a concentrated earnings week, where nearly half of S&P 500 market weight reports in five sessions, demands smaller initial exposure and defined risk levels. Preparation over positioning is the correct posture into October 28.