October 25, 2026
Bonus Content: Honeywell’s Data Center Orders Just Doubled. The Cooling Angle Traders Miss.
Hey,
With the Fed hiking rates for the first time since 2023, I thought I’d share this free gift with you.
Hurry, you’ll want to put this strategy into action this week.
In your corner,
Dave Aquino
Base Camp Trading
Honeywell’s Data Center Orders Just Doubled. The Cooling Angle Traders Miss.
Honeywell Technologies reported Q3 2026 results on October 22, and the headline beat was clear: adjusted EPS of $2.27 topped consensus by about $0.11, organic sales grew 7%, and segment margins expanded 370 basis points to 21.3%. The stock closed at $221.15 on October 23, roughly 12% below a recent 52-week high near $252. Wall Street’s average price target sits around $253 to $255, implying about 15% upside from current levels.
Most coverage focused on the LNG backlog and the Forge software platform nearing $1 billion in recurring revenue. The line that deserves sharper attention: orders in the data center vertical were up over 100% year to date. That is not a rounding error. It reflects a structural shift in what Honeywell sells and to whom.
Where the Cooling Chemistry Fits
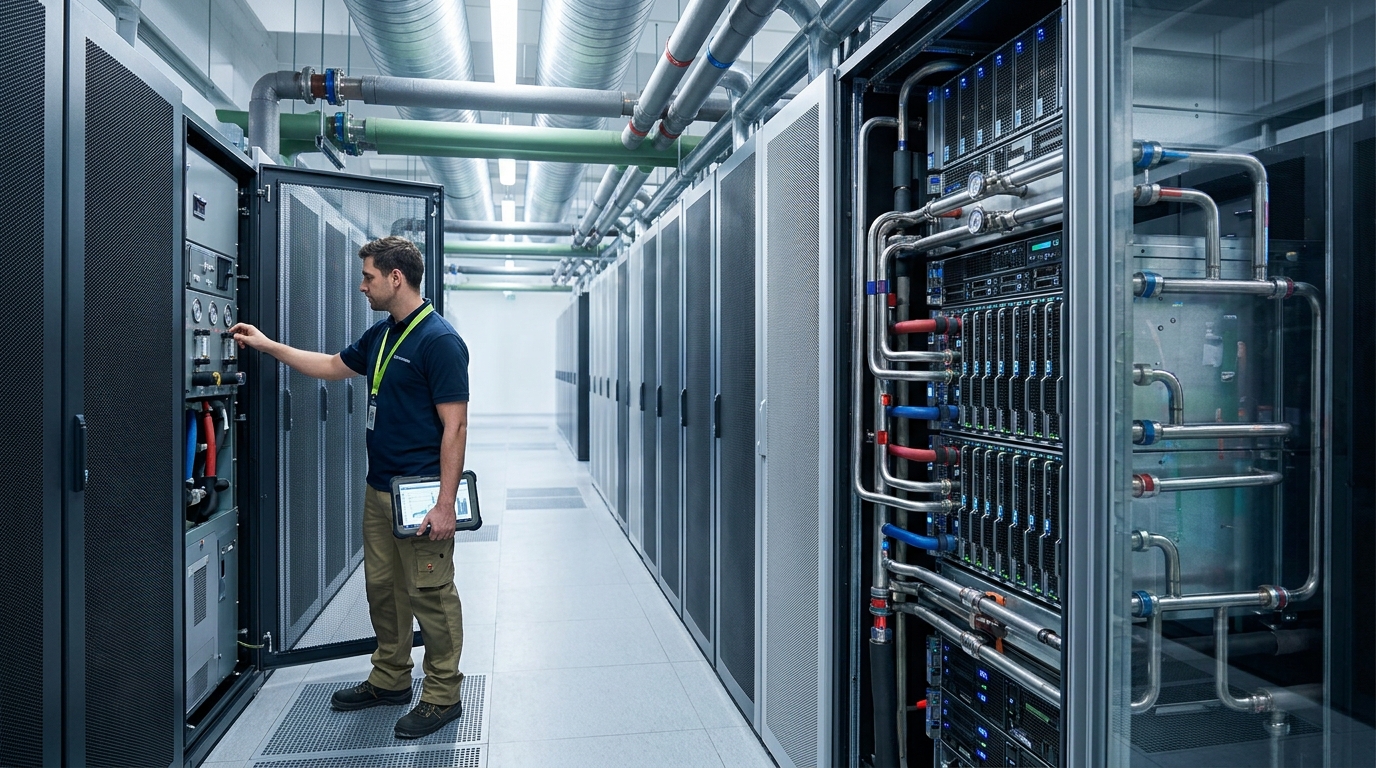
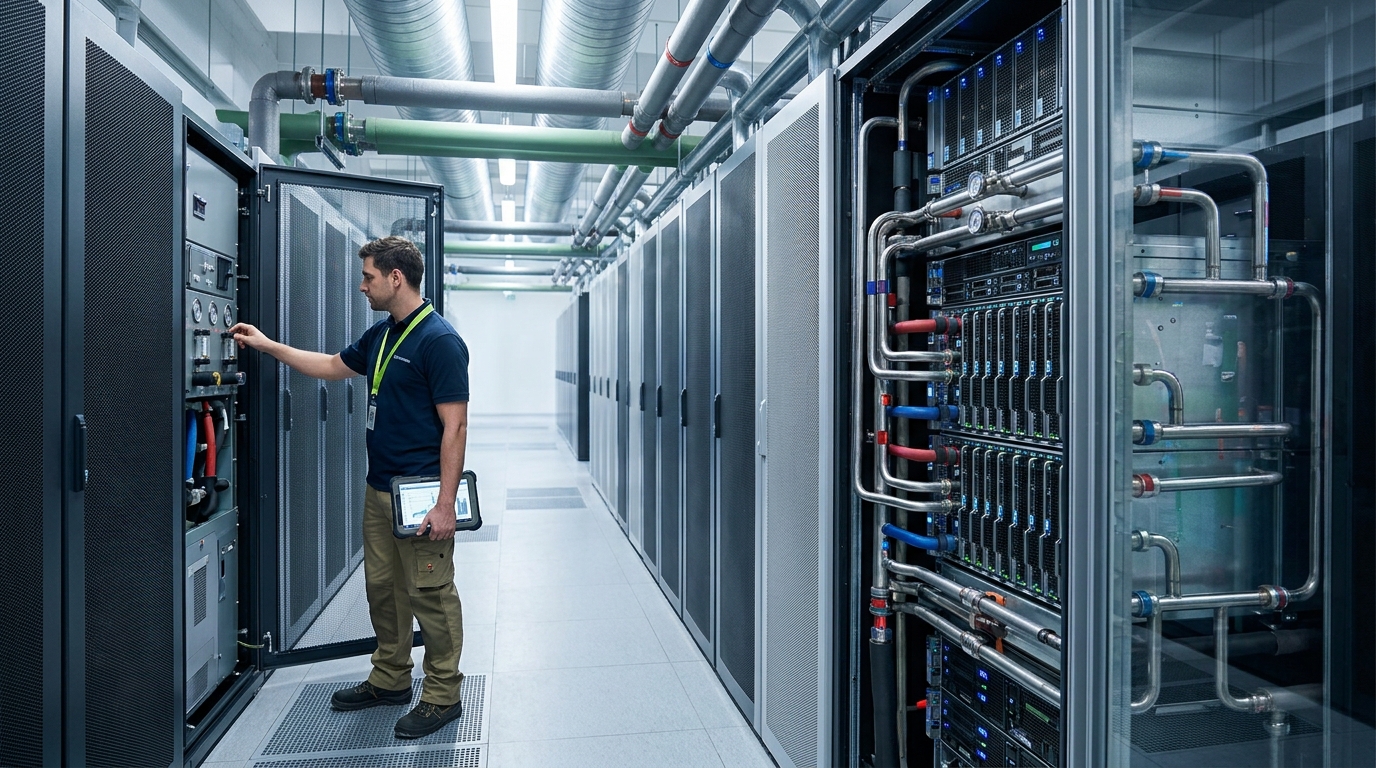
Supercritical CO2 operates above 31°C and 73.8 bar, at which point it becomes a single-phase supercritical fluid. That combination can support very high heat-transfer performance in certain closed-loop designs, which is why supercritical CO2 concepts are increasingly showing up in next-generation data center thermal and energy-recovery work. The physics matter because leading-edge AI racks are now commonly discussed in the tens-to-100 kW class. Air cooling is increasingly constrained at those densities.
Honeywell’s industrial position in this loop is specific. Its Process Automation and Technology segment sells the control valves, instrumentation, and control systems that regulate pressure and flow in high-cycle, high-pressure loops. Honeywell also has specialty refrigerants and heat-transfer fluids, but the article’s earlier claim that it has a dedicated “specialty fluids division” supplying dielectric and phase-change working fluids for two-phase direct-to-chip systems was too specific to state as fact here. Likewise, the attribution to a ZutaCore engineer and the 18°C boiling point detail could not be verified from primary, citable public materials, so it has been removed.
The Market Structure Around HON
The AI datacenter liquid cooling market is valued at roughly $3.7 billion in 2026 and is projected to reach about $17.8 billion by 2036 at a 16.9% compound annual growth rate, with direct-to-chip systems cited at about 47% of the mix in that forecast. Estimates vary across research firms, but the direction is consistent: higher rack densities are pulling more spend into liquid cooling and the adjacent controls stack. Honeywell sits at the intersection of both: valves, sensors, and controls required to run higher-pressure and higher-duty-cycle systems are not commodity items. Qualification cycles are long, switching costs are high, and the company ended Q3 with backlog of nearly $19 billion.
Process Automation and Technology sales grew 8% organically in Q3, and free cash flow conversion reached 95%, with management guiding to above 100% in Q4. The company raised full-year organic growth guidance to 4% to 5% from 3% to 4%.
Scenario Framework
Bull Case: Higher-density rack architectures accelerate adoption of advanced liquid cooling and higher-pressure thermal loops. HON’s control valve, instrumentation, and controls qualifications become a gating constraint for competing hyperscale buildouts. The stock re-rates toward the $270 to $293 range that some covering analysts have published as targets.
Base Case: Data center orders sustain triple-digit growth into 2027. Forge’s recurring revenue closes the gap to $1 billion and begins generating visible margin lift. HON trades toward $240 to $255 as backlog converts and stranded costs from the aerospace separation clear by year-end 2026.
Bear Case: A pause in hyperscale capex commitments stalls order momentum. Direct-to-chip remains the dominant architecture, limiting the addressable share for more exotic high-pressure loop components. HON consolidates near $200 to $210 support.
The bear case hinges on whether Honeywell holds pricing authority or merely participates in the cycle. Component suppliers with genuine monopoly positions have extracted margin even as Nvidia’s own input costs rose.
Active Trader Framework
HON has held above $205 on multiple tests since August, a level that aligns with the post-separation re-rating floor. The 21-day moving average near $215 is the near-term resistance to watch after the post-earnings move. Position sizing should account for the stock’s elevated price-to-free-cash-flow multiple, which has recently screened around the high-50s on trailing data, and that compresses the margin for error if Q4 delivery on the 100%-plus free-cash-flow conversion target slips. Volatility will be most sensitive to any hyperscaler capex revision, not to Honeywell’s own execution.
Preparation over prediction. The cooling infrastructure cycle is real, the backlog is verified, and the Q3 data center order figure is not ambiguous. What remains to be priced is which component layer inside advanced cooling loops commands the widest moat, and Honeywell’s controls and instrumentation position is the answer most institutional models have not yet fully disaggregated.