Record top-line numbers landed this morning. The underlying brand picture is messier. Celsius Holdings posted Q3 2026 revenue of $847.2 million, a record for the company, compared with $725.1 million in the prior-year period. The result beat consensus revenue estimates. Shares jumped. The premarket applause was understandable. But traders focused on durability need to look past the headline.
Who Actually Drove the Beat
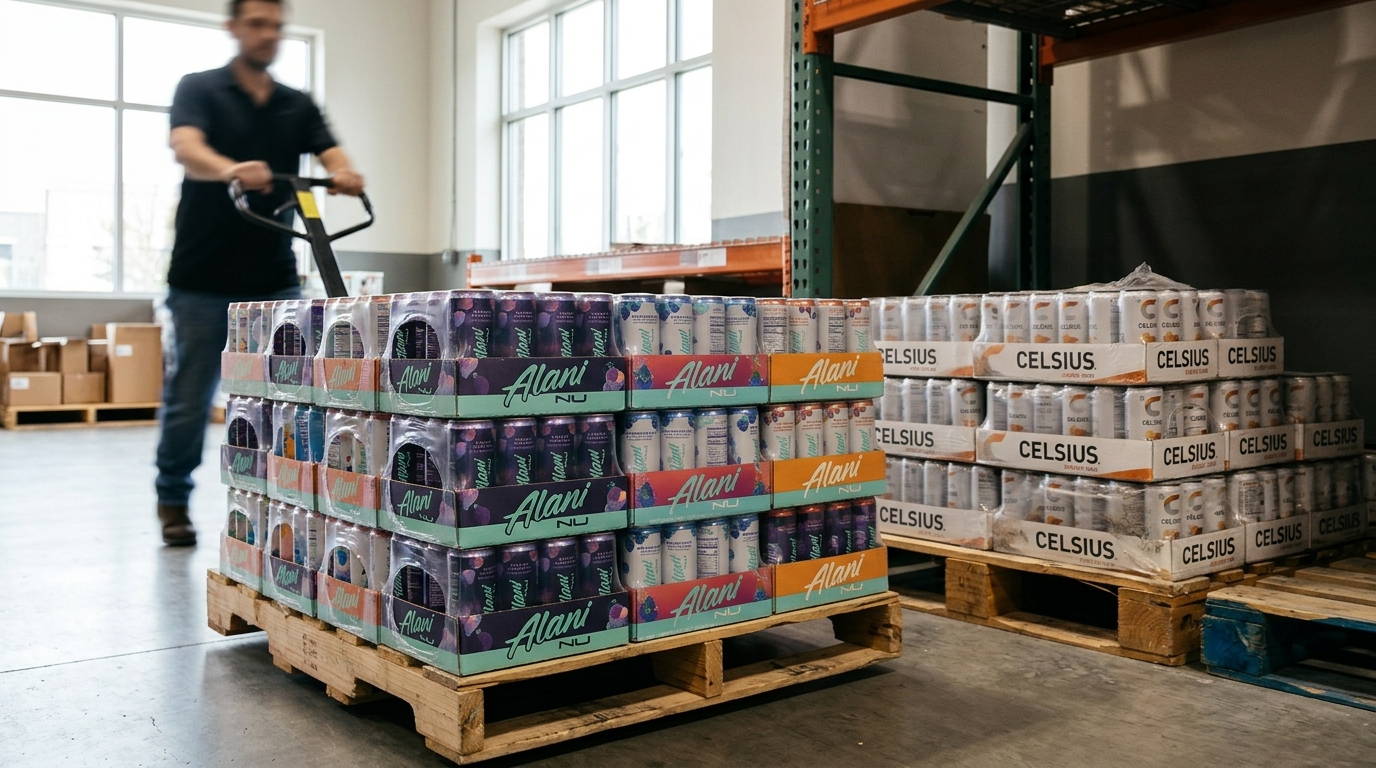
Alani Nu revenue rose 24% to $410.1 million, driven by strong demand and increased distribution within the PepsiCo DSD system, while CELSIUS brand revenue fell 6% to $356.8 million due to inventory rebalancing, club-channel softness, and SKU optimization. Alani Nu delivered the strongest quarter in the brand’s history, led by Witch’s Brew, the largest limited-time offer in the portfolio’s history. Strip that seasonal push out and core Alani Nu retail sales in tracked channels still grew approximately 50% year over year.
That is the distinction that matters. Alani Nu has earned its run. The CELSIUS name has not yet earned back market confidence. Management acknowledged it plainly on the call: “Brand Celsius is not yet where we want it to be.”
The Margin Problem Is Real
Gross margin contracted to 46.8% from 51.3%, a 450-basis-point decline, as aluminum and fuel inflation and a higher mix of DSD sales offset supply-chain integration efficiencies. GAAP net income rose sharply, but gross margin fell about 450 basis points and adjusted EBITDA declined 3%.
Adjusted EBITDA was $198.6 million, or 23.4% of revenue. Sequential EBITDA margin improvement is a real data point. It is not enough to dismiss the gross margin compression.
The Valuation Argument
CELH is described by GuruFocus’ GF Value framework as significantly undervalued versus its GF Value estimate. That spread reflects two things simultaneously: genuine growth at scale and a market that refuses to pay a full multiple until the CELSIUS brand recovery is proven in consumption data, not just management commentary.
Fuel and aluminum inflation are not unique to energy-intensive beverage manufacturing. Packaged-food companies absorbing the same freight and commodity surge face their own gross-margin reckoning without a high-growth brand to offset it.
The company is finalizing selected international markets for Alani Nu launches in 2027 and expects non-U.S. markets to account for more than 15% of total revenue over the next five years. CELSIUS brand international revenue increased 78% to approximately $41.0 million. That is a legitimate long-cycle growth lever. But it starts from a small base.
Scenario Framework
Bull: CELSIUS brand consumption stabilizes by Q1 2027, Alani Nu sustains 40%+ retail growth excluding seasonal items, aluminum costs ease, and gross margin recovers toward 50%. CELH re-rates toward $55-$60.
Base: Alani Nu continues carrying the revenue line, CELSIUS brand recovers slowly through 2027, gross margin holds the high-40s range, and the stock drifts in the $30-$38 band pending brand-level proof points.
Bear: Witch’s Brew volumes normalize sharply in Q4, CELSIUS retail share erodes below 9%, and aluminum inflation persists. Gross margin breaks below 45%. The stock revisits $22-$25.
Tactical Framework
The company is restructuring into three brand-led business units: Celsius, Alani Nu, and Rockstar and Emerging Growth, each led by a dedicated Brand President. Execution risk in that transition is not priced. Watch Q4 CELSIUS consumption data in tracked channels as the first real test. The 9.1% dollar share floor matters. A break below it reopens the bear case fast. The company repurchased approximately $44.5 million of shares in the quarter, which provides modest technical support but does not resolve the brand question.
The Q4 consumption data watch is exactly the kind of post-earnings confirmation setup that separates reactive traders from prepared ones. Waiting for tracked-channel signals after the report rather than betting on the print itself is the discipline that avoids the beat-and-bleed outcome.
Preparation here means knowing which brand is doing the work and monitoring whether management’s restructuring delivers measurable momentum by February’s Q4 results.