There’s a market signal that shows up around 9:35 AM that most traders completely overlook.
They’re watching RSI.
Moving averages.
Candlesticks.
Trying to figure out where the market is headed next.
Meanwhile, I’m watching what happens in the first few minutes after the opening bell.
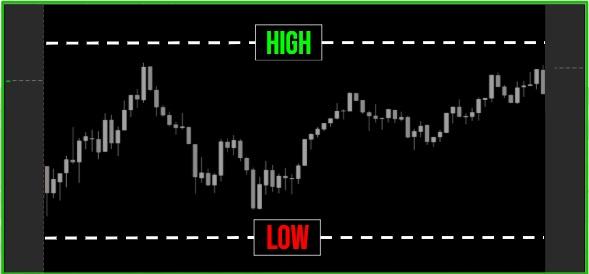
Because that’s where I’ve found a recurring pattern that can help identify key levels above and below the market.
I’ve spent years tracking this behavior.
And over the past two years, we’ve seen this approach produce 618 winning signals.
Now there’s a new test on the table.
Can we get to win #618 before the weekend?
I’ve set a challenge in motion to find out.
No trading guarantees, of course…
But I can show you the data behind the setup, the levels I’m watching, and exactly what I’m looking for as we make our run from #618 toward #620.
If you want to follow along the Challenge, I’ve laid everything out right here.
See you in the market,
Chris Pulver
Birkenstock Holds 93% Full-Price in Europe. The Stock Hasn’t Noticed.
Consumer discretionary is a sector where discounting tells you almost everything you need to know about brand health. By that measure, Birkenstock stands apart from the rest of its peer group in a way that the stock price, sitting near a 52-week low of $29.93, has yet to reflect.
The Pricing Discipline Others Can’t Match
In Q3 fiscal 2026, Birkenstock maintained 93% full-price realization in Europe even as management noted that the broader market had grown materially more promotional. That is not a rounding error. Most apparel and footwear brands operating in a soft consumer environment default to markdowns to move inventory. Birkenstock is managing scarcity and channel discipline instead.
DTC revenue accelerated to 16% growth in constant currency, outpacing B2B in the quarter. Owned retail revenue surged 50% as the company opened 13 new stores in the quarter, with same-store sales running in the high single digits. China grew more than 50% and management described it as the company’s highest-average-selling-price market.
The Numbers the Market Is Discounting
Q3 revenue came in at €720 million, up 15% in constant currency, at the high end of the company’s full-year constant-currency growth target. Management raised full-year targets to 15% constant-currency revenue growth and adjusted EBITDA of at least €710 million, with reported revenue expected at the high end of the €2.30 billion to €2.35 billion range. Adjusted EPS rose 19% to €0.74 in the quarter. The consensus analyst price target sits at $50.90, roughly 39% above where BIRK closed on November 11, 2026 at $36.61.
Adjusted gross margin of 59.2% was down 130 basis points year over year, primarily due to foreign exchange translation and incremental U.S. tariffs. Full-year adjusted gross margin guidance of 57% to 57.5% remains well above what most footwear peers report.
Scenario Framework
Bull case: Q4 results on December 10 confirm full-year revenue at the high end of the guided range, DTC mix continues expanding over time, and the dollar weakens enough to ease the FX drag that has suppressed reported earnings. BIRK trades back toward $50.
Base case: Revenue lands at approximately €2.35 billion for the fiscal year, adjusted EBITDA clears €710 million, and the stock gradually closes the gap to its $50.90 consensus target over the next two to three quarters as FX headwinds moderate. BIRK trades in the $40 to $46 range.
Bear case: A material deterioration in U.S. consumer spending or escalating tariff friction compresses margins below the 57% guided floor, inventory builds beyond the current 37% inventory-to-sales ratio, and DTC deceleration signals the full-price discipline is cracking. BIRK retests the $29.93 52-week low.
The contrast with Birkenstock’s channel discipline is sharpest when set against a peer that abandoned it. Nike’s distribution strategy has undermined its own pricing power in ways that took years to fully surface.
Active Trader Considerations
BIRK trades below its 200-day moving average with its December 10 earnings date as the next hard catalyst. Traders sizing exposure ahead of that release should monitor whether full-price realization stays firm, and whether China’s 50%-plus growth trajectory stays intact. The forward P/E near 14x is directionally plausible for a brand compounding revenue at 15% with roughly 59% adjusted gross margins, but that multiple depends on which estimate set and price point you are using.
Disciplined positioning means respecting the technical floor at $29.93 and understanding that the December results are binary: a beat strengthens the thesis, a revenue miss or margin guide-down reopens the low. Preparation is the trade here, not momentum.