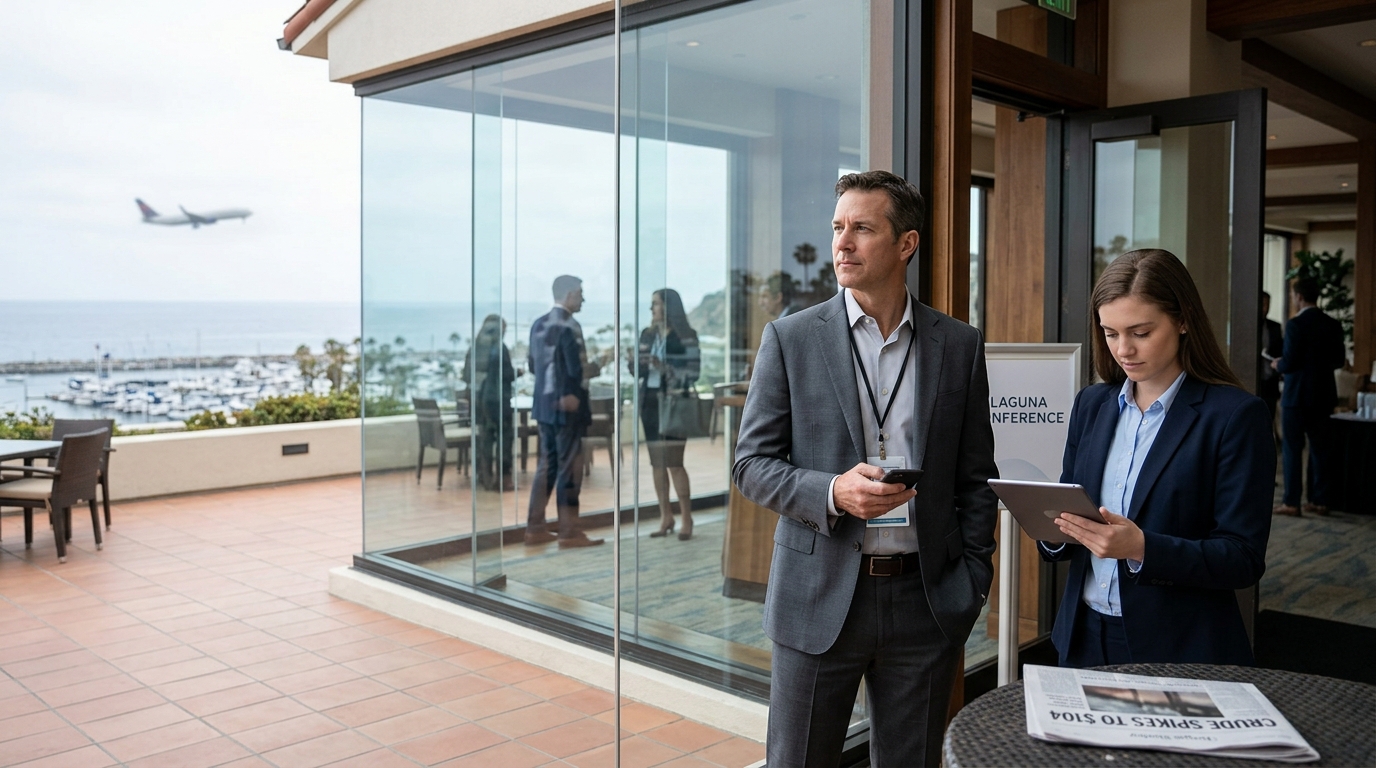
Brent crude closed Thursday at $104.42 a barrel. On Friday it briefly topped $108. U.S. diesel crossed $6 a gallon on average for the first time. And in three days, Delta Air Lines (DAL) executives walk into the Morgan Stanley 14th Annual Laguna Conference in Dana Point, California, to explain why $6.50 in full-year earnings per share is still a credible floor.
In case you missed it… make sure you get your free “Simple Options Trading For Beginners” book before your link expires.
I eventually plan to charge money for this training, so do yourself a favor and download it now…
That way, no matter what it costs in the future, you’ll have a free copy.
Sound good?
That answer had better be thorough. The energy environment has moved sharply since Delta issued its July guidance, and traders are paying close attention.
Market Context
The Strait of Hormuz conflict has reset crude oil’s structural range. Brent averaged $91 per barrel in August, $7 higher than July, according to the EIA’s September 2026 Short-Term Energy Outlook. The agency now forecasts the benchmark around $90 per barrel for the second half of 2026 as its base case, but front-month contracts traded above that level this week amid fresh disruption headlines. Over the past month, the benchmark is up more than 17%.
Diesel told an even sharper story. The national average hit about $6.06 a gallon on September 11, 2026, per AAA, the first time that threshold has been crossed. That is not just a trucking problem: the U.S. ultra-low-sulfur diesel crack spread hit an intraday record of $108.02 per barrel in early September, and jet fuel, which prices off similar distillate economics, is running in lockstep.
The Delta Financials
When Delta reported Q2 2026 results on July 10, the numbers were striking in both directions. Adjusted operating revenue hit about $17.7 billion, up 14% year over year. Adjusted EPS came in at $1.56. Loyalty revenue grew 19%, premium corporate sales climbed 25%, and demand showed no evidence of fare elasticity.
The other side of the ledger was equally notable. Adjusted fuel expense was about $4.4 billion for the quarter, at an adjusted fuel price of $3.93 per gallon, the highest quarterly fuel expense in the airline’s history. Delta still produced $1.4 billion in pretax profit.
Is the Declaration of Independence Missing its Most Valuable Page?
For 250 years, almost nobody noticed what Joel Litman believes America’s founders left unfinished. Today, he says that forgotten blueprint could help determine where the next $10 trillion of wealth is created.
Against that backdrop, CEO Ed Bastian reaffirmed the full-year EPS range of $6.50 to $7.50 and free cash flow of $3 billion to $4 billion. For Q3, management guided to mid-teens revenue growth, operating margin of 11% to 13%, and EPS of $2.00 to $2.50. Delta burns approximately 4 billion gallons of fuel annually, meaning each $0.10 per gallon shift in jet fuel carries roughly $100 million in annualized cost. With per-gallon fuel costs running near $4 entering Q3, the math on the low end of that EPS range is compressing.
One buffer the market is pricing: Delta’s Monroe Energy refinery provides partial insulation on crack spreads that rivals American and United do not possess. Goldman Sachs forecasts U.S. diesel refining profits at $63 per barrel extending into 2027, suggesting that structural advantage may be more valuable than usual.
Sector and Competitive Positioning
Delta’s willingness to hold guidance put it in a distinct category after Q1. American and United both lowered full-year targets; Alaska and JetBlue suspended theirs outright. That divergence reflected genuine structural differences: Delta’s revenue diversification, with more than 50% of revenue from non-main-cabin sources, gives it cost pass-through capacity its peers lack.
United CFO Mike Leskinen presents at Laguna on September 16. Southwest CFO Tom Doxey follows the same day. The sequential positioning means Delta, which is scheduled earlier in the conference, will set the tone for how the sector frames the fuel conversation this week.
Technical Framework
DAL traded at $79.80 on September 12, inside a 52-week range of $55.03 to $95.68. The stock is roughly 16% below its early-July peak and sits between the 50-day and 200-day moving averages on most charting intervals. Volume on September 12 came in at 4.77 million shares against a daily average of 5.15 million, suggesting limited conviction ahead of the conference. A clean guidance reaffirmation at Laguna would put the $85-$86 zone back in view, while downward revision language would likely retest the August low near $77.
Scenario Modeling
Bull Case
Brent stabilizes below $95 as Hormuz diplomatic talks in Oman gain traction. Delta confirms Q3 trends tracking the high end of its $2.00-$2.50 EPS range at Laguna. Barclays, which cut its target to $95 from $105 on September 11, reverses the trim. DAL pushes toward $90, closing the gap with the consensus analyst target of $103.81.
Global energy demand is surging and one overlooked power source is quietly returning to the spotlight. New policy support and supply constraints are setting the stage for a surprising shift in the energy markets.
Base Case
Crude stays in the $95 to $110 range through year-end. Delta holds its $6.50 full-year floor but guides toward the lower half. Q3 operating margins land near 11%. DAL trades in a $77 to $88 range as bulls accept reduced upside and bears find limited catalyst to press the short.
Bear Case
Hormuz tensions re-escalate, pushing Brent toward $120. Jet fuel per-gallon costs breach $5.00 in Q3. Delta trims full-year guidance, breaking the $6.50 floor that has anchored the investment case since January. DAL revisits the $65 to $68 zone, effectively erasing the post-Q2 recovery.
Active Trader Strategy Framework
The Laguna fireside chat is an event-driven arrangement that warrants pre-positioning discipline rather than reactive trading. Key levels to monitor: $77 as near-term support, $85 as the first resistance zone, and $95 as the level where the street-high target from Barclays becomes relevant again. UBS cut its target to $99 from $112 on September 10; any further analyst target compression before the presentation narrows the risk/reward asymmetry on the long side.
Implied volatility on DAL options tends to expand in the 48 hours surrounding investor conference appearances. Traders using options should account for elevated premiums and the possibility that a guidance hold, rather than a raise, may produce a muted move given how much uncertainty is already discounted in the stock. Position sizing relative to portfolio fuel-exposure concentration matters here, particularly for accounts already long energy sector names benefiting from the same Hormuz dislocation pressuring Delta’s cost structure.
Conclusion
Delta built one of the more compelling full-year guidance defenses in airline history at the Q2 results in July. The energy environment has since made that defense harder to repeat. Brent above $104, diesel at a record, and the distillate crack spread at all-time highs are not conditions the July fuel curve anticipated. What management says in Dana Point this week will either reinforce the $6.50 floor as a structural achievement or signal that the fuel math has finally overwhelmed the revenue offset. Preparation, not projection, is the operative framework going into that session.