September 14, 2026
Bonus Content: McKesson’s $15B GLP-1 Quarter Proves the Margin Story Is Real
New Digital System Threatens Your Money
The biggest financial shift in 50 years just accelerated.
If you have not seen how people are preparing for this, you should.
137 nations – nearly the entire world economy – are building digital currencies to replace the U.S. dollar.
China’s digital yuan processed $986 billion.
India’s digital rupee grew 334%.
The UAE’s Digital Dirham goes live this year.
Russia follows next year.
The most dangerous part is already active:
Project mBridge – a digital payment network that bypasses SWIFT and settles global transactions in seconds.
It cuts out the dollar.
It cuts out U.S. banks.
It cuts out America’s influence.
26 central banks are joining.
This is not a debate.
This is a replacement.
When the dollar loses demand…
markets shake.
purchasing power drops.
retirements take the hit first.
If you have not seen how people are shielding their savings, do it now.
The only assets not tied to this new digital system?
Gold and silver.
You can legally move part of your retirement into physical metals – tax and penalty free.
Here is the quickest way to get ahead of this:
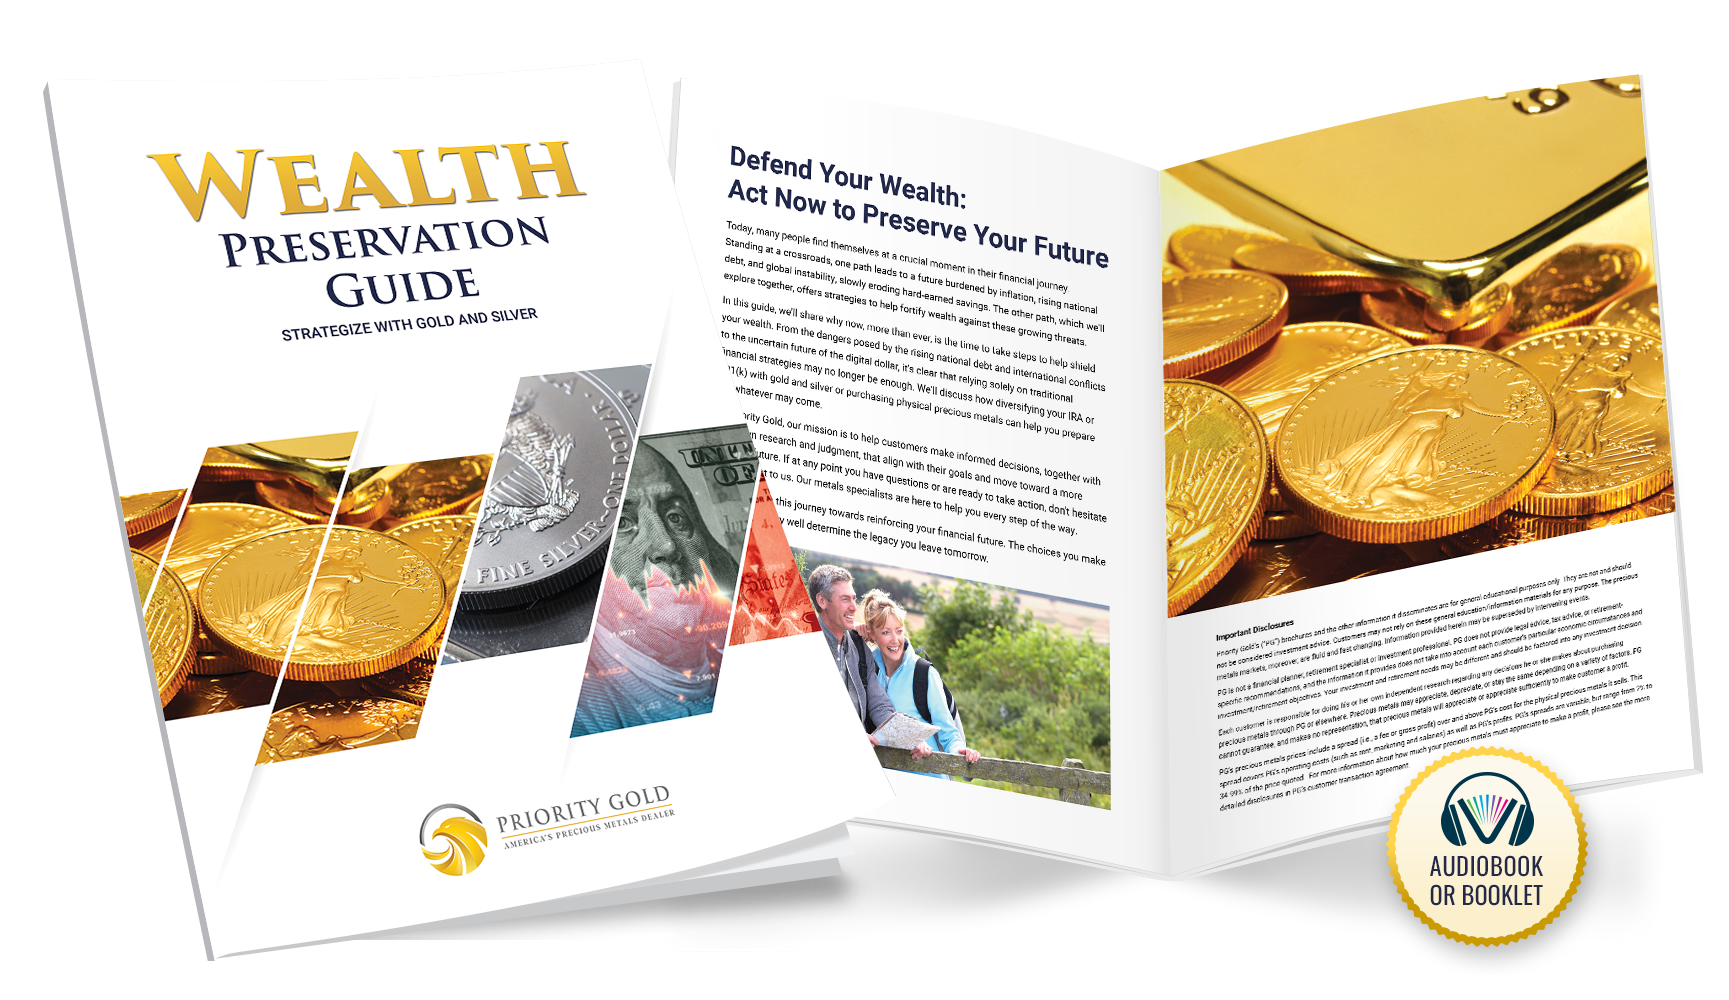
Download Your Wealth Preservation Guide >>
This shift is already happening.
Do not let your savings be the last thing to adjust.
McKesson’s $15B GLP-1 Quarter Proves the Margin Story Is Real
The obesity drug wave is large enough to appear on a $400 billion revenue base. That is the opening fact for traders reassessing McKesson (MCK) heading into Q2 FY2027.
Market Context
GLP-1 therapies generated approximately $132 billion in global sales in 2025, a 33.5% year-over-year increase. Weight-loss indications drove a 131% five-year CAGR. By March 2026, nearly 8 out of every 100 U.S. prescriptions were for GLP-1 receptor agonists, the largest quarterly percentage-point jump recorded since Truveta began tracking the category in 2019. First-time anti-obesity prescribing surged 21.7% between December 2025 and March 2026 alone. The U.S. prescription drug market is on pace to exceed $1 trillion for the first time in 2026, with GLP-1 volume identified as a primary catalyst.
Sector and Company Breakdown
McKesson sits at the center of this volume surge. The company supplies roughly one-third of the domestic drug distribution market, operating alongside Cardinal Health and Cencora in a three-firm oligopoly that collectively covers more than 90% of U.S. pharmaceutical wholesale.
In Q1 FY2027, GLP-1 distribution revenue reached $15 billion, up 24% year over year and 13% sequentially. North American Pharmaceutical revenues rose 5% to $86.8 billion, but adjusted segment operating profit climbed 19% to $894 million, with margin expanding 12 basis points to 1.03%. The revenue-to-profit divergence is the key structural insight: lower branded drug pricing under IRA wholesale acquisition cost reductions compressed reported revenue, while specialty and GLP-1 volumes drove earnings higher. Management confirmed the pricing changes had little effect on operating profit, because more than 95% of McKesson’s branded-drug contracts compensate on a fee-for-service basis.
Total Q1 adjusted EPS rose 20% to $9.93, beating the consensus of $9.44 by 5.2%. Revenue of $105.4 billion topped estimates by approximately 1%. McKesson subsequently raised FY2027 adjusted EPS guidance to $44.20–$45.00. Oncology and Multispecialty posted 33% revenue growth to $14.2 billion and 41% operating profit expansion. On August 25, 2026, McKesson signed a definitive agreement to acquire Precision Medicine Group for $2.25 billion, folding a global contract research organization, biomarker intelligence platform, and biopharma commercialization services into its oncology segment.
Technical Framework
MCK traded near $897 as of September 14, 2026, with the average consensus price target from 22 analysts sitting near $977, implying roughly 9% upside. Post-earnings price target revisions from major desks moved sharply: Evercore ISI to $1,000, UBS to $1,080, and TD Cowen to $1,006. Barclays raised to $1,000 in August and maintains Overweight. Wells Fargo moved to an Equal Weight rating with a $933 target, flagging valuation. Technically, the stock has established a support zone near $788 and a resistance zone approaching $948, based on recent price range analysis. RSI near 34 reflects a stock that has pulled back from post-earnings highs without breaking structural support.
Scenario Modeling
- Bull Case: GLP-1 prescription volumes continue expanding at the current 24% year-over-year pace into Q2 FY2027. The Precision Medicine Group acquisition closes on schedule and management reaffirms FY2027 EPS of $44.20–$45.00. Oncology and Multispecialty revenue growth sustains its 14.5%–18.5% guided range. MCK trades toward the $1,000–$1,080 analyst consensus high.
- Base Case: Volume growth moderates to the 12%–15% range as the Henry Fund’s forward model projects a 12.8% GLP-1 CAGR from 2026 to 2031. Specialty distribution offsets branded pricing pressure and the stock consolidates in the $900–$950 range. FY2027 EPS tracks near the midpoint of guidance at approximately $44.60.
- Bear Case: IRA Part B implementation creates unexpected pricing disruptions, GLP-1 adherence challenges (roughly 28% of obesity patients discontinue within one year) slow net new volume growth, and the Medical-Surgical separation via Wellverse creates near-term earnings noise. MCK tests the $788 support zone with a break inviting further selling toward the $750 area.
Active Trader Strategy Framework
The structure here rewards patience over immediacy. The Q1 earnings reaction confirmed that operating profit leverage on GLP-1 volumes is real, but the guidance raise matched the beat almost exactly, leaving Q2–Q4 expectations unchanged. That arithmetic limits near-term re-rating potential unless volume inflects above current trajectory.
Key levels to monitor: $788 as structural support and $948 as near-term resistance. A sustained move above $948 on volume above the 1.06 million daily average would shift the technical posture constructively. Volatility should be sized around Q2 FY2027 earnings, which will offer the first read on whether GLP-1 momentum can sustain after the record Q1. The Precision Medicine Group closing timeline and any IRA policy developments represent binary catalysts worth tracking on the options surface.
Conclusion
McKesson’s GLP-1 position is not speculative. At $15 billion per quarter and growing at 24%, it is a structural feature of the North American pharmaceutical supply chain. The margin math confirms that scale, not price, drives the profit. Traders who focus only on the revenue line are reading the wrong column. Preparation for Q2 FY2027 means understanding the fee-for-service contract structure, monitoring adherence data, and watching whether the specialty segment’s 19% profit growth holds against the pricing headwinds that will persist through the fiscal year.