September 18, 2026
Bonus Content: Workday Jumps 6% as Reported Buyout Financing Progresses
Marvel was valued at $54 billion. Star Wars at $181 billion. And Pokemon at $115 billion.
What do they have in common? IP with a passionate fanbase.
And that’s great news for companies like Skybound Entertainment.
Skybound is one of the few companies that have successfully struck deals with major streamers and studios while keeping 250 of their own IP properties and the profits across gaming, merchandise, and licensing.
The opportunity to own a piece of it closes soon.
Here’s how they use that IP to create global franchises: They create the comics, where audience response helps shape their next breakout hits, then scale the strongest stories through TV and film, and monetize through releasing games, merchandise, and more. The Walking Dead and Invincible are just two big names in their portfolio.
Now you can own a piece of what’s next. Final days to invest before the opportunity ends.
Workday Jumps 6% as Reported Buyout Financing Progresses
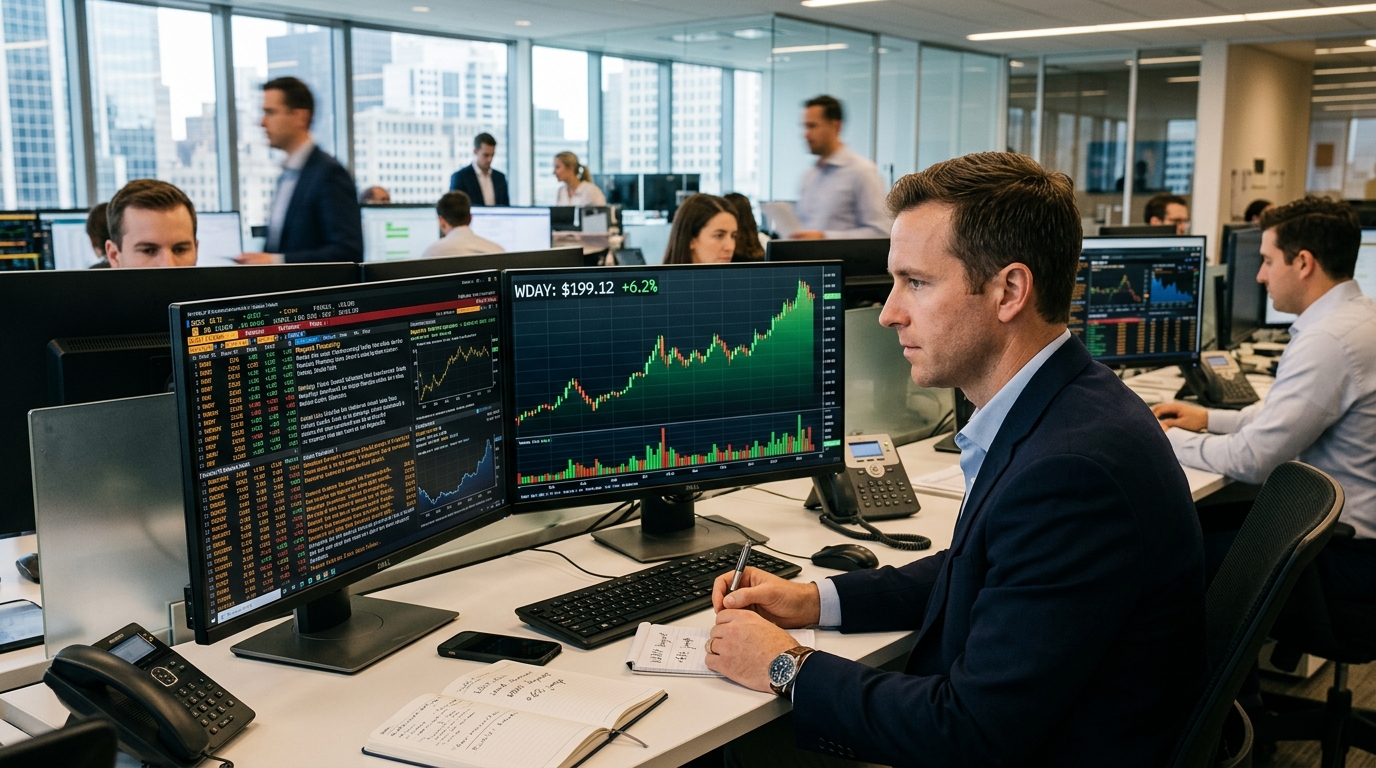
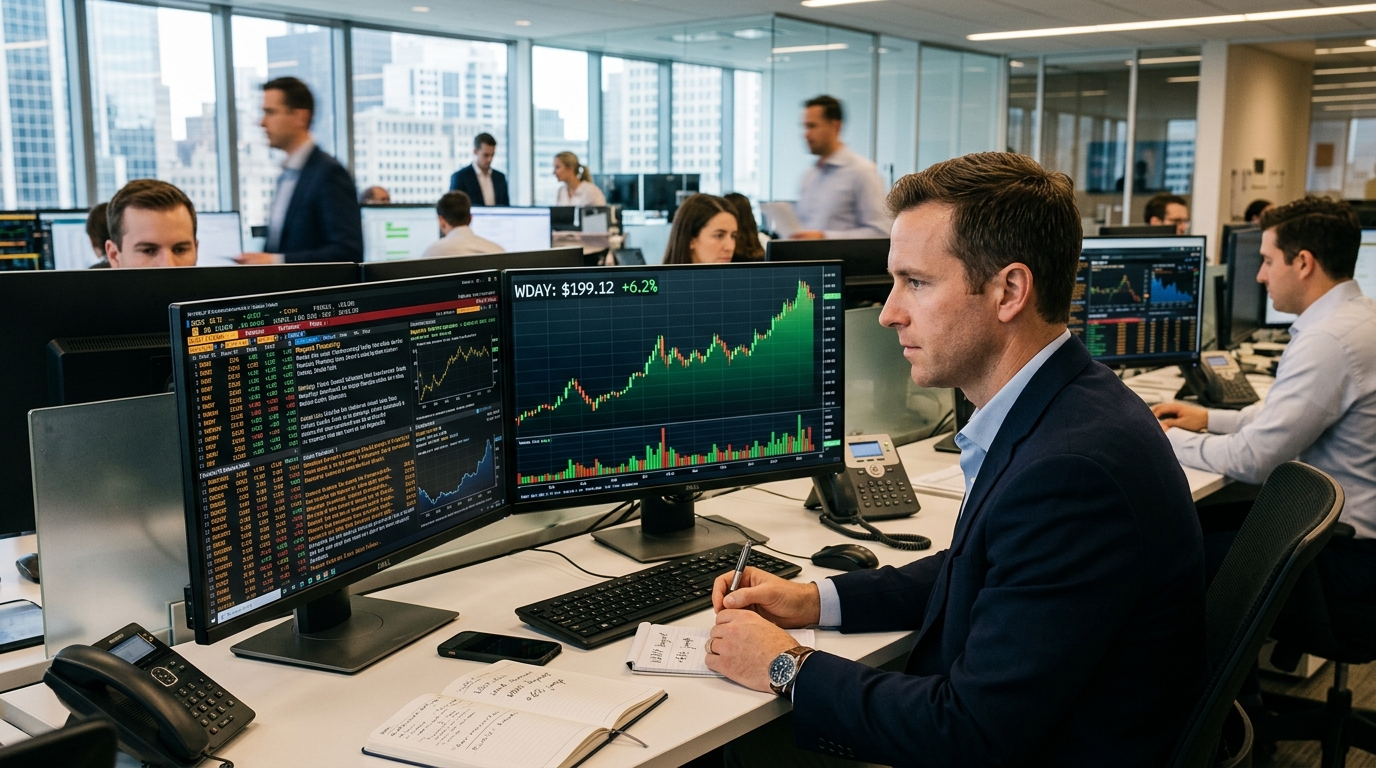
On Thursday, Workday (WDAY) traded as low as $183.61 and finished near $199, a move of roughly 6% on volume of about 4.25 million shares. CNBC’s David Faber reported that financing packages are being provided and equity is still being raised in size for a Silver Lake take-private, and that he was hearing more optimism the deal can happen. That is not a confirmed transaction. It is something more actionable for active traders: a large-cap software name moving on deal-financing chatter at roughly 60% above normal volume, still sitting about 20% below its $249.85 52-week high.
What the Financing Structure Tells You
Silver Lake is in talks to take Workday private in a deal that would rank among the largest software buyouts ever. Reuters reported on August 13, 2026 that Workday had a market value of about $43 billion before the report. Conversations have been ongoing for months, and a transaction of that size would almost certainly require Silver Lake to bring in partners. The firm previously teamed with Saudi Arabia’s Public Investment Fund and Affinity Partners on its roughly $55 billion take-private of Electronic Arts.
The tell in software LBO reports of this kind is the financing package and the multiple paid on recurring revenue, since sponsors in this space have historically leaned on subscription cash flows to support leverage. Thursday’s move suggests that the financing piece is consolidating, not collapsing. That distinction matters.
The Financials Sponsors Are Looking At
Subscription revenue grew 16.9% in fiscal 2025, and Workday guided fiscal 2027 subscription revenue growth to roughly 12% to 13%. The firm posted a non-GAAP operating margin of 29.6% for fiscal 2026, a combination of recurring income, double-digit growth, and solid margins that is precisely the profile private equity buyers favor. Valuation framing in deal chatter matters, but specific multiples move with the tape and with how you normalize EBITDA for stock-based compensation and acquisition-related items. The cash flow point is still the core one for traders: Workday guided to operating cash flow of about $3.45 billion and free cash flow of about $3.18 billion for fiscal 2027.
Buyout firms have largely stayed out of large software take-privates in 2026 as the rise of artificial intelligence has made the future growth and value of traditional software harder to judge. Workday itself has felt that pressure, with shares down year-to-date into mid-September before Thursday and sitting well below their September 29, 2025 52-week high. That compression is exactly what creates the sponsor opportunity: a business with multi-billion-dollar annual free cash flow potential trading at a public market multiple that reflects maximum AI-disruption fear.
Sector Context
Over the past year, relative performance across SaaS has been uneven, with large single-name dispersion and shifting leadership. WDAY’s Thursday close near $199 puts it ahead of its August lows but well below the $206 area it traded around when the initial Reuters report hit in mid-August. The spread between current levels and the 52-week high at $249.85 represents the market’s discount for deal uncertainty. Traders must decide how much of that gap is closeable on financing news alone.
Scenario Framework
Bull Case
Financing is formally committed and equity co-investors are named within weeks. WDAY pushes toward $220 to $230, pricing in deal certainty. The broader SaaS group, including CRM and NOW, re-rates upward on the premise that private buyers are floor-setting valuations the public market has abandoned.
Base Case
Financing chatter continues without a formal announcement for another four to eight weeks. WDAY consolidates in the $190 to $205 band, holding the Thursday move but giving back some of the premium as uncertainty lingers. Volume normalizes. The stock remains a headline risk in both directions.
Bear Case
Financing falls apart or Silver Lake walks. The stock reverts toward pre-August levels, the $170 to $175 area, erasing the entire deal premium. Elevated volume on Thursday means a meaningful number of traders entered at $195 to $199; a deal denial would leave that entire cohort offside quickly.
Active Trader Framework
Thursday’s close near $199 on about 4.25 million shares is the reference point. The session low at $183.61 is the level that defines whether this move has merit or gives back ground. Traders holding from below $190 should define their exit around whether volume on any pullback matches or exceeds Thursday’s session. Sustained high volume on down days would be a concerning signal. Take-private chatter of this kind typically follows a familiar sequence: initial sourcing reports, a run-up in the target’s shares toward an implied premium, then either confirmation with financing details or a denial that unwinds most of the move. Position sizing relative to that binary is the only disciplined framework here. The 52-week high at $249.85 is not a realistic near-term target without a formal deal announcement. $220 is the first level worth mapping if the financing story hardens further.
The $43 billion question is whether Silver Lake can close the capital stack. Thursday’s price action says the market thinks the answer is closer to yes than it was 48 hours ago. Preparation, not conviction, is what the moment requires.