You won’t believe what I’ve been seeing almost every Monday at 9:30am.
For 20 years, I’ve been watching the markets.
Seen every pattern you can imagine.
But this one still blows my mind.
Almost every Monday morning… Right when the bell rings…
Certain stocks start doing things that shouldn’t be possible.
Little companies nobody’s heard of…
Have suddenly rocketed 100%… 200%… sometimes 500%.
All on the same day.
Past performance doesn’t indicate future results. And all trading carries risk, of course…
But after years of tracking this anomaly…
There are 4 specific things that happen before these Monday explosions.
And when I see all 4 together?
That’s my cue.
I’ve automated the whole process now.
My scanner watches thousands of stocks every Monday…
Hunting for those 4 signals.
When it finds them… you’ll know immediately.
Because Monday mornings could become your favorite time of the week.
See the Monday pattern that’s been hiding in plain sight
Tim Bohen
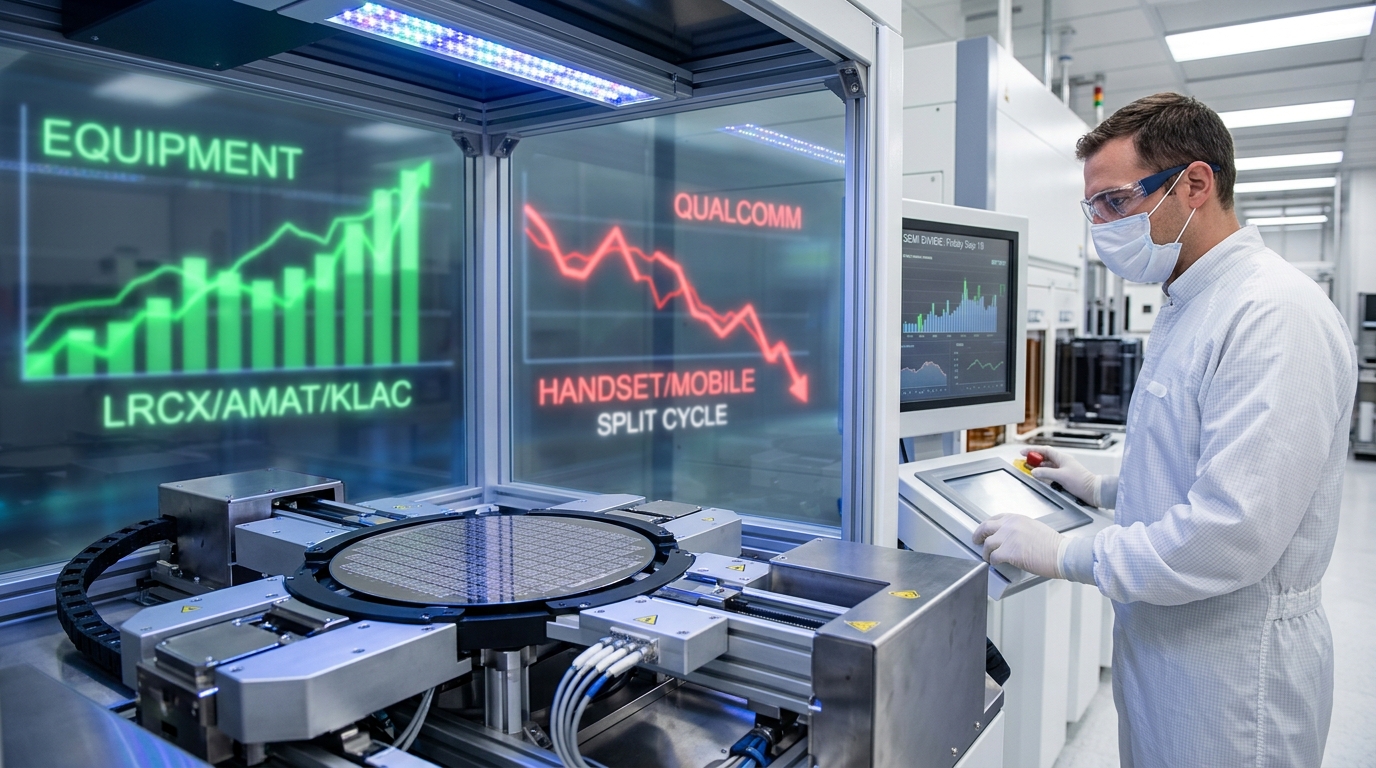
Chip Equipment Ripped. Qualcomm Fell 6%. Same Day, No Company News.
Friday, September 18 handed traders one of the cleaner positioning reads of the year. Lam Research gained nearly 7%, Applied Materials added 6.5%, and KLA rose 4.7%. On the same session, Qualcomm closed at $177.72, off roughly 5.8%, with Skyworks and Qorvo each slipping about 2% to 3%. SOXX closed higher while the S&P 500 was roughly flat.
- LRCX +6.98%, AMAT +6.51%, KLAC +4.74% on Friday with SOXX +2.66% versus SPY +0.13%
- SanDisk closed at $1,791.82 (+10.99%); the move was widely attributed to its upcoming S&P 100 inclusion effective Monday, September 21
- Qualcomm -5.82% to $177.72, reversing a roughly 10% rally over the prior month, with no clear company-specific catalyst
- Micron reports fiscal Q4 on September 30; consensus EPS near $31.16
- DRAM contract prices rose 90% to 95% quarter-over-quarter in Q1 2026 and another 58% to 63% in Q2, per TrendForce
- Lam Research posted $23.23 billion in fiscal 2026 revenue, up 26% year-over-year, with non-GAAP operating margin of 38.4% in the June quarter
- LRCX had pulled back 13% over the prior month despite a 66% year-to-date gain before Friday’s bounce
Two Markets Inside One ETF
Lam Research and Applied Materials led a rally tied to future capital spending plans rather than current chip demand, while SOXX gained about 2.7% and SPY gained 0.1%, confirming the buying was concentrated in the equipment layer, not a broad market move. That distinction matters. Equipment names are pricing forward order books. Qualcomm is pricing handset demand right now, and that demand cycle has different exposure to consumer spending, smartphone replacement rates, and Fed policy.
Qualcomm shed nearly 6% Friday in positioning-driven profit-taking, while RF peers Skyworks and Qorvo slipped just 2% each, with SOXX gaining about 2.7% on the same session, showing that AI data-center chip demand and smartphone RF demand run on different cycles. Qualcomm’s stock had risen roughly 10% over the prior month, making a 6% reversal on no news consistent with crowded-long unwinding rather than any fundamental deterioration.
The Numbers Behind the Equipment Side
Lam Research recorded annual revenue of $23.23 billion for fiscal year 2026, a 26% gain year-over-year, with quarterly revenue of $6.72 billion in the June quarter, up 30% from a year earlier. Non-GAAP gross margin for the June quarter came in at 52.0% of revenue, with non-GAAP operating margin of 38.4%. Even after that fundamental performance, LRCX had dropped 13% in the month before Friday despite holding a 66% year-to-date gain, pointing to money returning to a washed-out group.
SanDisk adds a separate layer. The company posted quarterly revenue of $8.97 billion with gross margin of 71.5%. The headline catalyst was SNDK’s upcoming inclusion in the S&P 100 effective before the open on September 21, which typically forces passive funds tracking that index to buy the stock mechanically on the rebalance.
The Micron Countdown
Everything above is pre-positioning for what arrives September 30. Micron reports fiscal Q4 results on September 30, with consensus near $31.16 per share. The company guided to $50.0 billion in revenue, plus or minus $1.0 billion, when it reported in June. Conventional DRAM contract prices rose 90% to 95% quarter-over-quarter in Q1 2026 and another 58% to 63% in Q2, per TrendForce. TrendForce has forecast that price increases may moderate to 13% to 18% in the third calendar quarter. At roughly $975 per share, Micron trades near 7.9 times annualized earnings implied by its most recent quarterly guidance, a multiple that says the market does not expect this level of profit to persist.
Friday’s equipment rally is partly a bet that memory tightness sustains capex commitments through 2027. The Qualcomm decline reflects the opposite read on consumer demand and RF pricing power.
Scenario Framework
Bull Case. Micron confirms HBM demand strength on September 30, DRAM pricing holds above TrendForce’s moderation base case, and equipment order books extend into 2027. LRCX reclaims the $320 to $340 range, SNDK consolidates above $1,800 on index inflow support, and QCOM stabilizes near $175 as handset seasonality improves into Q4.
Base Case. Micron meets consensus but guides cautiously on DRAM price moderation. Equipment names hold most of Friday’s gains but stall at resistance. QCOM trades in the $170 to $185 band as the RF trade rebuilds slowly. SOXX range-trades between $520 and $545 into the report.
Bear Case. Micron misses on margins or guides below consensus, reigniting concerns about the memory cycle peak. Equipment names retrace the September bounce sharply, with LRCX vulnerable back toward the $250 to $260 zone. QCOM breaks below $170 if handset data weakens simultaneously.
Active Trader Considerations
The long equipment / short handset RF spread has a clean structural logic right now, but position sizing matters given that both legs carry the same macro risk: a Fed that has seen market-implied odds of an additional 2026 rate hike rise sharply under Chair Kevin Warsh, which pressures high-multiple growth names across the semiconductor complex without discrimination. LRCX’s 13% September drawdown before Friday’s bounce is a reminder that momentum can unwind fast in this group. Monitor SOXX $520 as the key support level and Micron’s September 30 report as the event that resolves the split. Preparation, not prediction, is the edge.