September 18, 2026
A cyberattack, EP share losses, and a $14.5B acquisition have reset every assumption traders had about Boston Scientific’s margin story.
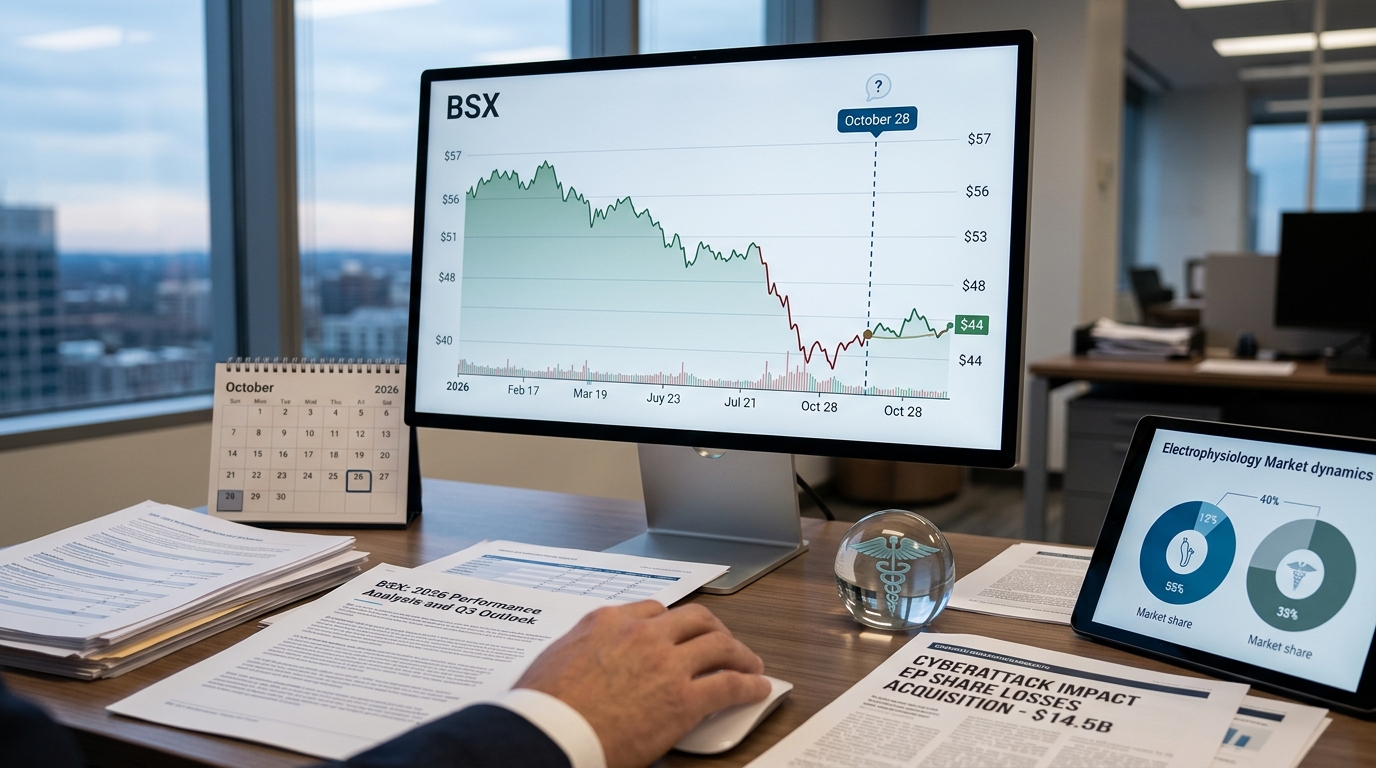
Boston Scientific traded near $57 at the start of 2026. As of mid-September it sits around $44, a decline of roughly 23% year to date. The stock has recovered modestly off its lows, but the question ahead of Q3 earnings on October 28 is whether the bear case is already priced or whether the company still needs to clear several compounding hurdles before the numbers stabilize.
In at 9:35 AM. Out by 10.
I call it the “Opening Bell Breakout.” It’s the same setup I used to catch moves like 113% on GOOGL and 240% on META. I trade one simple 15-minute window each morning – and I’m usually done by 10 AM.
The deterioration unfolded in layers. Electrophysiology, once BSX’s growth engine, hit a ceiling faster than management anticipated. Pulsed field ablation fueled the EP portfolio to triple-digit growth rates in prior years, but increased competition from Medtronic, Johnson and Johnson, and Abbott ate into that success. PFA now accounts for a large majority of ablation procedures in the U.S., which limits the company’s ability to offset competitive pressures through market conversion alone.
In Q2 2026, EP grew 9% overall, but the split mattered: international EP expanded 23% while U.S. growth came in at just 3% due to competitive share movement. For the second half of 2026, BSX now expects flat global EP growth. That is a sharp reversal from a business that was posting triple-digit rates two years ago.
The financial frame around those headwinds is significant. Q2 revenue came in at $5.442 billion with 7.5% reported growth, adjusted gross margin of 70.3%, and free cash flow of $1.29 billion. Those are not weak numbers in isolation. The problem is guidance. Full-year reported sales growth was cut to 5.5% to 6.5% from a prior range of 7% to 8.5%, and adjusted EPS guidance fell to $3.28 to $3.32 per share from $3.34 to $3.41. Then a cyberattack in late August added another layer of uncertainty. Operations have been restored, but the company has not said that prior Q3 or full-year targets will be met following the disruption.
The 60-Second Change That Stays With You
One small setting could change how you enter and exit every options trade. It’s easy to overlook, but many beginners learn its importance the hard way. Discover the permanent rule inside Your First Trade Playbook – free for a limited time.
The Restructuring and the Acquisition
BSX announced a restructuring program targeting $500 million in run rate savings by 2029, with over half realized by end of 2027. That signals management knows the margin expansion that investors were counting on is delayed. The company reduced expected adjusted operating margin expansion to 0 to 25 basis points from its prior 50 to 75 basis-point range.
Layered on top is the Penumbra deal. Boston Scientific agreed to acquire Penumbra in a cash and stock transaction valued at approximately $14.5 billion. The acquisition adds a neurovascular device portfolio addressing stroke-causing blood clots and pulmonary embolism. Strategic rationale is sound. The timing, against a backdrop of a steep stock drawdown and a reduced guidance range, is what traders need to price.
Scenario Modeling
Bull Case: FARAFLEX, the next-generation large focal ablation catheter, progresses through development and becomes a meaningful growth driver later in the decade, reigniting EP growth. Penumbra integration runs cleanly, restructuring savings arrive ahead of schedule, and the 23% international EP growth rate holds. The average analyst price target sits near $66. A return to that level implies roughly 50% upside from current prices.
Base Case: Q3 revenue grows at the low end of the original 3% to 5% organic guidance range. Penumbra closes in Q4, adding near-term debt but eventual revenue diversification. EP remains flat through year-end. Meaningful improvement does not arrive until 2028.
America’s Debt Just Crossed a Line No Nation Has Ever Crossed Yet
US Treasury data puts the national debt near $40 trillion, with borrowing costs at some of their highest levels in years. History suggests governments rarely cut their way out of debts this size. They quietly inflate instead. It may be why central banks keep adding gold at a historic pace. A free Precious Metals Retirement Guide explains what the shift may mean for savers and how to prepare early.
Request your FREE Precious Metals Retirement Guide today and see how prepared savers stay protected.
Bear Case: The cyberattack disrupts Q3 revenue more than the recovery suggests, the Penumbra integration absorbs management bandwidth, and WATCHMAN and U.S. electrophysiology continue to weigh even after the attack is resolved. Shares retest the low $40s ahead of earnings.
Active Trader Framework
October 28 is the first real data point after the cyberattack disruption and the pending Penumbra close. Traders should track the U.S. versus international EP revenue split for any inflection in domestic share losses, free cash flow conversion against the $3.8 billion full-year target, and any updated commentary on Penumbra timing. One recent sell-side note has cited a $56 price target while maintaining an Outperform-style view. That spread between cautious near-term targets and bullish structural views is exactly where disciplined positioning lives.
Preparation here means knowing which catalyst moves the stock in which direction, not guessing which scenario wins. BSX is a turnaround story that still needs to prove its own timeline.