September 26, 2026
Bonus Content: The Fed Just Hiked. Two Data Releases This Week Decide October.
Dear Reader,
The Trump Administration is buying up stocks.
They bought Intel… Up almost 100% in three months
MP Materials… Up 216% in 4 months.
Trilogy Metals… Up 388% in 8 days!
Now, an Ex-CIA economist is saying the Trump administration could be about to target a new $5 stock.
He bought 10,000 shares himself.
And he reveals exactly why he did it right here.
Good investing,
Rachel Gearhart
Publisher, The Oxford Club
The Fed Just Hiked. Two Data Releases This Week Decide October.
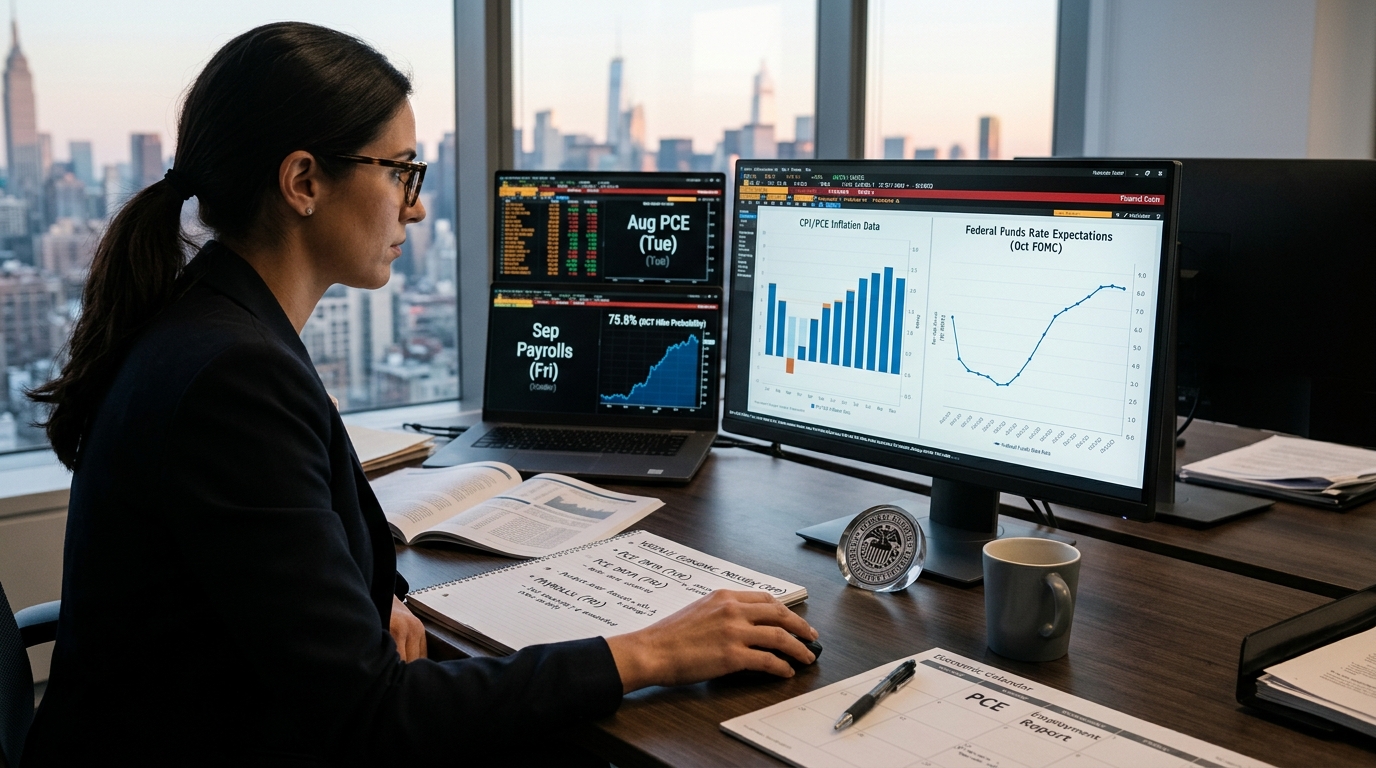
The Federal Reserve lifted rates for the first time since 2023 ten days ago. Now the market is pricing a 75.8% probability of a follow-up 25bp hike at the October 27-28 FOMC meeting, before a single piece of data from the new cycle has been published. That gap closes this week. Two releases, August PCE on Tuesday and the September employment report on Friday, constitute the entirety of the fresh evidence Warsh’s committee will have before it decides whether to move again.
Position accordingly. This is not a week to wait for the dust to settle.
Market Context
The September 16 decision was unanimous. The Fed took the target range to 3.75%-4.00% and Chair Kevin Warsh framed it not as tightening but as removing “a dose of accommodation”, language that left Wall Street wondering where removal ends. The Fed’s own projections pegged 2026 headline PCE at 3.7% and core at 3.4%, both above target, signaling the committee does not consider the job finished.
Bond markets have already delivered a verdict. The 10-year Treasury yield hit 5.18% this week, while the 2-year note trades near 4.90%, pricing in a policy rate that goes higher still. The 30-year bond briefly touched 5.47%. TLT has become a live referendum on hike expectations every session.
Against that backdrop, the S&P 500 closed Friday at 7,742, sitting above its 50-day moving average of 7,636 but carrying a duration risk that has grown quietly heavier all year. The equity market’s decoupling from bonds cannot survive another significant yield leg higher if payrolls come in firm.
Sector Breakdown
Small caps are the most direct casualty of this rate path. IWM is down roughly 4% month-to-date, and its correlation with TLT has surged to 0.51, nearly double the 0.29 correlation SPY carries. As Schwab’s Kevin Gordon noted, small caps’ negative correlation to the 10-year yield is twice that of large caps. Rate-sensitive names in financials, homebuilders, and biotech carry the same exposure. Until TLT stabilizes, capital rotation into IWM is structurally impaired.
Mega-cap technology remains the counterweight. QQQ gained more than 3% last week as semiconductor breadth surged, temporarily masking the narrowness underneath. SPY looks constructive only because of that concentration. Confirm whether it holds.
The Two Releases That Matter
Tuesday, September 30, 2026, August PCE: Consensus sees headline PCE rising 0.4% month-over-month, doubling July’s 0.2% pace. July’s year-over-year reading was 3.7% headline and 3.3% core. A 0.4% monthly print sustains or accelerates those annual rates. This is the Fed’s preferred inflation gauge and, combined with the BEA’s final Q2 GDP revision published the same morning, gives the committee a full picture of the summer’s inflation trajectory. A hot number makes October nearly certain.
Friday, October 2, 2026, September payrolls: Consensus sits near 100,000 after August’s 162,000 surprise. FXStreet economists expect 90,000. Unemployment is seen holding at 4.1%. That three-month moving average is already at 71,000, well below the pre-hike pace. A miss toward 70,000-80,000 with rising unemployment injects genuine ambiguity into the October decision. A beat above 130,000 locks it in.
Technical Framework
TLT is the instrument that links every rate-sensitive asset this week. Watch whether it can hold the low established after the September 16 hike; a break lower means yields extend, and IWM/XLF unwind accelerates. SPY’s 50-day at 7,636 is the level that separates constructive from deteriorating. A post-PCE spike in yields that pushes SPY below that level on meaningful volume warrants a reassessment of risk sizing.
On the short end, the 2-year yield at 4.90% is the real-time hike probability barometer. A move through 5.00% before Friday signals the market is absorbing a hot PCE and front-running a firm payroll number simultaneously.
Scenario Modeling
Bull case: PCE headline comes in at 0.3% or softer. Payrolls print at 80,000-90,000 with unemployment ticking to 4.2%. October hike odds slide below 55%. TLT recovers 2-3 points, IWM outperforms, and rate-sensitive sectors lead a broadening rally. SPY tests 7,800.
Base case: PCE at 0.4% as expected. Payrolls near 100,000 with unemployment steady at 4.1%. October odds hold around 70%-76%. Rates stay elevated, SPY consolidates between 7,636 and 7,750, IWM remains under pressure. The hike happens in October and December odds stay near 95%.
Bear case: PCE above 0.4% and payrolls rebound above 130,000. October hike becomes near-certain, December hike is fully priced. The 10-year yield breaks above 5.25%, TLT sets a new low, and SPY retests its 200-day near 7,205. IWM breaks through its September low.
Active Trader Strategy Framework
The asymmetry this week favors positioning before Tuesday rather than waiting for Friday. PCE prints before the equity open; the initial yield move in the first 30 minutes will set the tone for rate-sensitive names all session. Sizing into that volatility without defined risk levels is the mistake most traders make on binary data days.
Monitor TLT at current levels as the regime signal. A breakdown in TLT alongside a hot PCE is a risk-off environment for duration-heavy equities, not a buying opportunity. IWM put activity has been elevated, open interest in puts is running nearly double that of calls, reflecting institutional hedging rather than speculative shorts alone. That skew can amplify downside momentum quickly if payrolls disappoint the bear case.
Warsh has explicitly rejected forward guidance. The data this week is not just an input, for this committee, it is the decision.
Conclusion
Preparation, not prediction, is the edge this week. The levels are clear, the catalysts are scheduled, and the range of outcomes is wide enough to matter for positioning across equities, rates, and volatility. Traders who define their response to each scenario before Tuesday open will be in a far stronger position than those reacting in real time to an 8:30 print with a hot 10-year yield and an illiquid bond market.