Dear Reader,
The Trump administration has been pumping massive cash into small resource companies lately…
Companies vital to national security.
As you can imagine, these “government targeted” stocks have soared in value.
Just look at the results:
Trilogy Metals – up 388% in 8 days.
MP Materials – up 216% in 4 months.
Lithium Americas – tripled in 3 weeks.
And America’s Economist, Dr. Mark Skousen, says it’s about to happen again.
Keep in mind… Skousen knows the President personally after Trump spoke at his FreedomFest conference.
And he’s also developed close relationships with Senators Rand Paul, Mike Lee, and others.
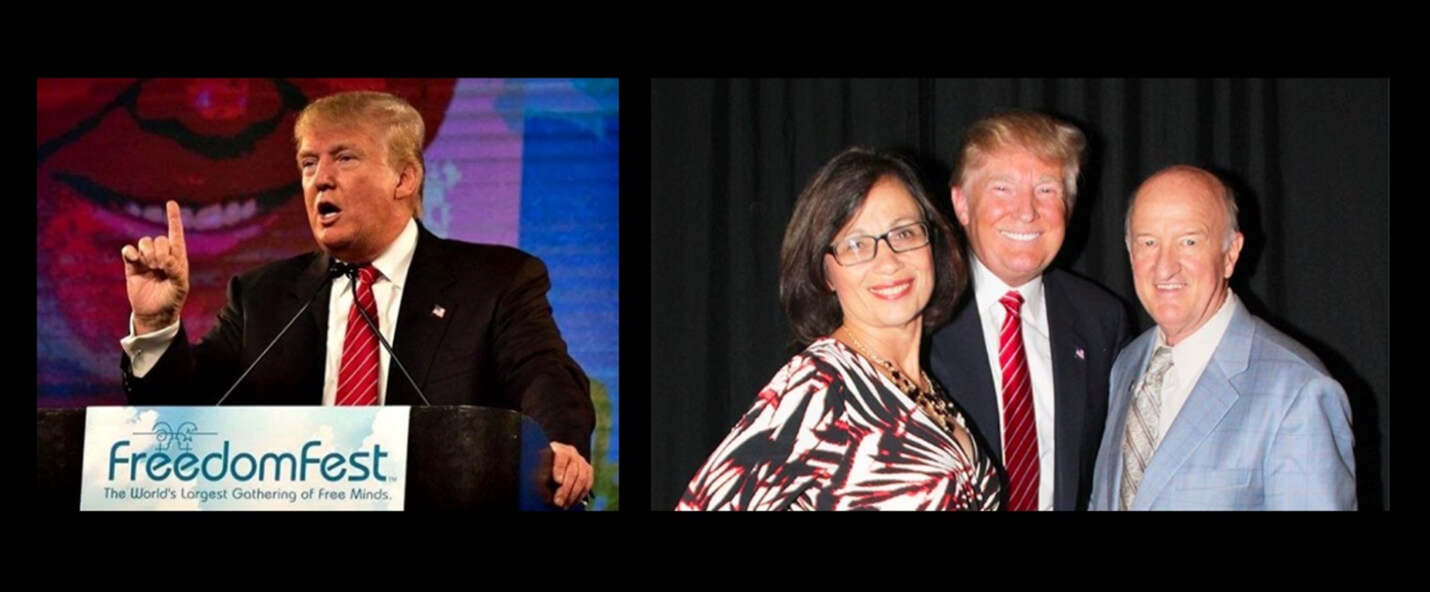
He’s learned what’s important to them.
And one thing they’ve made clear.
The current administration will take stakes in companies they deem important to national security.
Now, Dr. Skousen says he believes it will happen again.
This time with a much smaller company.
And in anticipation, he’s purchased 10,000 shares of his own.
Here’s why…
This company is the only domestic producer capable of delivering one strategic mineral America can’t do without.
That’s why Tesla just signed a binding agreement to purchase 75,000 metric tons from this company.
And it’s why the government has already handed the company grants totaling $130 million.
Dr. Skousen believes the U.S. government could take a stake at any moment in the days ahead..
He breaks down the full situation right here – read it before this stock makes headlines.
Good investing,
Rachel Gearhart
Publisher, The Oxford Club
P.S. The last time Mark felt this way about a resource stock, he turned $50,000 into a rare $1.3 million over just three years. Don’t sit on this one.
September Jobs Numbers Drop at 8:30. What Moves the Fed.
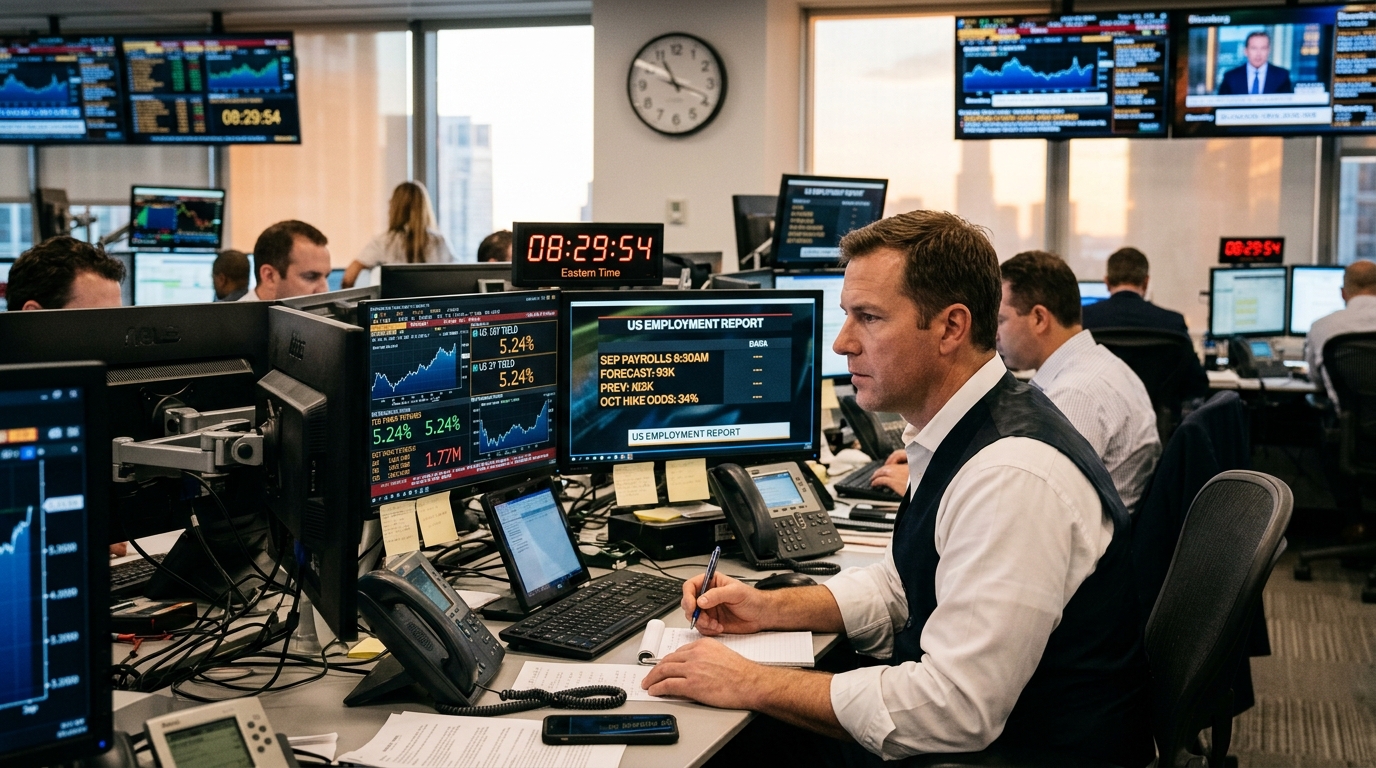
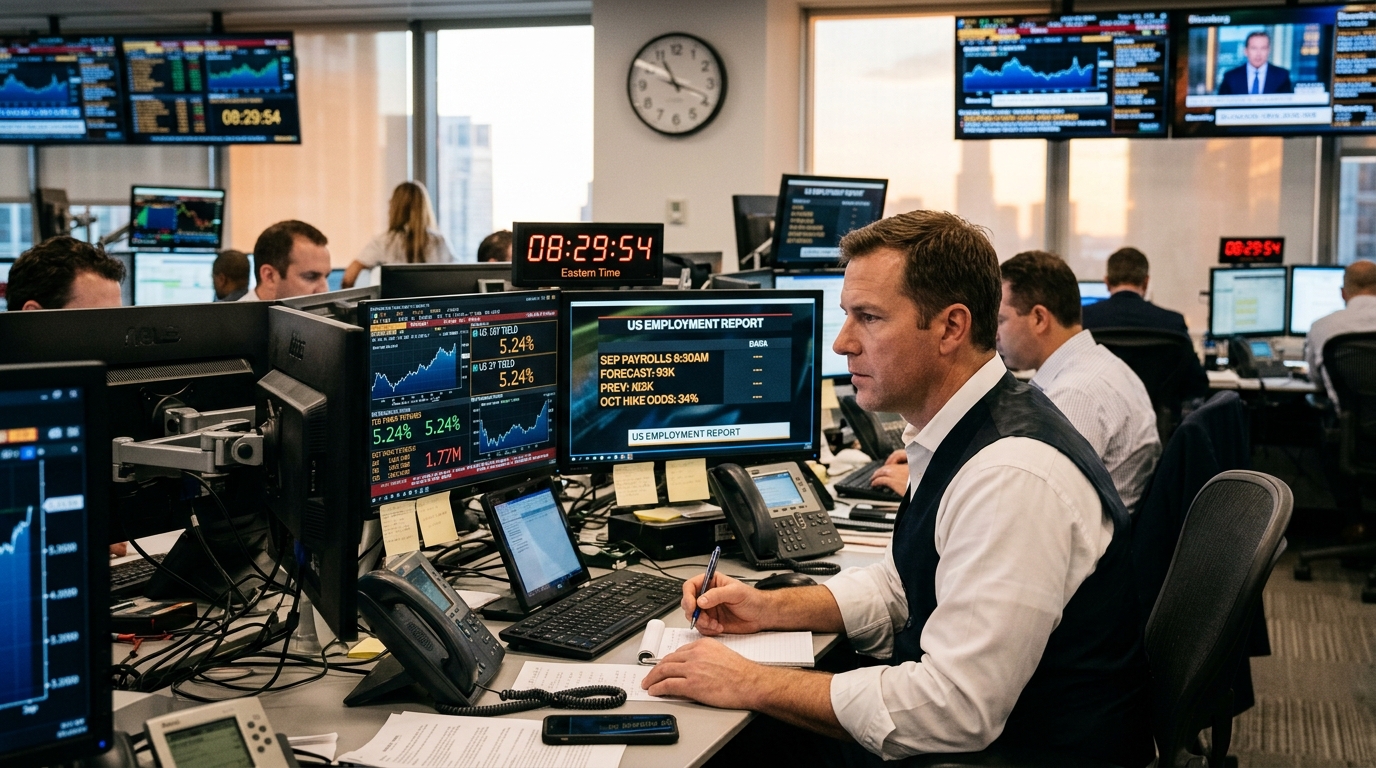
The Bureau of Labor Statistics releases the September Employment Situation report at 8:30 a.m. Eastern this morning, and the range of plausible outcomes is wide enough to move every rate-sensitive instrument on the board. Forecasters predict the U.S. added about 90,000 to 95,000 jobs in September, a slowdown from August’s unexpected 162,000, according to FactSet. The unemployment rate is forecast to remain unchanged at 4.1%. The spread in sell-side estimates tells the real story: Bank of America expects payrolls to rise by a below-consensus 60,000 in September, including 50,000 in the private sector, while Continuum Economics expects a 100,000 gain, slower than August but still maintaining a healthy trend.
The pre-report signal was mixed. U.S. private employers added 90,000 jobs in September, up from a revised 36,000 in August, according to the ADP National Employment Report released September 30, offering an early sign of firmer hiring before the official figures. Reuters cautioned that ADP has been a poor predictor of the BLS private-payrolls estimate, so the headline should not be treated as Friday’s result in advance. Education and health services added 55,000 positions, and leisure and hospitality gained 22,000, while financial activities lost 16,000 positions and professional and business services shed 11,000. That sectoral divergence matters: concentrated strength in low-wage, service-sector hiring is a meaningfully different signal for the Fed than broad-based gains.
The Rate Trigger Points
The 10-year U.S. Treasury yield touched about 5.34% on Thursday, its highest since 2002, as bets on the Fed’s October rate decision swung between a hold and a hike. It pulled back to about 5.24% on October 1. Futures on the federal funds rate have been consistent with roughly two-thirds odds of a hold at the October 27-28 FOMC meeting, leaving hike odds in the low-to-mid 30% range.
That low-to-mid 30% is not static. Late September saw the market swing meaningfully from leaning hike to leaning hold as incoming inflation and growth data shifted the front-end reaction function. Fed Chair Kevin Warsh’s September rate hike broke a multi-year pause, and investors now face the highest borrowing costs in nearly two decades. The September 16 decision raised rates to a 3.75% to 4.00% range, the first hike since 2023.
Today’s payrolls number is the clearest remaining input before October 28. A reading above 130,000 with unemployment holding at 4.1% would likely push October hike odds back above 50% within the first 30 minutes of trading. A print at or below 60,000 keeps the market leaning hold for October and gives duration room to stabilize. The two-year note, which was around 4.90% in late September, is the most rate-sensitive duration to watch in the first hour.
TLT and SPY in the Crossfire
TLT closed at $77.71 on October 1, sitting on its session low and matching its 52-week low print at $76.76. The fund is significantly below its 50-day and 200-day moving averages of $81.90 and $85.52, respectively, a structural positioning that makes any hawkish payrolls beat easier to extend lower. SpotGamma flagged elevated event risk into the data, with front-end SPX implied volatility around 18.5% for the October 2 expiration versus roughly 14% for subsequent weeks, underscoring payrolls as the near-term volatility fulcrum.
Scenario Modeling
Bull Case (risk assets): Payrolls print between 60,000 and 80,000, unemployment holds or ticks to 4.2%. October hike odds slide toward the teens. The 10-year retreats toward 5.05%, TLT recovers toward $79.50-$80.00, and SPY holds above 775.
Base Case: Payrolls land in the 90,000-100,000 range, unemployment steady at 4.1%. October odds drift in the low-to-mid 30% range, yields stabilize near 5.20%-5.25%, and equities absorb the report with limited directional follow-through.
Bear Case (rates): Payrolls exceed 130,000 or average hourly earnings accelerate beyond 0.4% month-over-month. October odds surge back above 55%. The 10-year retests 5.30%-5.34%, TLT breaks below $76.76 (its 52-week low), and SPY faces downside pressure toward the 740-750 zone where negative gamma conditions begin to amplify moves.
Active Trader Framework
Position sizing matters more than direction today. Volatility around payrolls releases is typically front-loaded: the largest moves in both TLT and SPY tend to occur in the first 20 minutes after the release, then consolidate. Chasing an extension past 30 minutes carries diminishing edge. Monitor the two-year yield in real time as the most direct read on how the market is interpreting the October hike probability shift. TLT’s $76.76 level is the structural line; a close below it on heavy volume would represent a new 52-week breakdown. For SPY, the 775 level is the gamma inflection point flagged by SpotGamma’s work.
Preparation is the only edge available before 8:30. Know the payroll number that changes your view on October, and know where you exit if the market moves against it. The report answers a specific question this morning: does the labor market give Warsh permission to pause, or does it reopen the October hike debate in full?