November 3, 2026
Bonus Content: AutoZone’s Real Growth Engine Is Not the DIY Aisle
Dear Reader,
In 1946, America had just financed the largest war in human history.
Debt-to-GDP hit around 119%… a record.
Last year, debt-to-GDP hit around 123%.
And this time, there’s no world war to explain it.
So how did America get out from under that debt last time?
It never paid that debt off. It grew its way out… the economy expanded for decades until the debt was small next to it.
America’s done it before.
And Washington is betting on growth again. GDP growth driven by AI.
And some of that growth won’t come from people at all.
AI is ALREADY starting to pay for things on its own.
Amazon now lets AI agents pay for tools and content while they work.
How do you think those AI agents are going to transact?
There’s ONE little-known asset class sitting right at the center of this shift.
My free briefing names it, and shows why America’s way out of the debt may run straight through it.
Watch The 2026 AI Gold Rush Briefing →
To your wealth,
Tan Gera, CFA®
Decentralized Masters
P.S. AI agents are already paying for things on their own. See the ONE asset class built for how they pay →
AutoZone’s Real Growth Engine Is Not the DIY Aisle
AZO closed Monday at $3,253, sitting roughly in the middle of its 52-week range of $2,731 to $3,996. The stock trades at 20.75x normalized earnings versus O’Reilly’s 26.77x, a discount that reflects two things: a CFO departure landing November 25 and a DIY segment that has been losing foot traffic all year. Neither tells the full story.
- Full-year net sales of $20.3 billion, up 7.4% year over year, crossing $20 billion for the first time.
- Q4 diluted EPS of $56.05, up 15.1%; full-year EPS of $152.55, up 5.3%.
- Domestic commercial (DIFM) sales grew 8.6% in Q4 and 10.6% for the full fiscal year.
- DIY domestic same-store sales declined 0.6% in Q4; management said some customers deferred maintenance purchases and traded down.
- 172 Mega Hubs now operational; target is about 300, with at least 40 openings expected in FY2027.
- An IEEPA tariff refund benefited Q4 results; management has indicated the benefit should be smaller going forward.
- CFO Jamere Jackson departs November 25 for FedEx; external search underway.
The Structural Shift Driving Positioning
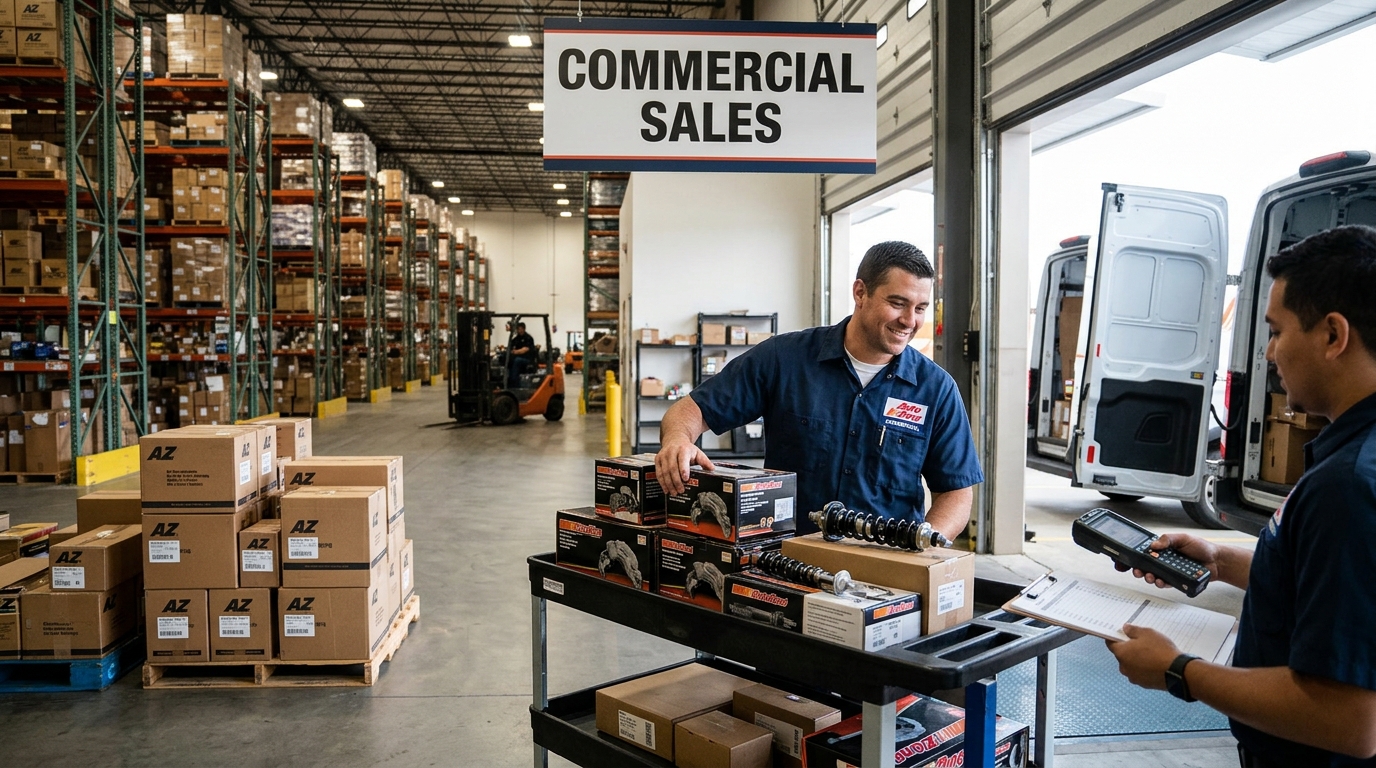
AutoZone spent most of fiscal 2026 fighting a two-speed business. The DIY segment, the brand identity most traders associate with AZO, saw transaction volume decline more than 5% in the period management discussed on the Q4 call, partially offset by average ticket growth around 5%. Meanwhile commercial revenue, the professional repair shop business, compounded at double digits for the full year and now represents approximately 34% of domestic auto parts revenue.
The infrastructure behind that shift is the Mega Hub network. Each Mega Hub carries over 100,000 SKUs and supplies surrounding satellite stores with same-day or next-day delivery. Management said commercial programs linked to a Mega Hub generate roughly 16% higher sales than programs not linked to a Mega Hub network. With 172 locations active and about 300 as the stated target, AutoZone is less than halfway through a build that structurally advantages its commercial margin profile well into the decade.
What the Tariff Refund Obscures
The Q4 headline numbers flatter the underlying picture. The company cited tariff refunds as a material contributor to Q4 gross margin. With management noting it has applied for additional refunds but for lesser amounts, the fiscal 2027 comparison becomes materially harder. Management said it expects same-store sales to be relatively flat to start fiscal 2027, with average ticket still running around 5%. That implies transaction volume remains the drag.
Scenario Framework
Bull Case: DIY transaction trends normalize toward negative 1 to 3% as inflation moderates (management’s stated expectation), commercial comps sustain above 10% on Mega Hub maturation, and the 40+ new Mega Hub openings in FY2027 accelerate weekly sales per program. Stock reclaims the upper end of the 52-week range near $3,996.
Base Case: Flat to low single-digit SSS in fiscal Q1 2027, commercial growth moderates to high single digits as the comparison base rises, and the CFO transition creates modest execution uncertainty through mid-FY2027. AZO consolidates in the $3,100 to $3,400 range at a 20x to 21x earnings multiple.
Bear Case: Consumer stress deepens into year-end, DIY traffic falls further than the historical 1 to 3% range, and LIFO charges persist. At 18x earnings, fair value drops toward $2,750, near the 52-week low.
Levels and Framework for Active Traders
AZO’s 200-day moving average sits near current price. A sustained hold above $3,200 keeps the medium-term trend constructive. The CFO departure is an event-risk overhang through November 25: leadership transitions at the financial officer level have historically introduced short-term multiple compression even when operationally benign. Watch Q1 FY2027 commercial comp guidance as the first clean read on whether the Mega Hub flywheel accelerates without a tariff tailwind underneath it.
The positioning question heading into December is not whether AutoZone is a defensive name. It clearly is. The question is whether the DIFM engine can sustain earnings growth without the one-time items that made FY2026’s numbers look cleaner than the underlying business warranted.