Dear reader,
Most investors wait for the government press conference.
I follow the money before the cameras show up.
And the money trail now leads straight to one tiny nickel stock.
Its U.S. platform has already been selected for $135.4 million in disclosed federal grants: $114.8 million tied to a domestic processing facility and another $20.6 million supporting exploration in Minnesota and Michigan.
That is not a prediction. That’s money already disclosed.
The next step is my forecast: I believe Washington could eventually go further and take an equity stake.
It may never happen. But the U.S. has already shown it is willing to put taxpayer capital directly into strategic mineral companies. And this company now controls the only primary nickel mine operating in America.
Meanwhile, Tesla has locked in a six-year supply agreement, and America remains dangerously exposed to foreign nickel supply.
Russia, China, and Indonesia have leverage because the United States allowed its domestic pipeline to wither.
This little company is one of the few credible ways to fight back.
That’s why I bought 10,000 shares before any equity announcement.
I am not promising Washington will buy in. I am saying the grants, the operating mine, the Tesla agreement, and the strategic pressure form a setup I refuse to ignore.
Click here to learn more about the $5 nickel stock I believe Washington could target next.
Yours for peace, prosperity, and liberty, AEIOU,
Dr. Mark Skousen
Macroeconomic Strategist, The Oxford Club
P.S. Washington has already backed this platform with $135.4 million in disclosed grants.
If an equity stake comes next, I believe a stock this small could move violently.
I refuse to wait for the press conference.
Click here to reveal details on what I bought before Washington makes its next move.
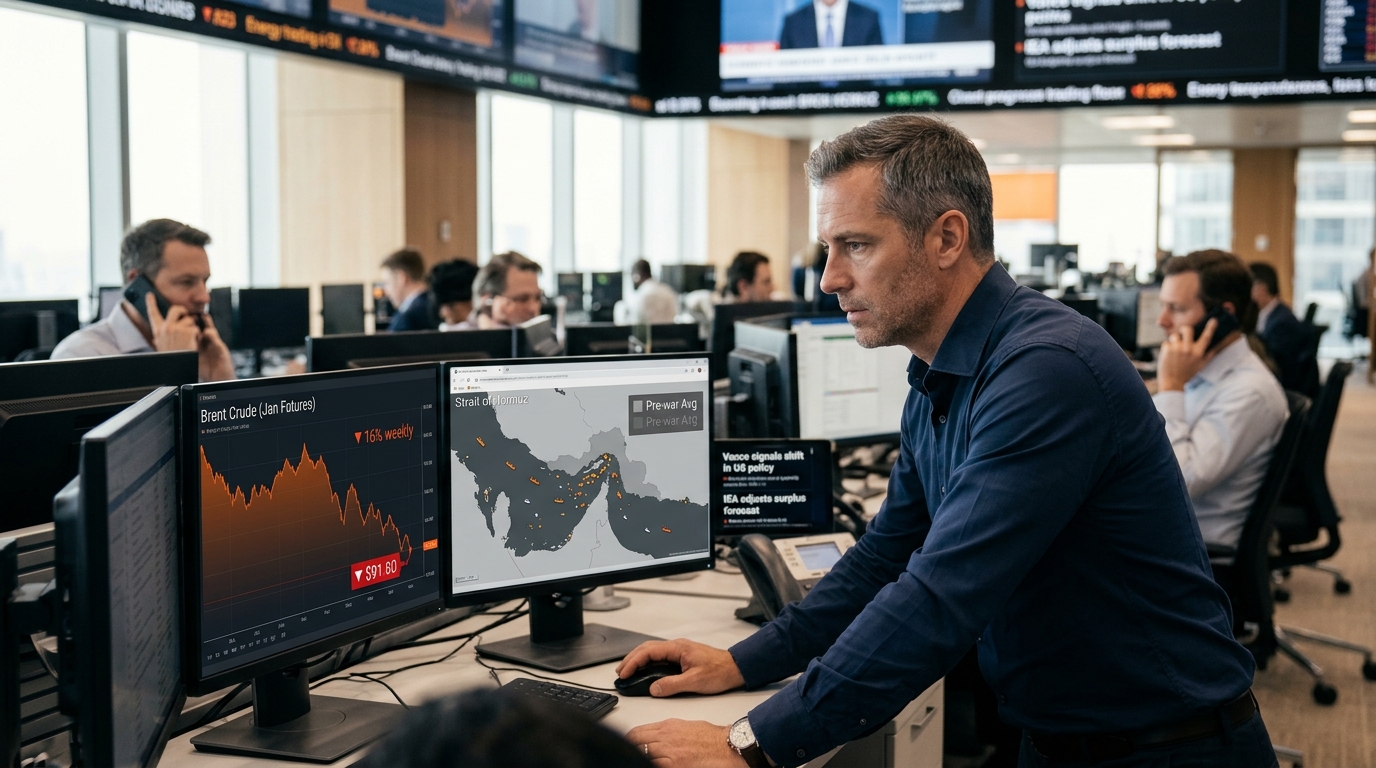
Brent Below $92 After a 16% Weekly Drop. What to Watch
Brent January futures touched $91.66 around 04:30 GMT Tuesday, extending Monday’s 3.5% drop after a week in which Brent and WTI recorded declines of 16% and 13%, respectively. Six weeks ago the same contract was pricing war-risk at nearly every session. That regime is over. Three independent data points are now telling the same story: physical supply is coming back faster than the market priced, diplomatic signals favour de-escalation, and the institutional outlook has flipped from deficit to surplus.
- Brent spot: $91.72–$91.80, down about 0.7% on the day
- WTI: $85.20, down 0.6%
- Brent weekly decline: 16%
- IEA view: the market returns to a surplus in Q4 2026; October supply was 105.4 million bpd
- Goldman Sachs Brent base case, 2027: $88 average, easing to $78 by December 2027
- Hormuz war-risk insurance: roughly 7.5–10% of hull value in 2026 vs. about 0.25% pre-war
- OPEC+ next policy decision: November 29
What Broke the Regime
Shipments from the Middle East through the Strait of Hormuz have recovered from the worst of the disruption, but remain far below prewar levels. The IEA said Gulf oil exports excluding Oman rose to 82% of prewar levels in October, despite continued attacks on shipping. Other independent shipping assessments have put overall traffic through the strait at well under prewar levels.
The political signal reinforced the physical one. VP Vance said Monday on Fox News that President Trump would not allow the conflict with Iran to become a prolonged war, reaffirming the administration’s commitment to avoiding prolonged military engagements. “We are not going to allow this to become a 10- or 15-year commitment,” Vance said. Markets read that as a compression of the conflict-extension risk premium that had been embedded in Brent since the war launched in late February.
The IEA provided the structural anchor. In its November Oil Market Report, the agency said the market is showing signs of rebalancing, with global oil supplies surpassing demand for the first time since the outbreak of the war and its balances suggesting a return to surplus in 4Q26. The report also put October global oil supply at 105.4 million bpd.
Sector and Stock Implications
The integrated majors are absorbing the correction from elevated prices but remain structurally well-positioned. XOM carries an analyst consensus closer to a Buy, with an average price target around $184 against a current price near $168, trailing twelve-month revenue of about $388 billion, and net income of about $40.6 billion. CVX traded around $218–$225 in recent sessions. Valero (VLO), the largest U.S. independent refiner, is a different calculation entirely: falling crude costs are a direct margin tailwind, and the stock has outperformed peers in recent sessions as the crack spread logic shifts in its favour.
Shipping rates remain high because of the risks tankers face carrying crude through Hormuz and because the number of ships tied up in shuttle operations has reduced available vessel supply. War-risk insurance in 2026 has been reported around the high single digits as a percentage of hull value, against roughly 0.25% before the war. As those rates compress, delivered crude costs fall and refiner margins expand. VLO is the cleaner trade for that thesis than the upstream names.
The margin arithmetic behind that thesis is already showing up in Valero’s reported numbers. Valero’s refining margin per barrel tripled year-over-year even as the diesel crack held near record levels, giving the stock a fundamental floor that pure upstream names lack.
Technical Framework
Brent’s 50-day moving average sat at $104.26 as of last week’s close, putting spot roughly 12% below that level, a gap that flags momentum exhaustion rather than a floor. The 200-day average near $94 is now resistance. The November session low of $91.49 is the first meaningful support. A weekly close below $90 would open the path toward Goldman’s $88 average base case for 2027.
The distance from current spot to those moving averages is itself a product of how aggressively the market priced military escalation at the peak. Upstream names like XOM and CVX carried very different risk-reward profiles when Brent was pricing direct US military action near $116.
Volume patterns confirm the regime change: the selloff was broad and orderly, not panic-driven, suggesting institutional repositioning rather than forced liquidation. VWAP anchors from the prior $95–$96 range are now acting as overhead resistance on any bounce.
Scenario Modeling
Bull Case: $96–$100
Fresh mine strikes or confirmed infrastructure damage in the Gulf reignite risk premiums. Iranian state media has reported tanker mine incidents in the Strait of Hormuz, and incidents remain live. A verified supply disruption of 1 million bpd or more would pressure the surplus math and push Brent back toward the $95–$96 prior anchor zone.
Base Case: $88–$93
Goldman Sachs expects Brent to average $88 a barrel in 2027 and slip to $78 by December 2027 as a return to surplus weighs on markets. In this scenario, Hormuz flows continue recovering gradually, the November 29 OPEC+ meeting produces no aggressive output cuts, and demand does not recover sharply. Brent consolidates in the $88–$93 range through year-end.
Bear Case: Below $88
Goldman Sachs said global oil supply in 2027 will exceed end-user demand by 2 million barrels a day, with average Brent prices in its base case at $88 and potentially easing to $78 by year-end. If the November 29 OPEC+ meeting signals 2027 quota increases and transit volumes continue climbing, the surplus could arrive faster than modelled, pulling spot below $88 before Q1 2027.
Active Trader Framework
The asymmetry has shifted. War-risk insurance rates are a leading indicator to monitor. Any sequential weekly compression in those high single-digit hull-value premiums toward mid-single digits would confirm the base case and remove one of the last structural price floors.
For upstream exposure, the risk-reward on XOM and CVX is a function of where spot Brent settles relative to their break-even assumptions, not of near-term price direction alone. For refiner exposure through VLO, the declining crude input cost thesis is more direct and less dependent on a geopolitical call. The November 29 OPEC+ ministers’ meeting on 2027 quotas is the next scheduled binary event. Position sizing ahead of it should reflect that uncertainty, not resolve it.
Preparation matters more than prediction here. The regime has changed. The confirming data, export recovery, insurance rates, and the IEA’s shift to surplus, are aligned. Discipline in level-setting and risk management determines whether traders capture the move or chase it.