September 16, 2026
Bonus Content: The Fed Hikes Rates for the First Time Since 2023. Here Is What Re-rates at 2:01 PM.
Editor’s Note: When the 2008 financial crisis hit, 60 Minutes turned to Whitney Tilson to explain it – a segment that went on to win an Emmy. Billionaires Bill Ackman, David Einhorn, and Joel Greenblatt were among the earliest followers to his research. Now he’s connecting the dots on what he calls possibly the biggest energy story of the decade. See below…
Dear Reader,
Right now, the man CNBC nicknamed “The Prophet” – Whitney Tilson – is making what he believes is the biggest call of his 25-year career.
He recommended Apple when the entire company was worth just $7 billion…
Pitched Netflix on the very day it bottomed…
And walked viewers through the 2008 crash on 60 Minutes, in a segment that won an Emmy award.
His next huge call?
And it isn’t uranium, wind or solar.
In fact, most investors haven’t even heard of this fuel source before.
But lifelong Berkshire Hathaway disciple Tilson noticed Warren Buffett making a strategic company appointment moments before his retirement…
A move he believes offers huge clues to where the puck is heading next in the booming energy market…
And he’s convinced that people who invest now in this little-known power source have the potential to be the market’s next huge winners.
But the clock is ticking on this opportunity.
In fact, Tilson believes Wall Street money could rush in as soon as this October – the moment a key project in this niche power’s build-out phase is slated to finish.
That’s why he’s urging people to pay attention to this story right now – so they know how to claim a ground-floor stake while they still can.
Click here now to watch Whitney’s urgent broadcast.
Sincerely,
Matt Weinshenck
Publisher and Director of Research, Stansberry Research
The Fed Hikes Rates for the First Time Since 2023. Here Is What Re-rates at 2:01 PM.
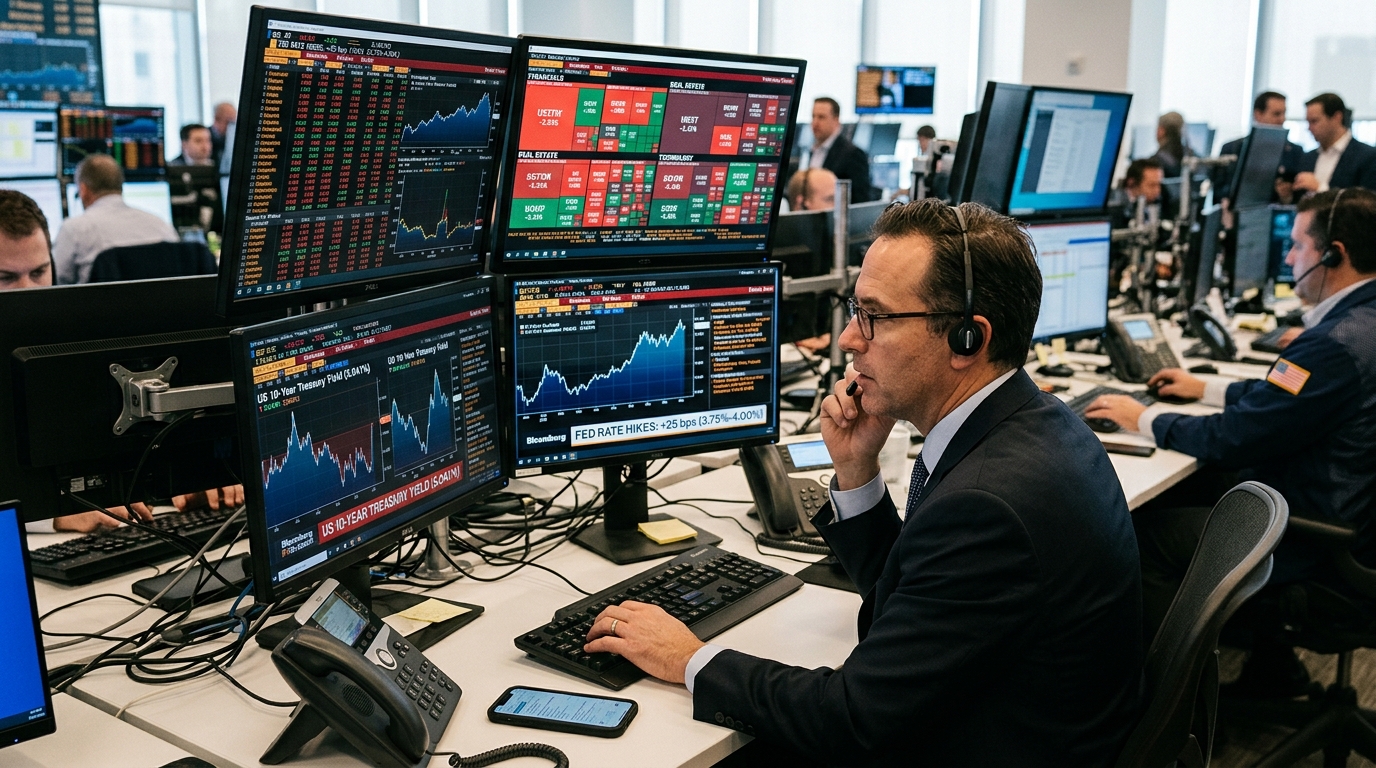
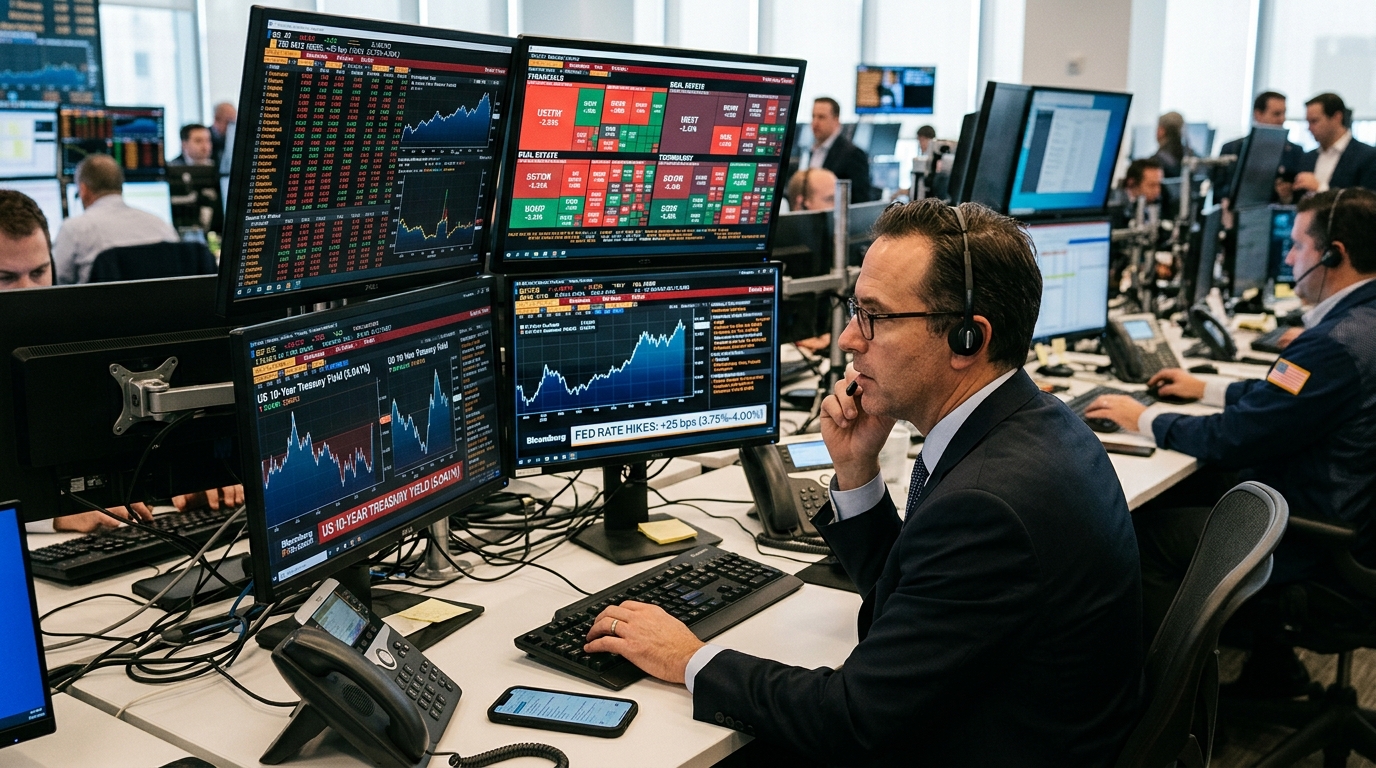
Today is not a day to watch. It is a day to have already decided.
Bullet Summary
- CME FedWatch prices a high probability of a 25-basis-point hike to 3.75%–4.00% at 2:00 PM ET, the first increase since July 2023.
- The 10-year Treasury hit 5.041% Tuesday, its highest level since July 2007, pressuring every rate-sensitive sector before the statement drops.
- August retail sales print at 8:30 AM. July came in at $763.6 billion, down 0.6% month-over-month. The August number lands 5.5 hours before the Fed.
- Empire State Manufacturing fell 13 points to 7.6 in September versus a 14.75 consensus, while the prices paid index rose to 63.1, edging above its recent four-year high reached in May 2026.
- Warsh has largely avoided explicit forward guidance. The dot plot and press conference are the main signals on whether December brings another hike.
- Lennar reports fiscal Q3 earnings after the close. Consensus is $1.30 EPS on about $8.37 billion in revenue, down roughly 35% and about 5% year-over-year, respectively.
- VIX broke above its 50-day moving average toward 18, implying approximately 1.1% daily moves in SPY for the session.
Market Context
The macro backdrop entering today’s decision is tight in ways that complicate the post-hike read. Headline CPI held at 3.4% in August with core at 2.4%. The labor market added 162,000 jobs in August, well above forecasts, after July was revised from minus 23,000 to plus 21,000. That combination left Warsh essentially boxed in. As one market commentary put it, the chair “wanted markets to lead, not follow,” and markets have obliged: futures are pricing this hike as near-certain.
But the long end tells a different story. The 10-year at 5.04% is not merely a reflection of the 25 basis points the Fed is about to deliver. It reflects term premium, fiscal supply, and oil-driven inflation risk that a single quarter-point move does nothing to resolve. TLT closed at $80.87 on September 11. The iShares 20+ Year Treasury Bond ETF has shed roughly 2.7% over the past three months while SPY gained 2.0% over the same period. The divergence captures exactly the tension traders need to price at 2:01 PM.
That same real-yield pressure is doing visible damage beyond the bond market. With 10-year TIPS deep in positive territory, the arithmetic turns mechanically hostile for non-yielding assets — a dynamic explored in detail in why gold and the miners keep falling into this rate hike as real yields rise. Understanding that relationship helps clarify which sectors face structural headwinds today versus those merely caught in short-term volatility.
The 8:30 AM retail sales release is consequential context, not a pivot. July’s 0.6% monthly decline already set a cautious tone heading into August. A second weak month confirms that the consumer is absorbing higher borrowing costs. A strong number complicates the bond rally that a dovish dot plot might otherwise produce.
Sector Breakdown
Homebuilders: XHB traded at $97.76 as of Monday’s close. Lennar’s Q3 EPS consensus of $1.30 represents a 35% year-over-year decline on revenue of about $8.37 billion. The 30-year mortgage averaged 6.76% in Freddie Mac’s September 10 survey; lenders’ daily rate sheets touched 7.17% Monday. BofA has already cut its Lennar price target, reducing EPS estimates for fiscal 2026 through 2028. A hawkish dot plot extending the hiking cycle into 2027 challenges the sector’s recovery thesis, which assumes rates begin easing. At 6.76% and rising, that assumption is under active stress.
The gap between Freddie Mac’s survey rate and what lenders are actually quoting on daily rate sheets is itself a signal worth tracking into Lennar’s print. what the spread between Freddie Mac’s 6.76% survey and lenders quoting 7% means for homebuilder traders breaks down why that divergence matters for interpreting Lennar’s guidance tonight beyond the headline EPS number.
Banks: The rate structure is mechanically favorable for net interest margins on new lending, and KRE has returned 15.6% year-to-date through September 14 on that logic. The complication is credit quality. A slow hiking cycle historically produces milder drawdowns than a fast one, per Schwab’s analysis of eight decades of data. If the dot plot signals only one more hike and Warsh’s press conference sounds deliberate rather than aggressive, regional banks hold their bid.
Utilities and small caps: Both are rate-duration trades wearing equity clothes. Utilities compete with bonds for income capital; small caps in the Russell 2000 are disproportionately reliant on floating-rate debt. The Russell 2000 fell 0.4% on Tuesday and is up about 15.6% year-to-date. A higher-for-longer dot plot extends that rotation away from both groups.
Wall Street quietly buying these stocks before November 3?
We caught Wall Street in the act.
Take a look:
Right here in June…
BlackRock made a strange move.
It put nearly $1 billion into a forgotten-about corner of the AI market.
In fact, we flagged a number of strange transactions from gigantic firms like Goldman Sachs and JPMorgan…
Into two specific stocks in this critical but rarely talked about corner of AI.
I believe these companies are loading up ahead of November 3.
Technical Framework
SPY’s 30-day realized volatility sat at 8.9% as of September 11, but Friday’s CPI-day single session printed 19.2% annualized. The VIX broke decisively above its 50-day moving average toward 18, implying roughly 1.1% daily moves. On FOMC days, the reliable pattern is a whipsaw at the 2:00 PM statement followed by direction setting in the press conference beginning at 2:30 PM. The best read on sector-level conviction comes after 3:00 PM, not on the initial spike. SPY’s decision-day average gain since December 1999 is 0.23%, with markets positive 52.6% of the time. History is close to a coin flip. The dot plot is not.
TLT’s support sits near $81.60 with resistance at $82.54. A dovish dot plot, meaning fewer than two additional hikes projected for 2026-2027, could drive a short-covering rally in duration. A hawkish dot, signaling December plus additional hikes in 2027, tests the prior lows around $80.87.
Scenario Modeling
Bull Case: The hike lands as expected, retail sales surprise to the upside, and the dot plot shows only one additional hike beyond today. Warsh’s press conference language emphasizes data dependence over a prescribed path. SPY holds above the 50-day moving average. Banks and energy outperform. TLT stages a relief rally back toward $83. XHB stabilizes on the removal of ambiguity. Probability: 25%.
Base Case: The hike delivers, retail sales print modestly, and the dot plot shows two additional hikes by end-2027. The 10-year consolidates near 5.0%. SPY closes within 0.5% of the open. Utilities and homebuilders lag; banks trade sideways. Lennar’s post-close earnings are absorbed Thursday. Probability: 55%.
Bear Case: The dot plot is more aggressive than priced, or Warsh signals October is live. The 10-year breaks above 5.15%. TLT tests $79 and the 30-year approaches 5.40%. XHB drops more than 3% intraday. Russell 2000 underperforms SPY by 150 basis points or more. Lennar’s guidance misses and the stock opens Thursday below $75. Probability: 20%.
Active Trader Strategy Framework
The asymmetric risk today is in the dot plot, not the hike itself. A high probability means the hike is already owned. What the market has not fully priced is the distribution of dots beyond September. Monitoring the spread between the 2-year and 10-year Treasury into the 2:00 PM statement provides a real-time read on whether the market is interpreting the decision as the beginning of a sustained cycle or a one-and-done adjustment.
The 2s-10s spread is not the only cross-asset signal worth watching into this decision. The BOJ follows the Fed by roughly 48 hours, and Japan’s accumulated currency intervention has created some of the heaviest positioning risk in global FX markets heading into this window — a setup examined in how two central bank decisions in 48 hours create compounding positioning risk across currencies. A hawkish dot plot that lifts the dollar could force an abrupt unwind in USD/JPY that feeds back into Treasury demand before Friday.
For sector positioning, the sequencing of today’s catalysts matters. Retail sales at 8:30 AM set the tone for consumer-facing names. The 2:00 PM statement reprices rate-sensitive sectors. Lennar’s after-close results then test whether homebuilder fundamentals can survive the macro. Volatility expectations should not be compressed ahead of the press conference. Sizing accordingly into the statement, rather than chasing the initial move, remains the disciplined approach.
Conclusion
Three separate market-moving events are stacked into a single session. Retail sales, a rate hike, and Lennar’s earnings report will each attempt to send a different message. The trader who has mapped the scenario structure and pre-identified levels across TLT, XHB, KRE, and SPY enters 2:00 PM with a framework. The one waiting to react to headlines enters with noise. Preparation is the position.