September 15, 2026
Bonus Content: NuScale’s Dilution Math Is the Real Problem
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear reader,
This might be the most valuable document I’ve ever uncovered.

What’s under the black bars could change your life forever.
Elon quietly filed this document with the federal government.
And what’s inside could be bigger than Tesla, SpaceX, and xAI combined.
Big enough, I believe, to mint a record breaking wave of new “Musk Millionaires” over the coming years…
That’s because Elon is going after the largest cash pile in history.
Artificial Intelligence.
And what is in this filing proves he is about to make Bezos, Altman and Zuckerberg beg for mercy.
Look…
I called NVIDIA in 2008, Bitcoin in 2013, and his Super IPO years before they turned everyday Americans into millionaires.
And what Elon is doing next could be the biggest money making opportunity of them all.
Luckily, almost nobody knows this exists.
But it won’t stay quiet for long. Once it goes mainstream, your chance to get in early is gone.
If you missed out on Tesla…
If you missed out on Bitcoin…
If you missed out on NVIDIA…
This could be your final shot to make up for every other opportunity you’ve missed.
Don’t let one more click and two more minutes of your time be the reason you miss out again.
Regards,
James Altucher
NuScale’s Dilution Math Is the Real Problem
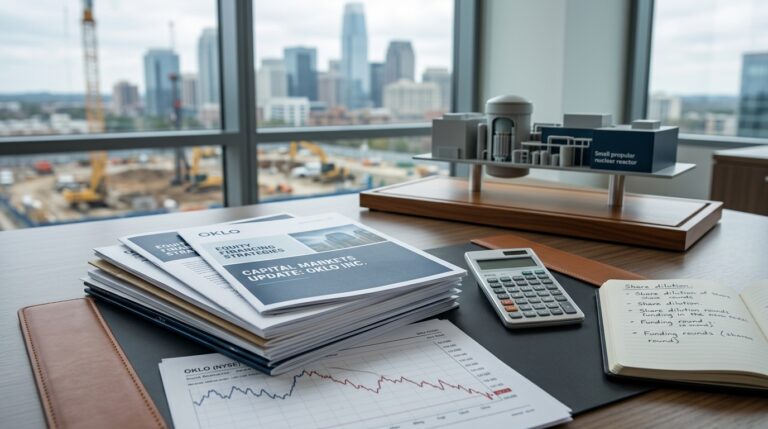
NuScale Power (SMR) entered the week at roughly $10.21, sitting about 81% below its October 15, 2025 closing high of $53.43. The stock has shed about 48% in 2026 alone. The question active traders should now be asking is not whether the SMR technology works. It is whether the equity structure survives the wait.
The Dilution the Bulls Are Underpricing
In the first half of 2026, NuScale issued and sold 89.7 million shares of Class A common stock at a weighted average price of $11.14 per share, raising about $1.0 billion in gross proceeds and $984.5 million net, and it reported no debt. In August, the company launched a $750 million at-the-market stock offering, working with firms including UBS Securities and B. Riley Securities to sell shares over time as needed. Multiple equity programs in roughly six months. Each one expands the denominator against zero near-term revenue.
Q2 2026 revenue was $75,000, down from $8.1 million year over year, reflecting project phase completions and a downward adjustment to revenue tied to prior Fluor services. The cash position remains substantial: liquidity totaled $1.9 billion in cash, cash equivalents, and short- and long-term investments as of June 30, 2026. But that cushion is eroding fast. NuScale used $314.7 million of cash in operating activities during Q1 2026, compared with $22.8 million in the prior year.
What UBS Is Actually Saying
On September 11, UBS downgraded SMR to Sell from Neutral, cutting the price target to $6 from $10. UBS pointed to construction timelines and a lack of firm customer commitments as key challenges.
The valuation gap is the sharper point. At the current stock price, UBS estimates the market implies $124 million of 2028 EBITDA, compared to its own forecast of $29 million. That is a roughly 4x mismatch, and the market has yet to fully close it. Ten of the 18 brokerages in coverage are maintaining Hold ratings, suggesting the next shoe drops when Holds convert.
Technical Framework and Key Levels
SMR is down about 48% in 2026 and about 78% over the past 12 months. July 17 marked an intraday low of $7.21. The recent bounce from that low to $11.18 looks corrective, not structural. VWAP from the post-earnings selloff in early August sits near $10.50. A failure to hold $10 on a closing basis reopens the July low. Above $12.63, the consensus analyst target, momentum shifts.
Scenario Modeling
Bull Case: ENTRA1 finalizes a definitive power purchase agreement with TVA, and at least one European project clears permitting before year-end. Shares recover toward the $15 B. Riley target on contract momentum.
Base Case: No firm contract is signed through Q4 2026. ATM issuance continues at the pace set in H1. Shares drift in the $8 to $12 range, capped by dilution and supported by $1.9 billion in liquidity. Consensus holds near $12.63.
Bear Case: UBS’s $29 million EBITDA forecast for 2028 proves optimistic. RoPower delays extend, TVA talks stall, and the ATM program pushes the share count higher. The $6 UBS target comes into view, roughly 40% below current levels.
Active Trader Considerations
Volatility remains elevated, implying wide price swings for short-term traders. Position sizing matters more than direction here. Monitor the $10 level as the near-term line between a rangebound trade and renewed pressure toward the July low. Catalyst timing, not fundamentals, will dictate the next 15% move in either direction.