Hi Friend,
Just wanted to let you know you can now get a free copy of my new strategy guide here:
How to Master the Retirement Trade [PDF]

What’s the Retirement Trade?
It’s a simple trading opportunity that appears almost every trading day, between 9:30 and 10:45 am EST where traders are making between $300-$1,100+ per contract.
One of my favorite parts about this trade is how predictable it is. It occurs about 3-5 times each week. And once you know what you’re looking for, and how to enter/exit the trade, this could become another nice stream of income for you.
I’m not sure how long I’ll leave this guide up for. So do yourself a favor and take 5 seconds to download it now. At least you’ll have a copy stored for future use!
>> Click Here to Download Your FREE Strategy Guide Now.
To your success,
Dave Aquino
Partner, Head of Options Trading
Base Camp Trading
IMPORTANT NOTICE! No representation is being made that the use of this strategy or any system or trading methodology will generate profits. Past performance is not necessarily indicative of future results. There is substantial risk of loss associated with trading securities and options on equities. Only risk capital should be used to trade. Trading securities is not suitable for everyone. Disclaimer: Futures, Options, and Currency trading all have large potential rewards, but they also have large potential risk. You must be aware of the risks and be willing to accept them in order to invest in these markets. Don’t trade with money you can’t afford to lose. This website is neither a solicitation nor an offer to Buy/Sell futures, options, or currencies. No representation is being made that any account will or is likely to achieve profits or losses similar to those discussed on this web site. The past performance of any trading system or methodology is not necessarily indicative of future results.
CFTC RULE 4.41 – HYPOTHETICAL OR SIMULATED PERFORMANCE RESULTS HAVE CERTAIN LIMITATIONS. UNLIKE AN ACTUAL PERFORMANCE RECORD, SIMULATED RESULTS DO NOT REPRESENT ACTUAL TRADING. ALSO, SINCE THE TRADES HAVE NOT BEEN EXECUTED, THE RESULTS MAY HAVE UNDER-OR-OVER COMPENSATED FOR THE IMPACT, IF ANY, OF CERTAIN MARKET FACTORS, SUCH AS LACK OF LIQUIDITY. SIMULATED TRADING PROGRAMS IN GENERAL ARE ALSO SUBJECT TO THE FACT THAT THEY ARE DESIGNED WITH THE BENEFIT OF HINDSIGHT. NO REPRESENTATION IS BEING MADE THAT ANY ACCOUNT WILL OR IS LIKELY TO ACHIEVE PROFIT OR LOSSES SIMILAR TO THOSE SHOWN.
Brent Jumped on a Crude Build. The Barrel That Matters Is Diesel.
Crude stockpiles built last week. Brent rose anyway. That divergence is the first thing worth understanding before adding or trimming energy positions today.
Bullet Summary
- Brent settled at $101.61 on September 23, up 2.37% on the session, while WTI reached $92.00.
- EIA reported a 3.0 million barrel crude build to 426.4 million barrels, 2% above the five-year average, beating analyst expectations for a 641,000-barrel draw.
- Gasoline inventories fell 1.7 million barrels; distillates dropped 428,000 barrels to 107.4 million barrels, leaving supply about 12% below the five-year average for this week of the year.
- U.S. on-highway diesel averaged $6.529 per gallon as of the week of September 21 (EIA), versus $3.69 around the same week a year ago.
- Saudi Arabia restarted its East-West Pipeline on September 22 after drone attacks, with a full return to roughly 4 million bpd capacity likely to take weeks.
- Refiner stocks MPC, VLO, and PSX have rallied sharply in recent weeks. As of September 18 closes, MPC was about $424.89, VLO about $413.28, and PSX about $273.13.
- MPC Q2 net income: $5.1 billion. VLO Q2 net income: $3.7 billion.
Market Context
Commercial crude stockpiles grew by 3 million barrels to 426.4 million barrels, pushing U.S. inventories 2% above the five-year average, while gasoline stocks dropped 1.7 million barrels and distillates fell 428,000 barrels to 107.4 million barrels, leaving distillate supplies about 12% below the five-year average for this week of the year. That combination produced a split market: crude overhang at the headline level, structural tightness buried in the product data.
Distillate stocks finished the week at 107.4 million barrels and are running about 12% under the five-year average for this point in the calendar. U.S. on-highway diesel prices averaged $6.529 per gallon as of the week of September 21 (EIA), versus about $3.69 around the same week a year ago. That kind of product-level deficit does not resolve with a crude build; it resolves with sustained refinery throughput, which is currently constrained.
An analyst at ship tracking firm Kpler noted that crude inputs need to run near 17 million barrels per day to stave off product inventory draws. Refinery utilization dropped 2.8 percentage points to 94.0% in the week, due largely to outages including ExxonMobil’s Joliet, Illinois refinery, which has been dealing with flooding and power-related disruptions. That single plant can explain a meaningful portion of the distillate tightness at the margin.
The Pipeline Variable
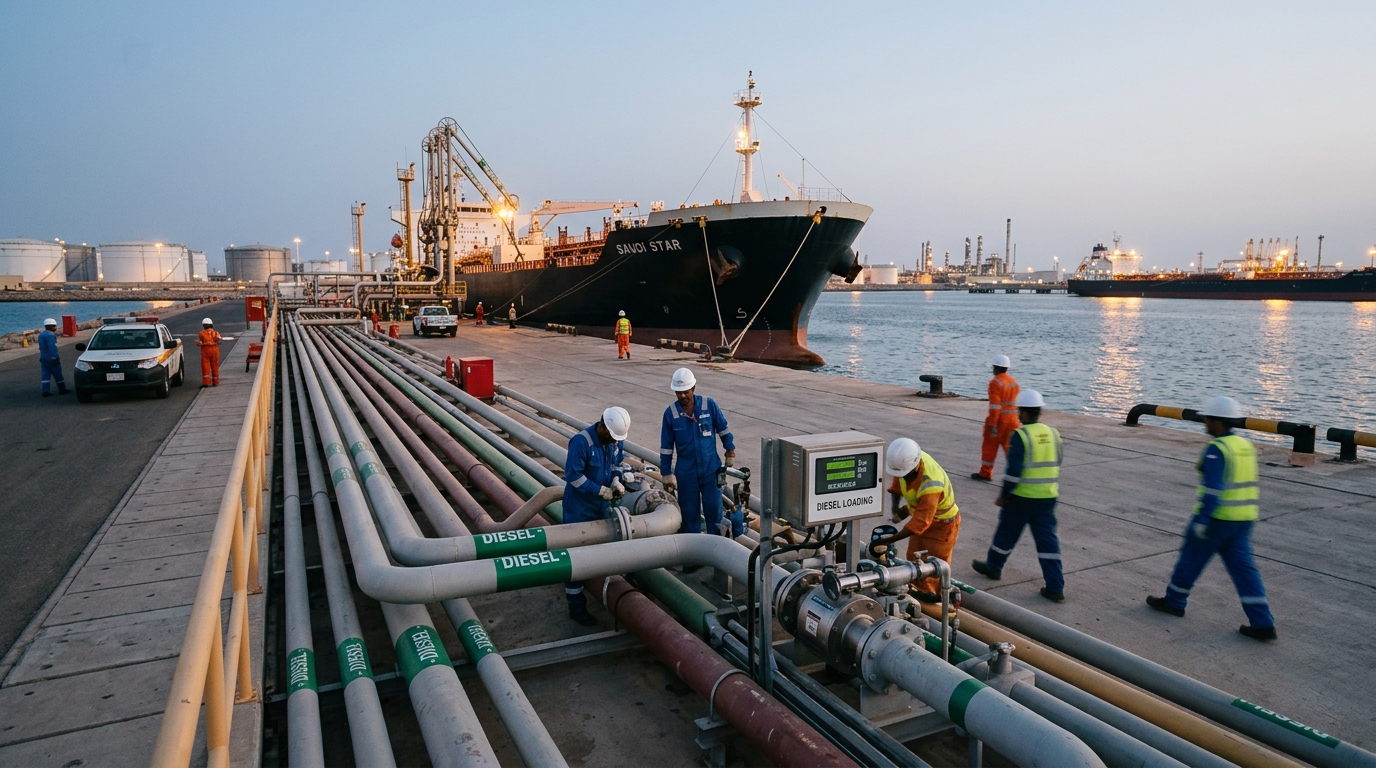
Drone attacks forced Saudi Arabia to shut its East-West Pipeline in mid-September, halting crude loadings at the Yanbu port. The resumption of supplies on September 22 helped ease immediate routing stress on global oil markets. Since disruption to oil flows through the Strait of Hormuz following the U.S.-Israeli conflict with Iran, OPEC’s leading oil exporter has leaned more heavily on the pipeline to reroute crude to Yanbu.
The pipeline is running at a low rate for now, with Aramco working to return flows toward roughly 4 million bpd. A full restart could still take weeks. That is the key qualifier. The market priced a partial restart on September 22, then reversed when the EIA data landed. The rebound to $101.60 reflects traders reading through the crude build to the product deficit, and discounting an incomplete pipeline recovery.
Sector and Stock Breakdown
The clearest beneficiaries of a sustained distillate deficit are independent refiners. MPC, VLO, and PSX have been among the downstream names showing the strongest momentum. As of September 18 closes, MPC was about $424.89, VLO about $413.28, and PSX about $273.13.
MPC reported Q2 2026 net income of $5.1 billion, while VLO posted $3.7 billion, reflecting strong operational performance across the sector. Claims about VLO’s specific forward P/E, S&P 500 forward P/E, and quarter-over-quarter EPS and revenue growth vary by vendor and update frequently; traders should confirm the exact figures on their terminal or in the companies’ filings and the index methodology they use before leaning on a single snapshot.
For the integrateds, analyst price targets and next-quarter consensus numbers move continuously. Traders should treat any single point estimate as stale quickly and confirm the current consensus set and the underlying estimate dispersion before using it as an input.
Technical Framework
Brent held above $100 after the pipeline news broke on September 22 and then re-accelerated through Wednesday’s session. The $98 to $100 range established on pipeline restart day is the first structural support zone to monitor. A close below $98 would suggest the market is pricing fuller pipeline recovery than current flows justify. The $105 level represents the next meaningful resistance.
For refiner equities, VLO and MPC are extended relative to their 50-day moving averages after a multi-week run. Pullbacks toward the 20-day moving average on light volume represent the more disciplined entry point rather than chasing the current momentum.
Scenario Modeling
Bull Case: The East-West Pipeline returns to full 4 million bpd capacity within two weeks, but refinery disruptions persist into October, keeping distillate stocks below seasonal norms. Diesel crack spreads widen further, driving VLO and MPC to fresh highs. Brent tests $107 to $110 as geopolitical risk premium resets higher.
Base Case: The pipeline ramps slowly over four to six weeks. Refinery utilization recovers toward the mid-to-high 90s as outages resolve. Brent consolidates in the $98 to $104 range, distillate stocks remain meaningfully below average through October, and refiner margins hold at elevated levels. Crack spreads stabilize near current levels rather than expanding further.
Bear Case: Iran and the U.S. reach a framework agreement, Hormuz shipping normalizes further, and the pipeline reaches capacity simultaneously. Brent breaks below $95 on the supply surge, crack spreads compress sharply, and refiner equities reverse a portion of their recent gains. Expectations for forward crack spread compression become the spot reality.
Active Trader Strategy Framework
The crude build is not the signal. The product deficit is. Traders weighing energy exposure should consider that distillate tightness is a function of refinery throughput and seasonal demand, both of which are slow to reverse. The pipeline restart introduces a binary risk: a faster-than-expected ramp in Saudi volumes could temporarily pressure crude prices even as distillate tightness persists, creating divergence between upstream and downstream names.
Key levels to monitor: Brent $98 as structural support, $105 as resistance. For refiner equities, the 20-day moving average on VLO and MPC offers the more measured risk reference relative to current extended levels. Sizing energy exposure to the distillate dynamic rather than the crude headline gives the more coherent risk framework. Volatility is elevated; position sizing should reflect that.
Conclusion
Wednesday’s EIA data was not a bearish crude report dressed up as a rally. It was a split report: excess crude at the headline, deficit in the product that moves pricing for industry, agriculture, and transport. The Saudi pipeline restart is a routing relief valve, not a resolved supply question. Disciplined traders track what the barrel is actually worth in its refined form. Right now, that calculus favors distillate-exposed refiners over broad crude length, pending clarity on how fast Yanbu resumes full exports.