September 29, 2026
Bonus Content: Mid-Cap Borrowers Are Running Out of Road to Dodge Debt Bills
A 2026 Gold-Silver Production Story Still Under $1.
There is a specific frustration that hits investors after a major move.
You watch the obvious names run. You hear about them everywhere. Then suddenly everyone starts acting like it was obvious the whole time.
Gold and silver feel a little like that right now.
The majors moved first. The headlines followed. And now a lot of investors are looking at the sector wondering if there is still room.
But here’s the part people miss. The first move usually goes to the obvious names. The next move often starts when investors find the stories still sitting just outside the spotlight.
Here’s one of those stories sitting just outside the spotlight for now.
And it is not just another junior explorer asking investors to wait years for a possible discovery. It is targeting 2026 production from above-ground material already sitting at the surface.
That means potential cash flow may be coming into view much sooner than the usual junior mining timeline.
That is a rare setup: a near-production company with cash flow potential before the crowd fully connects it. In a gold and silver market that is already moving.
Find out why this gold-silver setup may not be obvious for long…
Mid-Cap Borrowers Are Running Out of Road to Dodge Debt Bills
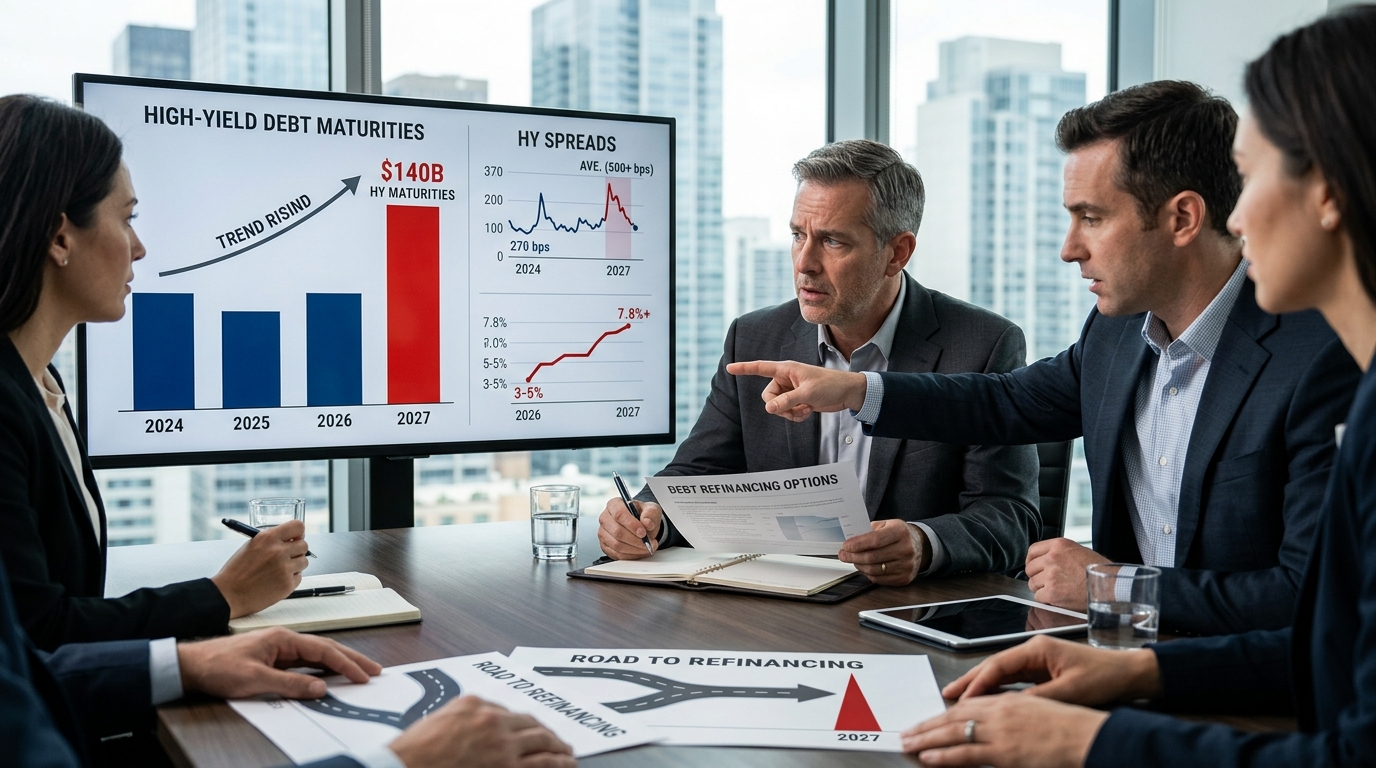
The surface looks calm. High-yield spreads sat near 270 basis points in early August 2026, well below the long-run average (roughly 500 plus basis points), and the ICE BofA index yield stood at 7.80% as of September 24. Beneath that, a specific corner of the market is under mounting stress: mid-cap leveraged borrowers who locked in pandemic-era coupons at 3–5% and now face rolling that debt at 7–10% or more.
The Numbers That Matter
Reuters reported this month that roughly $4.3 trillion in non-financial corporate bonds mature between 2027 and 2031, with annual maturities climbing from about $572 billion in 2027 to roughly $1.03 trillion in 2030. The mid-cap slice is more concentrated: 237 publicly traded U.S. and Canadian high-yield companies carry $79.2 billion maturing in 2026 alone, with about $140.3 billion hitting in 2027. Fitch’s trailing 12-month leveraged loan default rate was about 3.8% in July 2026, down from roughly 5.9% last September, but Fitch still projects 4.5–5.0% by year-end. Private credit is running hotter: Fitch put its trailing 12-month private credit default rate at 6.1% in July.
The LME Trap
The go-to survival tool has been the liability management exercise, or LME. Names including Lumen, Carvana, CommScope, and EchoStar bought runway using uptier exchanges and debt-for-debt swaps. But Harvard’s Bankruptcy Roundtable flagged that the Financial Times has reported around 80% of companies default on their restructured debt within three years of an LME. Davis Polk restructuring partner Adam Shpeen put it bluntly earlier this year: “what may keep me busiest in 2026 is busted LMEs” , companies that got the extension but never fixed the operating problem underneath.
That is the real trade. Refinancing volume for high-yield bonds is forecast around $250 billion in 2026, per BofA Global Research. The problem is that strong issuers are capturing nearly all of it. Access to capital has bifurcated sharply: companies with durable cash flows execute on tight terms while weaker names face covenant resets, PIK-toggle structures, or creditor-on-creditor conflict. Sovereign issuance competing for the same investor dollar is keeping long-end yields elevated and compressing the window for marginal borrowers.
Scenario Framework
Bull Case: High-yield spreads compress back toward 230 basis points as the Fed signals a 2027 cut cycle, letting B-rated mid-caps refinance at sub-8% all-in costs. Distress-for-control opportunities thin out. Watch HYG and JNK for spread signal.
Base Case: The 10-year Treasury holds above 5%, the refi window stays open only for BB-rated and above, and the CCC cohort faces extended maturities at punishing coupons. Fitch’s 4.5–5.0% leveraged loan default forecast proves accurate by December.
Bear Case: A macro shock widens high-yield spreads back toward the 346 basis points seen at the late-March 2026 peak during the Iran-war selloff. Companies in the roughly $79 billion 2026 maturity bucket that have not yet refinanced face distressed exchanges or outright Chapter 11. BDC quarterly earnings become the clearest stress gauge.
Positioning Considerations
Traders watching this credit cycle should monitor bond tender offers and exchange offers as early warning signals, per fixed-income convention: these transactions typically precede defaults by six to eighteen months. CCC spreads deserve closer attention than the headline index, which is distorted by BB-quality paper. BDC earnings reports from Ares Capital, Blue Owl, and FS KKR over the next two quarters will quantify non-performing loan trends in the private credit layer that public indices do not capture. Position sizing in high-yield ETFs should account for duration asymmetry: the upside in a spread-tightening scenario is limited when all-in yields are already 7.80%, but the downside in a default wave is not.
Preparation matters more than a spread call here. The companies that refinanced proactively in 2024 and early 2025 are not the ones traders need to watch. The ones that delayed are arriving at 2027 with fewer options, tighter lender relationships, and an interest coverage ratio that rate-cut hopes alone cannot fix.