Back in the 1860s, settlers from France, Italy, and Germany built grand Parisian boulevards…
…neoclassical facades…
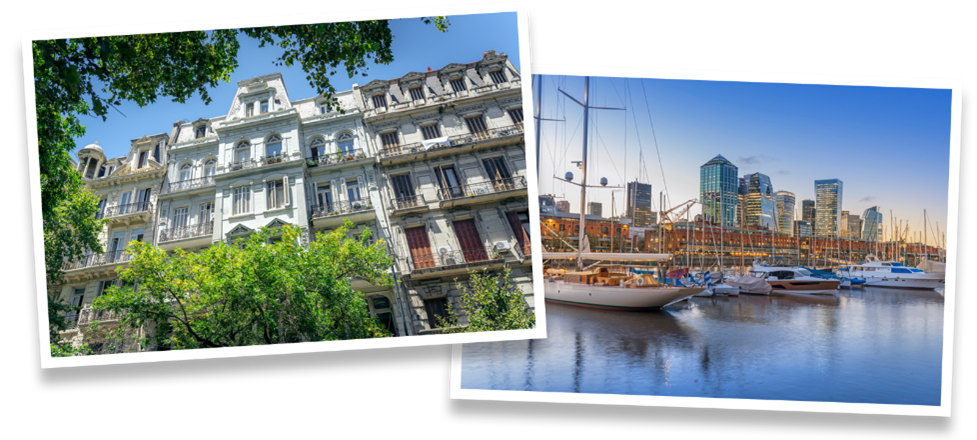
… and cobblestone Bavarian villages halfway across the globe.
Then the rest of the world largely forgot about them.
Today, expats are uncovering a European standard of living…
… Lakefront rental homes for $721 a month…
… private chauffeur service…
… and elite healthcare – completely free from tourist crowds and inflated European price tags.
The Last Inflation Reading Before the Fed Decides Has No Yearly Benchmark
Friday’s payrolls report changed the calculus. The U.S. economy added 165,000 jobs in October, more than double the 65,000 economists expected. Trader bets on a December interest-rate hike moved up after the data, with investors now seeing roughly a 78% chance of an increase. With the labor market anchor firmly in place, inflation is now the only variable left that could meaningfully shift December odds before the FOMC convenes.
The next CPI release is scheduled for Tuesday, November 10, 2026 at 8:30 AM Eastern Time, covering October 2026. It is the last CPI report the Fed will see before its December 8-9 meeting and December 9 decision. And it arrives missing something traders lean on every month.
The Missing Anchor
The Bureau of Labor Statistics did not issue an October 2025 CPI news release due to the suspension of federal government services during the 2025 shutdown. As a result, there is no October 2025 benchmark to compute the standard year-over-year CPI change for October 2026. That strips the market of its standard first-reaction metric. Algos fire on year-over-year misses. Human traders anchor to them. Tuesday delivers neither. The month-over-month core reading takes on disproportionate weight.
Consensus expects headline CPI to rise 0.3% month-over-month in October. The Cleveland Fed nowcast, updated November 6, puts headline at 0.24% and core at 0.21% month-over-month. Analysts suggest risks to core CPI are skewed to the upside; Bloomberg’s new core price index is currently tracking a 0.33% month-over-month rise in October. That spread, 0.21% to 0.33%, is the entire zone of market-moving uncertainty.
What the Numbers Do to Markets
Barclays forecasts headline CPI rising 0.24% and core CPI increasing 0.22% month-over-month, which the bank estimates would translate into a 0.21% rise in core PCE in October. Barclays’ baseline remains a 25-basis-point hike at the December FOMC.
A 0.21% core print likely cools the 10-year modestly from its current 4.86% to 4.89% range and trims December hike odds toward 65% to 70%. The 10-year TIPS real yield stood at 2.64% as of November 4, and a soft core reading would compress nominal yields faster than real ones, narrowing the breakeven. The 10-year breakeven inflation rate sat near 2.30% as of November 3, a level that already prices only modest disinflation. TIP, the iShares TIPS Bond ETF, would likely firm on a soft core as the inflation adjustment backstop gains relative value versus nominal Treasuries. TIP’s NAV was about $106.20 as of November 5.
A 0.28% to 0.33% core number is a different market entirely. December hike odds, already at 74% to 78% across futures and prediction markets, could push through 85%. Pantheon Macroeconomics retains its forecast for a 25-basis-point rate hike in December, citing the near-term inflation feed-through from higher energy costs. The 10-year likely retests the 5.00% area. The dollar firms. TIP underperforms nominal duration.
Scenario Framework
Bull Case (soft CPI: core at 0.21% or below). December hike odds fall to 65%. The 10-year yields 4.65% to 4.75%. TIP outperforms; short-duration TIPS see the strongest bid as real yield compression is steeper at the front end. DXY retreats toward 100.50. Equities rally on relief, with rate-sensitive sectors leading.
Base Case (in-line: core 0.22% to 0.27%). December odds hold near 75%. The 10-year consolidates around 4.80% to 4.90%. TIP trades sideways. The dollar remains range-bound between 101 and 102. Markets wait for November PPI on Thursday the 12th for the next signal.
Bear Case (hot CPI: core at 0.28% or above). December odds approach 85% to 90%. The 10-year re-challenges 5.00% to 5.10%. TIP drops as nominal yields surge and breakevens widen to uncomfortable levels. DXY pushes back toward the 102.50 to 102.94 range last seen in October.
Trading Framework
Without a year-over-year anchor, the first 15 minutes of post-release trading will carry more noise than usual. The two-year Treasury yield is the cleaner real-time signal: a move above 4.80% on the release confirms the hawkish read; a drop below 4.55% confirms relief. The most informative confirmation is often whether the two-year yield, the dollar index, and major currency pairs keep moving in the same direction after the initial release volatility fades.
VWAP on TIP and the 10-year futures contract will be the intraday reset levels. Traders sizing into duration before 8:30 ET Tuesday are taking uncompensated risk. Strong jobs data leaves inflation as the most important dimension of the Fed’s rate outlook going forward, and next week’s CPI report is likely to be very consequential, according to Glenmede’s chief of investment strategy Jason Pride. That is precisely the positioning environment where discipline around entry levels matters most. Wait for the data, confirm the directional follow-through, then size accordingly.