Dear Reader,
Across America, there’s been violence, protests, lawsuits, canceled projects, and campaigns to impose statewide moratoria to stop AI’s impact on cities and small towns across the nation.
And Whitney Tilson, the man CNBC once named “The Prophet,” believes these frustrations are only going to get worse.
Because now that our midterm elections are over, he believes it’s all going to come to a head.
And it will have huge implications on your portfolio.
If history is any indication, those on the winning side of this divide could see their wealth grow exponentially…
While the losers could see their portfolios cut in half – or more – within the next six months.
That’s why today Whitney is sharing all the details of this divide with you.
And what you must do right now to protect your wealth.
When “The Prophet” makes predictions, people listen…
In 2000, he called the dot-com crash before many investors lost everything.
He predicted the bankruptcies of Bear Stearns and Lehman Brothers during the Great Financial Crisis.
He appeared on 60 Minutes and called the bottom of the stock market right before the longest bull market in history.
Today, he’s sharing all the details of his new prophecy…
One that could be the most consequential to your wealth to date.
Regards,
Matt Weinschenk
Publisher and Director of Research, Stansberry Research
P.S. Whitney believes what’s happening today could reset the financial system now that America has voted. If he’s even half-right, it’s going to have a huge impact on your money and your future. Get the details here…
CEG Reports Monday. The PPA Payoff Is Years Away.
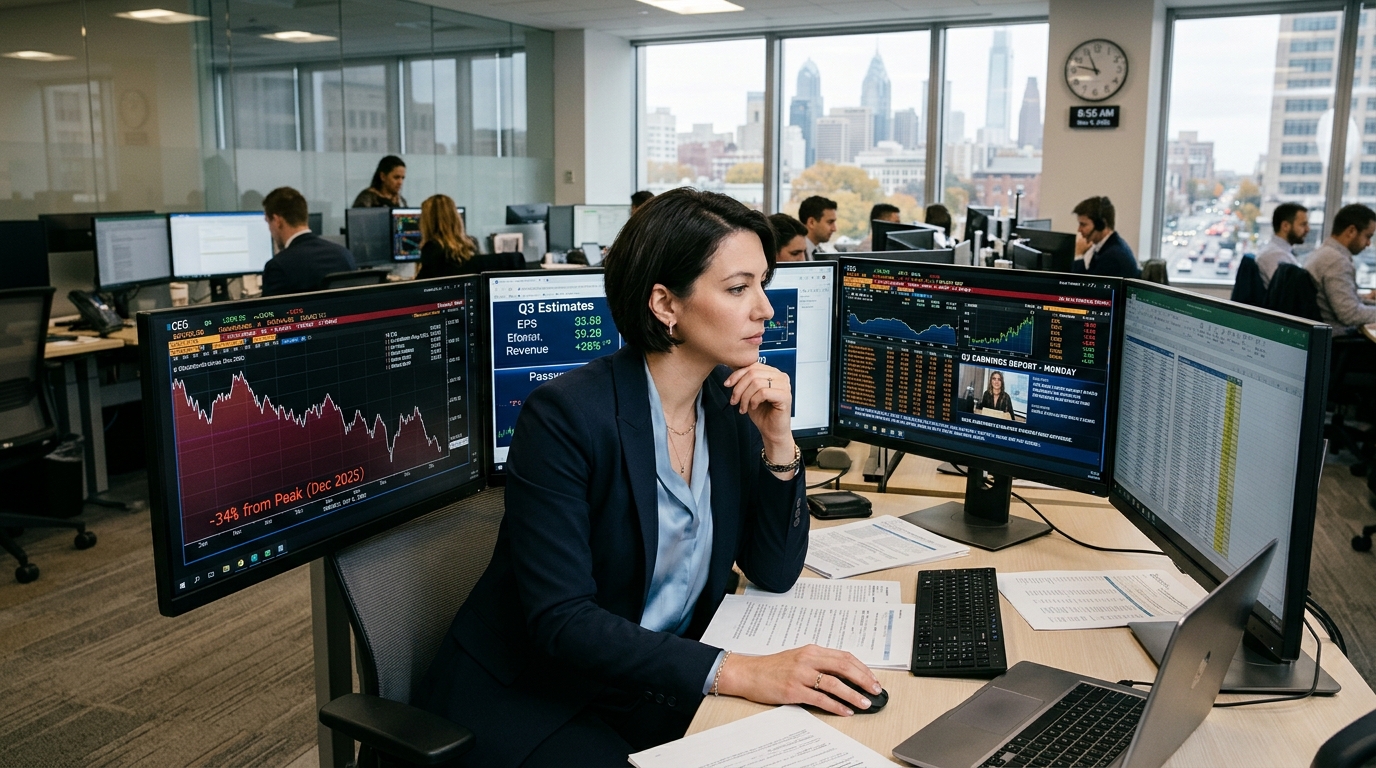
Constellation Energy is scheduled to report Q3 2026 earnings on Monday, November 9, 2026, with a conference call at 9:00 a.m. ET. Consensus estimates are still centered around roughly $3.88 to $3.91 in EPS and revenue near $9.2 billion. That would represent approximately 28% EPS growth year-over-year from Q3 2025’s $3.04 print. The stock closed Friday, November 6 at $249.95, sitting 34% below its 52-week high of $380.78 set on December 12, 2025.
That gap is the actual trade. Not the PPA headlines.
The Contract Book Is Real. The Revenue Is Not Here Yet.
Since September 30, Constellation has signed back-to-back 20-year nuclear power purchase agreements: 690 megawatts with Amazon tied to its Calvert Cliffs facility, and 890 megawatts with Google tied to more than $4.3 billion in upgrades across 11 nuclear units in Illinois, Pennsylvania, and New Jersey. Add the Microsoft agreement anchoring the Crane Clean Energy Center restart, and the company now holds one of the most concentrated hyperscaler PPA books in U.S. nuclear history.
The problem for near-term positioning: almost none of that contracted volume turns on before 2028. Constellation’s published modeling shows contracted clean nuclear volumes rising from 36 million MWh in 2026 to 53 million MWh by 2028 at $77 per MWh, stepping to $85 per MWh in 2029. The Crane restart itself is still framed as a 2027 event, and the NRC approved a fuel-related license amendment for Crane dated July 1, 2026. That is an earnings bridge that requires today’s underlying business to hold.
What Q3 Must Show
Q2 2026 showed real volatility in the quality of earnings beneath the headline: operating revenue was about $7.5 billion, and adjusted operating earnings were $920 million (or $2.55 per share). Full-year adjusted EPS guidance sits at $11.50 to $12.50, raised from $11.00 to $12.00 in August. Analysts now need Q3 to demonstrate that the Calpine integration is producing the accretion promised when the deal closed on January 7, 2026, and that PJM capacity revenues are running above the base case. Any narrowing of that guidance range matters.
Revenue at $9.2 billion would represent a sharp year-over-year increase, largely Calpine-driven. But top-line beats have been inconsistent: in Q2, revenue came in around $226 million below consensus, while Q1 revenue was roughly $2.66 billion above consensus. Volume alone will not move the stock. Margin trajectory will.
The margin-versus-revenue tension is not unique to Constellation. GE Vernova faced the same scrutiny heading into its Q2 print, where a record $163 billion backlog meant nothing until margin conversion proved out.
Technical Framework
CEG’s 52-week range is $228.63 to $380.78. The stock is consolidating between roughly $243 and $265. Moving average support sits near $243, with a secondary floor near $228. A clean Q3 beat with guidance reaffirmed could test $280 resistance. A miss or a guidance cut opens the door to the $228 low, which is about 9% below the November 6 close.
Scenario Modeling
Bull Case ($280-$300): Q3 EPS clears $4.00, management reaffirms the high end of full-year guidance, and commentary on the Google and Amazon PPA timelines confirms 2028 uprates are on schedule. Morgan Stanley’s $391 target becomes the conversation.
Base Case ($245-$265): Results land in-line, guidance midpoint holds at $12.00, and the stock grinds laterally as the market waits for the 2028 contracted revenue ramp to become visible in forward estimates. The 23.5x trailing P/E holds but does not expand.
Bear Case (sub-$230): Margin compression worsens, refueling outages in Q3 exceeded expectations, or management signals slippage in the Crane restart timeline. The Illinois ZEC program ending in 2027 without full PPA replacement coverage becomes the story investors price in.
Active Trader Framework
The asymmetry here is wider than the stock’s beta of 1.13 suggests. Traders holding through the report should size for a 10-15% move in either direction given the recent earnings-day volatility pattern. Watch the adjusted operating earnings quality and any commentary on the contracted nuclear MWh ramp. If Constellation confirms the 2029 base EPS target of $11.40 to $11.90 without revisions, the stock’s current valuation at roughly 20x forward 2027 earnings becomes a credible entry for patient capital. If the bridge wobbles, $228 is the number.