September 14, 2026
Elon’s Next Move Will Be Bigger Than the IPO
Bonus Content: FedEx Reports Thursday Night. Oil at $104 Makes This Quarter Count.
Editor’s Note: Hedge fund legend who delivered a 279% return on cash in 2025 and went on a 20 year winning streak, says Elon Musk is now executing the “Final Phase of his Master Plan”… and he’s identified the ONE ticker that stands to benefit most (it’s not SpaceX, Tesla, or anything you’d associate Elon with). Click here to see the details.
Dear Reader,
The SpaceX IPO made headlines around the world.
But Larry Benedict – the hedge fund legend who went on a 20-year winning streak – wasn’t watching the IPO.
He was waiting for what comes after.
You see, the SpaceX IPO has triggered a countdown.
And when that clock hits zero, billions of dollars could be forced into one specific ticker.
The ticker isn’t SpaceX or any of Elon’s companies.
And it could happen within days – far faster than anyone expects.
This is what Larry calls the “Final Phase of Elon’s Master Plan.”
Right now there is still a short window to get positioned ahead of it – and Larry is revealing the ONE ticker completely free today.
Click here to watch the presentation.
Regards,
Lauren Wingfield
Managing Editor, The Opportunistic Trader
P.S. Larry says in over 40 years of trading, setups this clear are rare… and this is one of them. Click here now.
FedEx Reports Thursday Night. Oil at $104 Makes This Quarter Count.
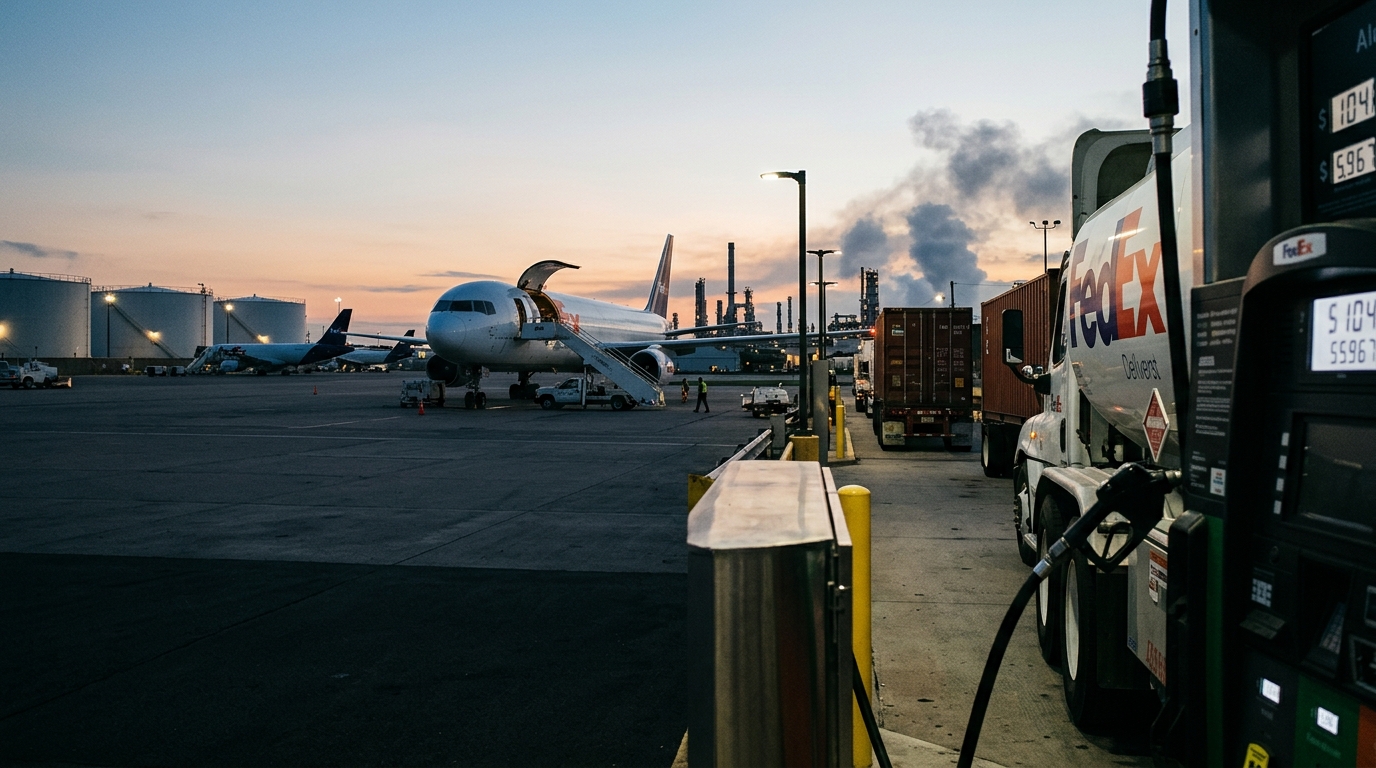
FedEx reports its fiscal first quarter after Thursday’s close, and the confluence of catalysts around it is as compressed as any earnings setup this year. The FOMC announces its rate decision Wednesday afternoon. Quad witching arrives Friday. And sitting in the middle of all of it is the company with the broad operational read on what $104 Brent and $5.967-per-gallon U.S. on-highway diesel did to global freight volumes between June and August.
Market Context
The macro backdrop entering this report is hostile to asset-light assumptions. Brent crude has traded above $100 since early September, with spot prices briefly pushing into the high $100s before pulling back toward $104. U.S. on-highway diesel hit $5.967 per gallon for the week of September 7, a nominal record on the EIA series used in many fuel-surcharge schedules, as the Iran war disrupted flows through the Strait of Hormuz and Russia maintained restrictions on diesel exports. Diesel refining margins also spiked into triple digits in early September, far above typical pre-conflict levels.
The Fed holds rates at 3.50% to 3.75% with a divided committee. Three dissenters at the July meeting favored a hike. Wednesday’s decision arrives with updated dot plots and a fresh Summary of Economic Projections, making the 2:00 PM announcement a live volatility input before Thursday’s FDX print.
Why FedEx Is the Cleanest Read
FedEx completed the spin-off of FedEx Freight on June 1, beginning the quarter as a package-and-express focused operator. The company’s fiscal year still begins on June 1 and ends on May 31, so this remains a June-to-August quarter rather than a shift to a calendar-year fiscal basis. The separation does concentrate fuel exposure inside the remaining network, but this draft’s segment mix and jet-fuel cost figures cannot be confirmed as stated and are best treated as directionally important rather than precisely quantified.
Consensus sits at $4.28 per share on roughly $23.1 billion in revenue. That compares with $3.83 reported in the year-ago quarter, implying 11.7% EPS growth. The bar is achievable, but the mechanism matters: in the prior-year period, U.S. average daily package volumes rose and yield expansion drove the beat. This time, traders need to know whether volume held or decelerated as fuel costs compressed shipper economics.
Sector and Peer Positioning
The broader freight complex has been navigating the same cost environment. UPS and FedEx both implemented 2026 general rate increases. LTL carriers including ODFL have benefited from structural pricing power after Yellow’s 2023 exit removed a meaningful chunk of industry capacity, creating a more disciplined pricing environment that can hold even as diesel surges. XPO operates in a similar discipline.
FDX trades at approximately 16.8x trailing earnings. JPMorgan cut its price target to $400 from $460 last week while maintaining an Overweight rating. Raymond James carries a $330 target. The 52-week range and other real-time price statistics move daily, but the stock is trading around $310 to $312 after going ex-dividend on September 14 at $1.22 per share.
Technical Framework
FDX has pulled back roughly 10% from its August 13 all-time closing high of $339.35. The stock found support near $308 during the September 11 session, which aligns with a prior consolidation zone. The 52-week low is the structural anchor, but nearer-term the $305 to $308 zone is the level to watch for post-earnings weakness. A sustained hold above $315 on the report would suggest the market is absorbing cost pressures as manageable.
Volume has been running below the 1.53 million average daily. That thins the order book into a binary event straddled by the Fed and quad witching, where institutional rebalancing can amplify directional moves.
Scenario Modeling
Bull Case: FDX beats $4.28 consensus on stronger-than-feared international yield, raises full-year guidance from its current $23.1B revenue trajectory, and management notes fuel surcharges are offsetting cost headwinds. Stock attempts a return toward $330-$340.
Base Case: EPS lands near consensus with volume softness offset by yield pricing. Full-year guidance holds. Network 2.0’s $2 billion savings target by 2027 remains on track. Stock trades $305-$320 as the market digests Fed and witching volatility before re-anchoring.
Bear Case: International volume contracts materially under tariff pressure and fuel-cost pass-through fails, compressing operating margins below the 5.3% reported a year ago. Management cuts guidance. Stock tests the $290-$295 region, well below JPMorgan’s revised $400 target.
Active Trader Strategy Framework
Wednesday’s Fed decision sets the directional backdrop for the FDX print. A hike, or a hawkish hold with multiple dissenters, pressures freight multiples before earnings arrive. A hold without escalation is the more stable launch condition.
Quad witching on Friday creates mechanical volume and pin-risk around large open interest strikes. Traders carrying FDX options through the print face Thursday post-close volatility plus Friday gamma unwind simultaneously. Position sizing and defined-risk structures are worth the discipline. Guidance language on fuel surcharge effectiveness and volume trends through September will move this stock more than the headline EPS number.
Conclusion
Few companies that report this week spent the entire June-to-August period operating a major global express network with on-highway diesel above $5.50 and Brent oscillating near $100. FDX’s Thursday result is not just a company event. It is a macro data point in corporate form. Preparation before the Fed and before the witching session matters more than any directional bet placed in a compressed, high-volatility window.