September 26, 2026
Switchgear lead times now exceed 60 weeks, transformer waits stretch to four years
The conversation about the U.S. energy buildout rarely lands on the right constraint. Capital is not the problem. Edison Electric Institute projects its member companies will invest nearly $208 billion in 2025 alone, up 57% from 2020, with more than $1.1 trillion in utility capital expenditures projected through 2029. The limiting factor is what that capital is trying to buy.
Jon Najarian’s Shocking “Beyond SpaceX” Prediction
For 16 years, Jon Najarian was a fixture on CNBC’s Fast Money – known as the man in the red beret.
He called Apple in 2010, Tesla in 2014, and Palantir in 2020. Now that the SpaceX IPO is in the books, he’s making what he believes could be his most important call of the decade.
A shocking prediction about what comes “Beyond SpaceX.”
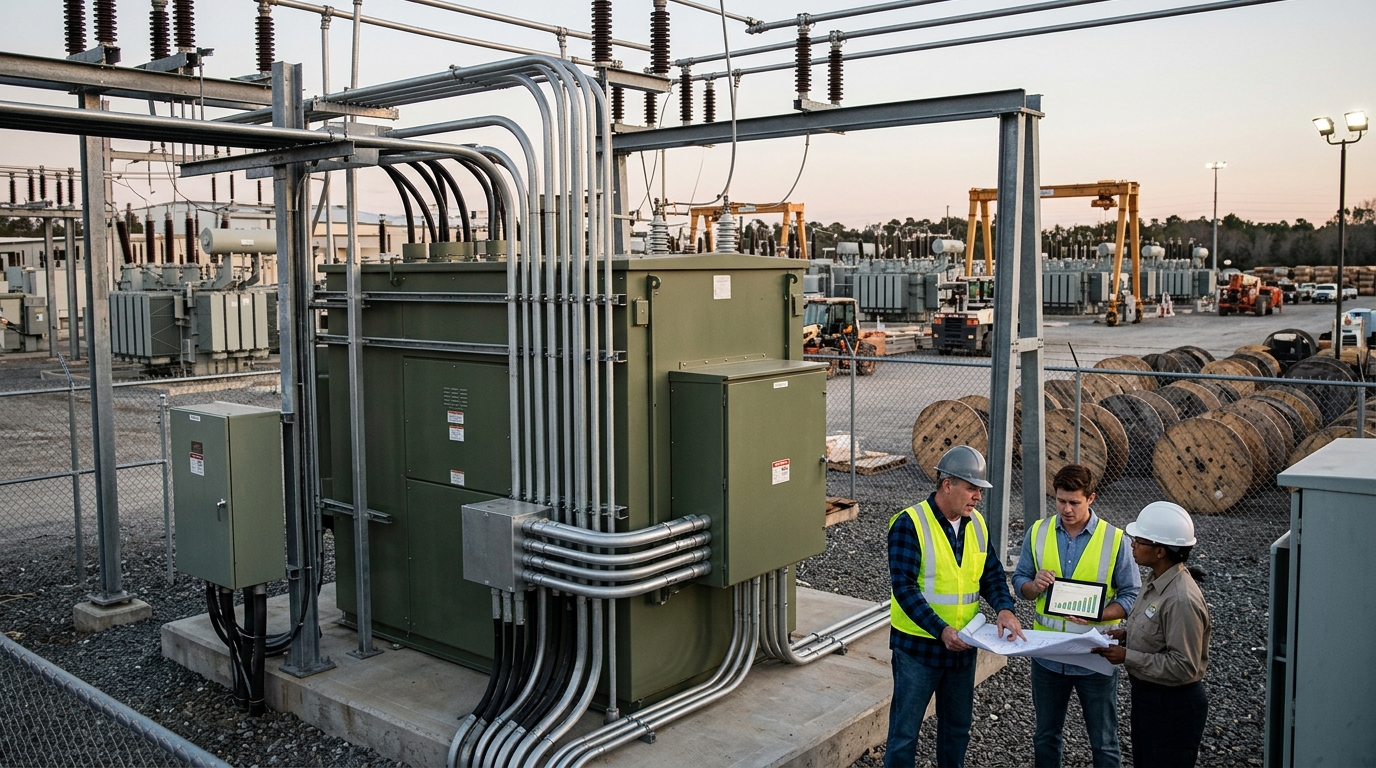
Transformers, conductor, breakers, switchgear, and substation equipment have become critical scheduling constraints. CoBank’s July 2026 review found demand for critical materials has outstripped supply, contributing to longer lead times and rising costs. Equipment that once arrived in under a year now carries lead times of three to four years.
Wood Mackenzie data shows demand for generator step-up transformers increased 274% between 2019 and 2025, while demand for substation transformers rose 116% over the same period. Switchgear has followed the same trajectory: as of May 2026, lead times for switchgear components have stretched beyond 60 weeks, up from an average of 44 weeks in late 2025. The Western Electricity Coordinating Council has flagged extra-high-voltage breakers as equipment that can take multiple years to source, directly delaying transmission projects.
The root cause sits upstream from the finished equipment. Domestic production of grain-oriented electrical steel, the core material required for transformer manufacturing, is constrained by a single producer: Cleveland-Cliffs, through its Butler Works facility in Butler, Pennsylvania, the only domestic producer of GOES. Copper windings have emerged as another bottleneck, and U.S. Section 232 tariffs raised to 50% in April 2026 are likely to worsen the issue.
The tariff decision did not arrive in isolation — it landed on top of a copper market already under structural stress from AI-driven demand and tightening mine supply. Understanding the full policy context matters for anyone modeling how transformer costs evolve from here. the Commerce report that reshaped copper tariff and supply policy walks through how phased tariffs, concentrate deficits, and data-center demand are colliding in ways that extend well beyond a single input cost.
No. 1 Stock to Buy for THIS MONDAY
Heads up: Tim Bohen’s new algorithm just uncovered a dirt-cheap stock that could DOUBLE or MORE this coming Monday. This powerful algo has already identified Monday moves of 149%, 190%, and even a whopping 536%…
Click here to see how to get positioned ahead of this Monday’s setup!
The companies positioned to capture that constrained output are compounding at a pace that earnings releases have begun to confirm. Eaton posted Q2 2026 revenue of $8.5 billion, up 21% year over year, with 14% organic growth. Data center market orders for Eaton surged 85% in the quarter. GE Vernova is booking at an even sharper rate: its backlog reached $176 billion in Q2 2026, with quarterly orders of $24.2 billion representing 88% organic growth. Data center orders alone exceeded $5 billion in the first half of 2026, more than double the company’s total for all of 2025. Hubbell, less discussed but equally exposed, reported Q2 sales growth of 15%, with Utility Solutions reaching about $1.03 billion and Grid Infrastructure growing roughly 12%.
That order acceleration is precisely why GE Vernova’s most recent quarterly report deserves a closer read than the headline number suggests. When shares sold off on an EPS miss, the backlog told a different story — one that traders focused on the wrong metric may have misread entirely. why GEV’s $176B backlog makes the EPS miss irrelevant lays out the case for why order momentum, not quarterly earnings, is the operative signal here.
The supply relief being built is real but mistimed. Hitachi Energy has committed more than $1 billion in U.S. grid equipment manufacturing investments, including a large power transformer facility expansion in South Boston, Virginia that Hitachi Energy says is expected to be the nation’s largest, with operations expected to begin in 2028. Eaton invested $340 million in a third three-phase transformer production site in South Carolina, coming online by 2027. That capacity does not solve the current shortage. Projects executing between now and 2028 face the market as it exists today.
Three Scenarios for the Component Trade
Bull Case: The DOE’s $375 million in grid supply chain funding and the Trump administration’s April 20, 2026 Defense Production Act determination accelerate domestic factory permitting. New Eaton and Hitachi capacity ramps ahead of schedule, order backlogs sustain revenue visibility into 2028, and GEV’s Electrification segment EBITDA margin expands toward the high end of guidance. ETN and GEV re-rate toward 30-plus forward earnings multiples on durable earnings growth.
#1 Power Grid Stock Right Now
In this free video, you’ll learn all about our #1 stock to buy right now as the U.S. power grid cracks. Its new tech is already live in remote fields in West Texas… and this tech is now backed by Elon Musk.
Base Case: Lead times plateau rather than compress. Wood Mackenzie projects most transformer specifications will remain in marginal shortage through 2030. Suppliers maintain pricing power, margins hold, and the order pipeline compounds steadily as utilities continue front-loading procurement. ETN sustains mid-20% segment margins; GEV delivers on its $45.5 to $46.5 billion full-year revenue guidance.
Bear Case: Tariff escalation on copper and imported GOES cores pushes transformer prices past utility budget thresholds, slowing order placement. The headline Producer Price Index was already 6.5% higher year over year in May 2026, compressing developer economics. A demand air pocket forms in 2027 as hyperscaler capex cycles reset, pressuring valuations on names already trading at premium multiples.
The copper input cost risk embedded in that bear case is not hypothetical — the raw material side of the equation is already under pressure from multiple directions simultaneously. Congo’s concentrate export ban, Chilean output falling sharply, and treatment charges near zero are all compressing the supply picture at the same time transformer demand is accelerating. how three concurrent copper supply crises are keeping the squeeze tight provides the commodity-level detail that sits directly behind the component pricing risk traders need to monitor.
Framework for Active Traders
The asymmetry in this trade is not directional on energy demand; that is consensus. It is operational, centered on which suppliers hold committed factory slots and long-term supply agreements before new domestic capacity arrives. EPC firms report being forced to redesign schedules and lock in equipment earlier than ever, as access to scarce grid components increasingly determines which projects advance and which are pushed into multi-year limbo. Watch Eaton’s Electrical Americas segment margin on the Q3 results in late October for evidence that pricing power persists as volume scales. GE Vernova’s Electrification book-to-bill, running above 2.0x in recent quarters, is the single cleanest signal for order momentum. For traders sizing exposure, the component scarcity that built these backlogs is the same force protecting them.