October 2, 2026
Nearly half of subscription cancelers cite price hikes, accelerating the billing shift that can reshape SaaS valuations.
The subscription economy’s foundational assumption, that customers set up auto-renewal and forget it, has weakened. Zuora’s Subscription Economy Index reporting around 2024 found that among consumers who canceled a subscription that year, nearly half (47%) said price increases were the reason. That behavioral shift is not a consumer story. It is a SaaS restructuring event, and the pricing model a company operates under right now is the clearest predictor of whether it survives the transition.
The Stocks That Pop 500% in Days
I’ve spent 25+ years hunting these tiny stocks. They always fire the same 3 signals first. Click here to grab the setup before the next Supernova pops 100%, 500%, or more.
Spend is still rising for many vendors because AI features are being monetized through new tiers, add-ons, and, in some cases, consumption-style charges layered on top of subscriptions. The pressure is running in both directions: buyers are cutting what they do not actively use, while vendors are simultaneously raising effective prices through bundled AI SKUs. Microsoft has introduced paid Copilot licensing and multiple Copilot options across consumer and enterprise plans, but the claim that customers must accept a mandatory AI tier upgrade to retain existing functionality is not supported as a general rule.
The NRR Gap Is the Trade
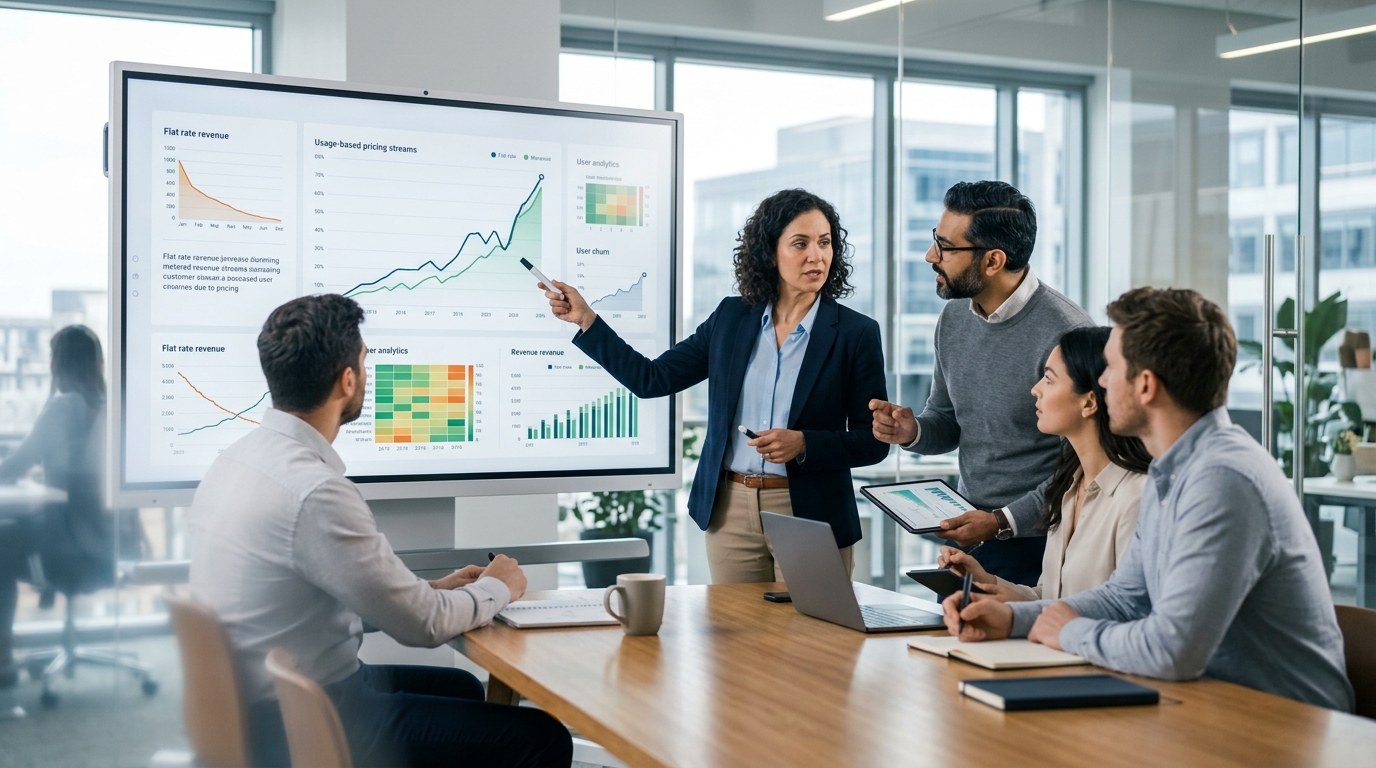
The structural argument for usage-based pricing is not philosophical; it runs through net revenue retention directly to valuation multiples. Benchmarks frequently show usage-based and hybrid models clustering higher on NRR than flat, seat-heavy pricing, but the specific claim that usage-based companies “routinely” run 115% to 130% versus 95% to 105% for flat-rate models is too absolute. A more defensible framing is that usage-based models often skew higher on expansion and can support NRR in the 110% to 130% range, while more traditional subscription and seat-based models more commonly cluster closer to the low-100s, depending on segment and scale.
NRR compounds: a company at 120% NRR grows its existing revenue base by 20% annually without new customer acquisition. That math is correct, but it assumes the metric is sustained and measured consistently across periods.
Valuation markets have already priced this divergence, but the specific “24x versus 5x” multiple claim attributed to McKinsey is not supported by McKinsey’s published public work. McKinsey has reported that higher NRR cohorts tend to carry higher EV-to-revenue multiples, and in one widely cited analysis of public B2B SaaS companies, the median EV/revenue multiple was about 21x for companies with NRR of 120% or more versus about 9x for those below 120%. Flat-subscription survivors do not simply grow more slowly; they can get re-rated into a different multiple category entirely.
Who Is Executing
Datadog is the clearest live proof point. The company prices on consumption, and the numbers reflect it. In second quarter 2026, revenue grew 36% year-over-year to $1.12 billion, with about 4,720 customers above $100,000 ARR, up from about 3,850 a year ago. Datadog does not disclose an exact trailing 12-month net revenue retention percentage each quarter, describing it as “in the low 120s,” so stating a precise 122% is too specific.
A signal the market may be missing
The CIA backed Palantir. The Pentagon bought into MP Materials. Now Washington is making another move – this time into a little-known quantum-chip company. Weeks later, executive orders reinforced the same trend.
Snowflake’s trajectory reinforces the point. The company reported product revenue of $1.23 billion in Q4 fiscal 2026, up 30% year-over-year, with remaining performance obligations totaling $9.77 billion, up 42%. The backlog build in a consumption model reflects committed spend floors with uncapped upside as workloads grow, a structure flat-fee contracts cannot replicate.
ServiceNow, Salesforce, HubSpot, and DocuSign have all expanded packaging, add-ons, and value metrics, and some have introduced credit-like or consumption-like constructs in specific areas. But the claim that usage-based pricing is “just 4 to 6% of total software spend” is not supported by a primary, broadly accepted dataset in the form stated, so it should not be presented as a hard market statistic.
Technical and Positioning Framework
For traders, the key distinction is between companies that have completed the billing architecture shift versus those running hybrid models with limited consumption revenue. Pure consumption plays like Datadog and Snowflake can carry NRR that expands with workload growth, a structural tailwind that does not require net new logo wins. Hybrid and flat-subscription names face a different setup: pricing pressure from enterprise CFO audits, margin compression risk from rapid feature bundling, and churn sensitivity that can rise when customers stop paying for what they do not use.
Scenario Modeling
Bull Case: Enterprise AI workload intensity continues growing through Q4 2026, lifting consumption volumes at Datadog above the company’s updated 2026 revenue outlook and pushing Snowflake’s product revenue growth back toward the low-30% range. NRR at pure consumption names stays in the low-120s, widening the valuation gap versus flat-subscription peers. DDOG reclaims the $135 area it held before Q2 earnings.
Base Case: Consumption revenue grows but remains a minority of total software spend through year-end. Hybrid vendors see modest NRR improvement to 108 to 112%, while enterprises continue auditing flat-fee contracts. Valuation multiples for consumption leaders hold in the mid-teens forward revenue range.
This stock “pattern” keeps showing up…
Apple crossed this one specific price line and ran 185,000% ever since.
Rigetti Computing crossed this same line, and ripped 5,770%.
Monster Beverage crossed that line too, and spiked 8,500% shortly after.
This is a pattern that’s been showing up over and over, with stock after stock.
It tells you exactly what stock to buy… when to buy it… when to sell it… and when to exit.
Giving everyday folks the chance to unlock some of the biggest and fastest gains in the market right now.
Click here to discover how to spot this “pattern” before the breakout.
Bear Case: A macroeconomic slowdown cuts cloud workload spend, exposing the revenue volatility inherent in pure consumption models. Usage-based pricing can introduce more NRR volatility because customers whose usage declines will contract automatically. If enterprise cloud optimization cycles return, consumption revenue misses guidance and the NRR premium compresses.
Active Trader Strategy Framework
The relevant spread trade is consumption-native SaaS long against flat-subscription vendors mid-transition. Monitor DDOG’s Q3 report for NRR directional signals; any sustained move higher within the low-120s range changes the growth calculus for the full sector. Watch enterprise CFO commentary in Q3 earnings calls for language around software consolidation and AI seat audits, which accelerate the migration timeline. Volatility in individual names can be wide after earnings, particularly where post-earnings reactions have been disconnected from operating fundamentals, as they were when DDOG sold off sharply despite strong Q2 numbers before stabilizing.
Position sizing should reflect the transition risk: vendors between models carry binary outcomes at renewal cycles. Flat-subscription names with NRR already below 100% are where the multiple compression thesis is most advanced and most likely to accelerate.
Preparation is the edge. The billing model shift is no longer a forecast; it is the environment. Knowing which companies have crossed the architecture threshold, and which are still explaining their roadmap, separates the trade from the noise.